


EN
NIO Stock Delivery Surge Puts EV Weight Rules In Focus
- NIO reported October 2026 deliveries of 34,246 vehicles across the NIO, ONVO and FIREFLY brands, taking cumulative deliveries to 1,332,139 as of October 31.
- The NIO All New ES8 led its large SUV and RMB400,000 level segments in China year to date. CEO William Li publicly pushed for national EV weight limits that align with the group’s focus on battery swapping and smart driving instead of ever larger battery packs.
- We will now examine how NIO's investment narrative could be influenced by strong October deliveries and William Li's EV weight comments.
Compare NIO's delivery momentum and infrastructure focus with other potential opportunities by scanning a curated list of 19 high quality undiscovered gems that may still be flying under most investors' radar.
NIO Investment Narrative Recap
To own NIO, you need to believe its multi brand approach, battery swapping network and smart driving tech can eventually support a profitable, scaled EV platform. October’s 34,246 deliveries and the ES8’s segment leadership speak to demand. However, the key near term catalyst is still clearer progress on margins and cash burn.
The biggest immediate risk remains persistent losses while NIO keeps heavy R&D and network spending in place and faces aggressive competition, especially around ONVO. William Li’s push for EV weight limits fits the infrastructure focused story but does not materially change that near term risk reward tension yet.
The clearest operational signal around this news is NIO’s October delivery update, including 18,125 NIO brand units, 8,383 ONVO vehicles and 7,738 FIREFLY cars. Those volumes matter because they test whether the product pipeline and three brand architecture are gaining enough traction to support factory utilization and fixed cost absorption.
For catalysts, you are watching whether this kind of monthly throughput can be sustained as NIO continues expanding its power network and rolling out new models such as ES9 and ONVO L80. Any stumble in execution, network utilization or pricing discipline could quickly feed through to vehicle margins, free cash flow and sentiment around the upcoming earnings release.
NIO's narrative projects CN¥173.6b revenue and CN¥4.1b earnings by 2029. This is based on an assumed 15.0% yearly revenue growth and an earnings increase of about CN¥8.9b from the current earnings, which reflect a CN¥4.8b loss.
Uncover how NIO's fair value indicates an 85% potential upside to its current price before the market closes that gap.
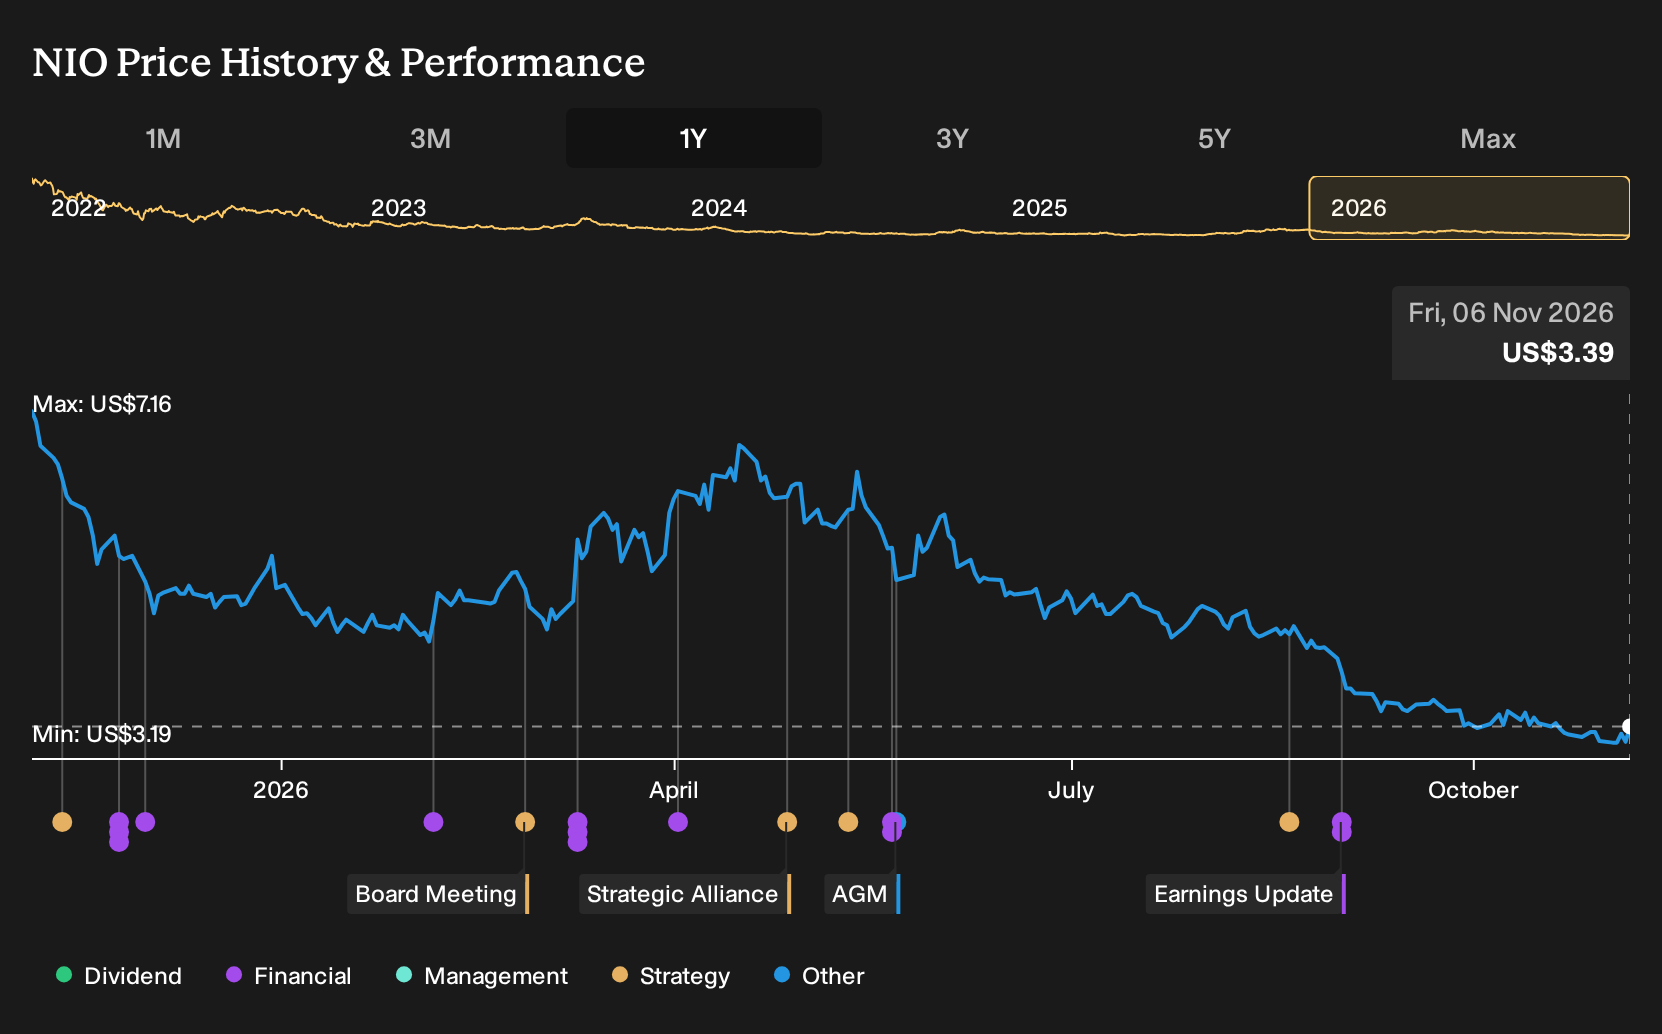
Exploring Other Perspectives
One alternate angle focuses on NIO’s revenue and earnings targets. Bearish analysts were working off roughly CN¥148.5b in 2029 revenue and only CN¥134.0m in earnings, which implies a very high P/E multiple. That view looks far more cautious than consensus and could shift if October’s delivery strength alters how you see long term profitability.
Explore 7 other NIO fair value estimates, including one that suggests it could be worth just $3.70.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NIO research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for NIO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NIO's overall financial health at a glance.
Looking For More Investment Ideas Beyond NIO?
If NIO is on your watchlist, it often helps to compare it with other opportunities that share some of the qualities you care about. The Simply Wall St Screener can surface very different types of businesses that might fit your risk appetite, income needs or preference for balance sheet strength.
- If you want to focus on valuation and quality together, scan a curated universe of 39 high quality undervalued stocks that combine solid fundamentals with potentially attractive pricing.
- For investors who care most about resilience and capital preservation, filter for 29 resilient stocks with low risk scores that score well on stability and financial risk measures.
- Income focused readers can zero in on companies with meaningful yields by reviewing 8 dividend fortresses that match a higher payout profile.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com