


EN
SharkNinja (SN) Lifted Guidance, Is The Stock Fully Priced?
SharkNinja (SN) jumped into focus after its third quarter 2026 update, with net sales at US$1.98b, higher earnings, and management lifting full year guidance while plowing tariff refunds into growth projects.
That earnings surprise and higher guidance have fed straight into SharkNinja’s momentum, with a 1 day share price return of 2.68% and a 30 day share price return of 20.39% taking the stock to US$222.95.
Zooming out, a 95.83% year to date share price return and a 1 year total shareholder return of 141.18% suggest buyers are treating the recent guidance hike and product launches as reinforcing an already strong three year total shareholder return of 431.92%.
Capitalize on SharkNinja’s earnings momentum by scanning a hand picked list of consumer-focused companies showing strong fundamentals and price strength with the 19 high quality undiscovered gems.The sharp rerating in SharkNinja after earnings rests on hefty reported sales and profit figures as well as raised guidance. Is this move mostly price enthusiasm, or a fair reset of what the business is worth?
Most Popular Narrative: 101.3% Overvalued
The leading SharkNinja narrative pegs fair value at $110.73, which sits well below the latest close at $222.95 and frames the recent surge in a very different light.
SharkNinja makes products people genuinely seem to love . My brother-in-law hasn't stopped talking about his Ninja coffee machine. Every gym-goer seems to own a Ninja ice cream maker churning out protein ice cream. And don't get me started on how everyone now owns an air fryer. This is a brand that has quietly embedded itself into daily life and that kind of word-of-mouth loyalty is genuinely hard to manufacture.
See why 8 investors see SharkNinja as 101% overvalued.
According to AshleighG, that brand strength and direct to consumer model support a long runway, yet their valuation work still lands at a fair value of $110.73 per share using a 9% discount rate. With SharkNinja trading well above that narrative estimate, the current move looks aligned with very optimistic assumptions rather than the more measured outlook in that thesis.
Result: Fair Value of $110.73 (OVERVALUED)
Still, SharkNinja’s story can break if consumer spending tightens further or if tariff and cost pressures squeeze the margins that underpin the current valuation narrative.
Find out about the key risks to this SharkNinja narrative.
Another View: SharkNinja Through The SWS DCF Lens
SharkNinja looks very different when viewed through the SWS DCF model, which puts future cash flow value at $233.80 per share versus the current $222.95. On that basis the stock screens about 4.6% below this estimate. Does that make the narrative fair value closer to a floor than a ceiling?
Look into how the SWS DCF model arrives at its fair value.
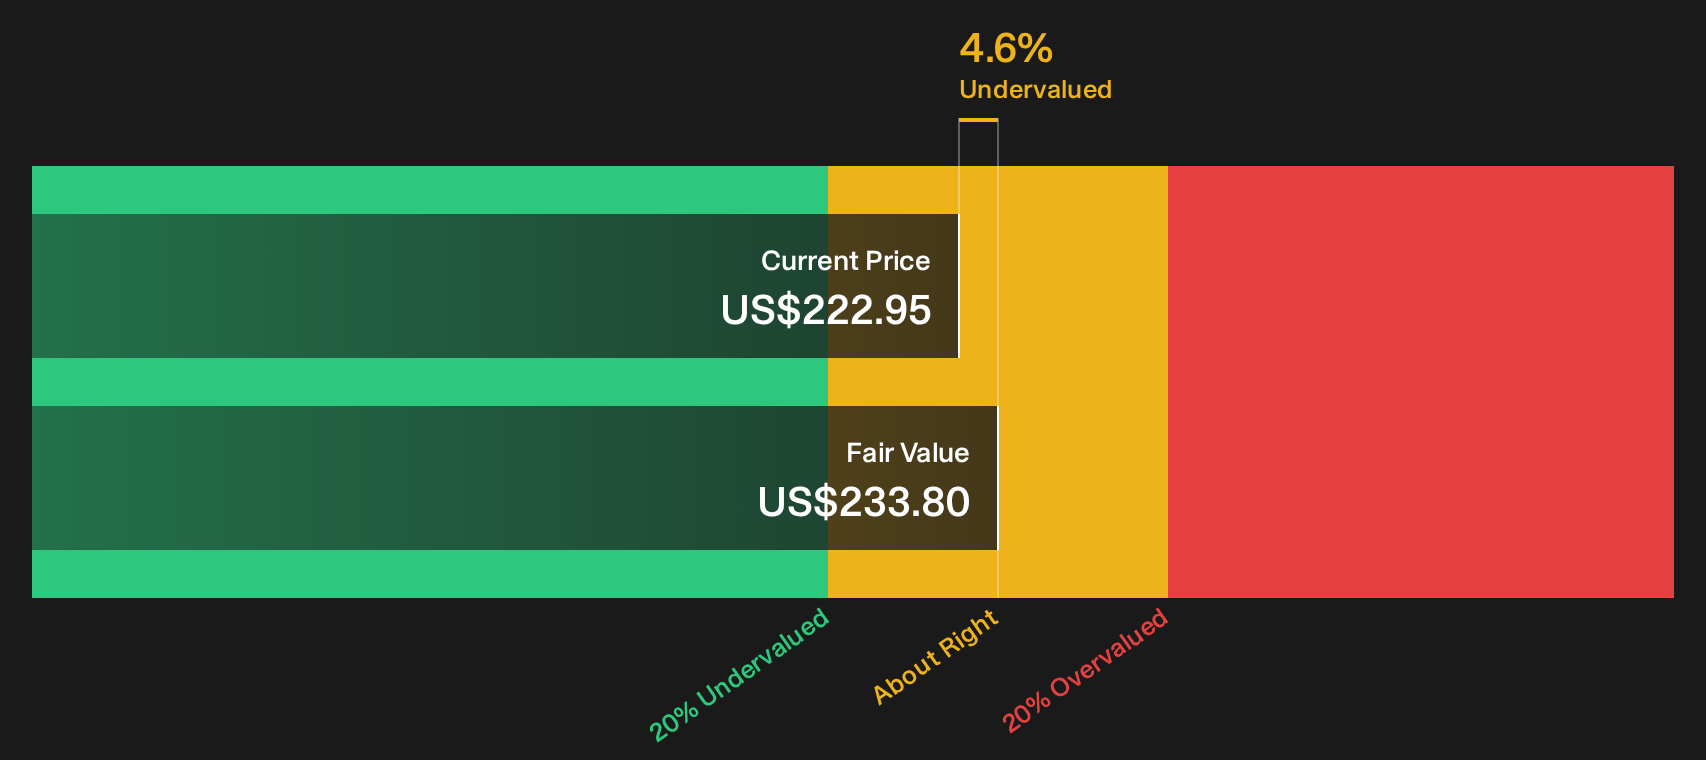
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SharkNinja for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Strong opinions on SharkNinja run both hot and cold. This is exactly why you should move quickly, pull up the full data set, and weigh the 3 key rewards and 1 important warning sign.
Looking for more SharkNinja style investment ideas?
If SharkNinja has sharpened your appetite for opportunity, do not stop here. Cast a wider net with data driven stock ideas built from the Simply Wall Street Screener.
- Target resilient compounding by scanning companies that look undervalued on both quality and balance sheet strength using the 39 high quality undervalued stocks.
- Lock in potential income streams by reviewing businesses that have paid investors with firm yields and robust coverage in the 8 dividend fortresses.
- Strengthen your watchlist with companies that pair sturdy financial footing and clean balance sheets using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com