


EN
Tonbo Imaging India And 2 Indian Insider Growth Stocks
Inflation is back on the agenda, with S&P 500 companies talking about rising costs more than at any time in over two years. Higher prices and worries about interest rates are squeezing many global businesses, yet that same backdrop can highlight Indian growth stories where insiders have serious skin in the game. This article walks through three such fast growing, high ownership stocks from our screener to help you focus your research.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders and analysts share an optimistic outlook. However, if you want the absolute best, these 43 high growth high conviction stocks are the cream of the crop.
Tonbo Imaging India (NSEI:TONBO)
Overview: Tonbo Imaging India designs and manufactures electro optical and infrared targeting systems such as thermal imaging cores and weapon sights for global defense and security customers.
Market Cap: ₹84.3b
Tonbo Imaging India ties cleanly into this screener through its thermal imaging cores and weapon sights. Earnings are forecast to grow 45.7% a year and revenue 31.8% a year, both ahead of the Indian market according to current analyst estimates. That growth story sits on top of a 138.6x P/E and elevated cash flow expectations, so much depends on how any pressure on future profitability is resolved.
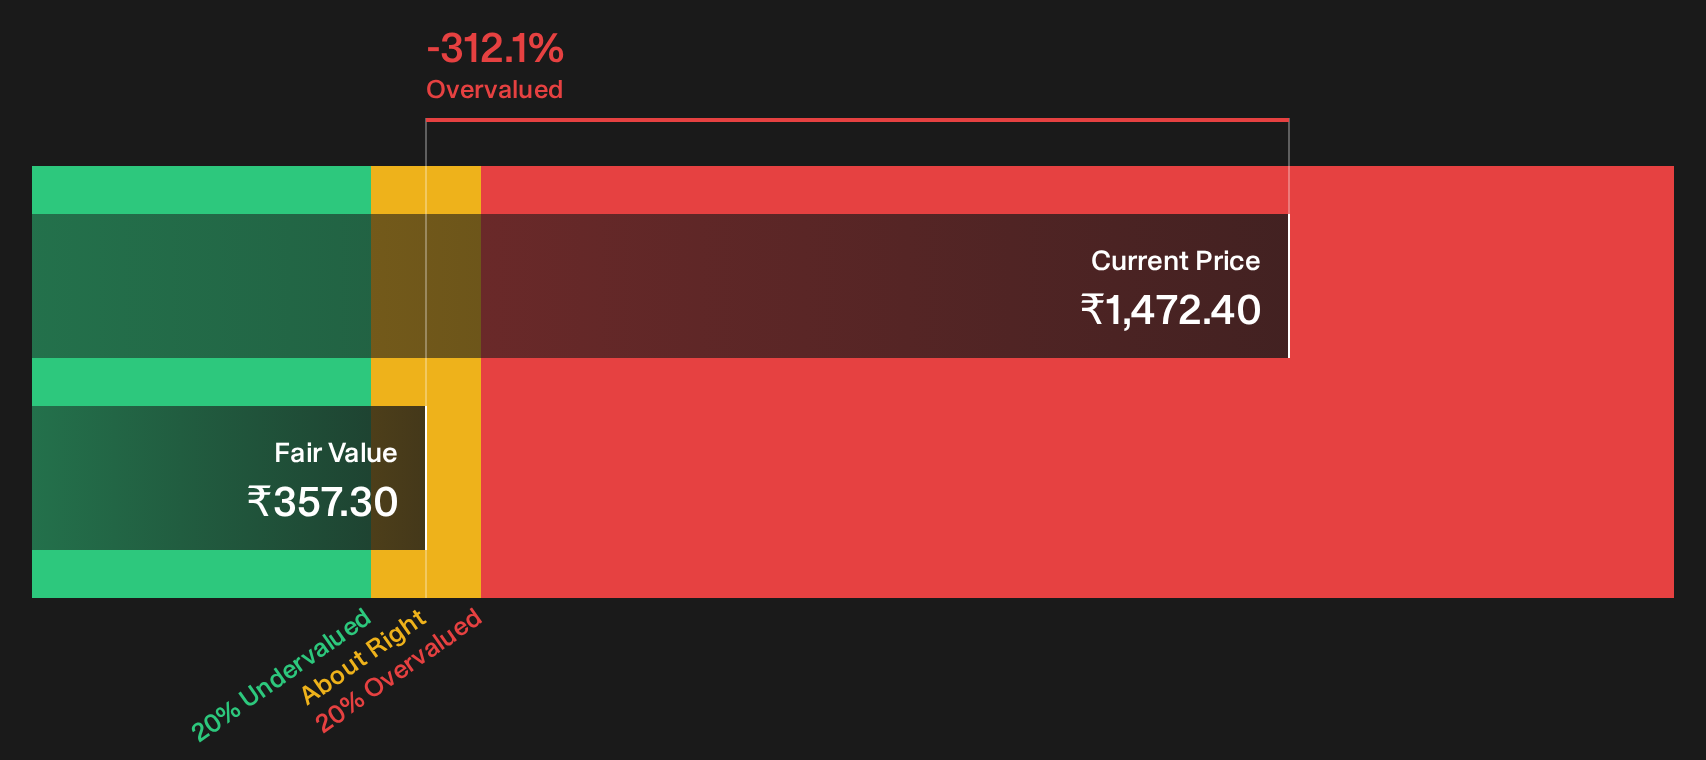
That kind of pressure makes pricing critical, so check the DCF valuation analysis for Tonbo Imaging India to see how Tonbo Imaging India’s growth assumptions stack up against that rich multiple.
Bajel Projects (NSEI:BAJEL)
Overview: Bajel Projects runs EPC contracts for high voltage power transmission and distribution lines, substations, and related steel structures and poles.
Operations: Bajel Projects generates about ₹27.5b in revenue from power transmission and power distribution EPC work and related infrastructure products.
Market Cap: ₹18.9b
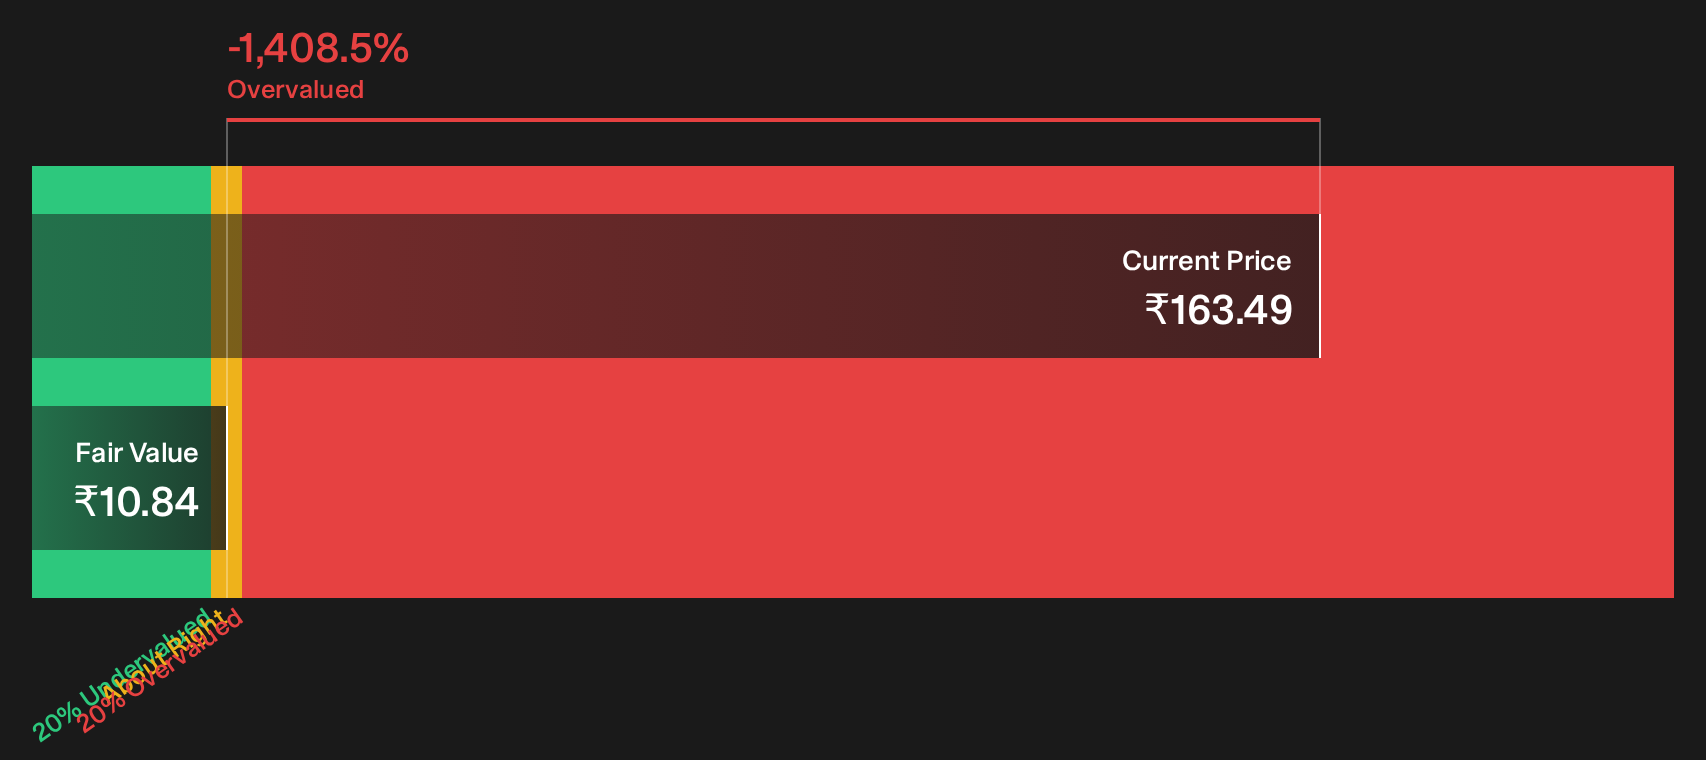
Bajel Projects plugs directly into the screener theme, with forecast earnings growth of 57.67% a year and a heavy pipeline of high voltage EPC orders. However, the stock trades on an 85.8x P/E with all liabilities funded by external borrowing, so future returns depend heavily on how one unseen pressure shapes cash generation and pricing power.
That hidden pressure is exactly why the 2 key rewards and 1 important warning sign could be crucial for judging how Bajel Projects’ leverage and growth ambitions really interact.
Syrma SGS Technology (NSEI:SYRMA)
Overview: Syrma SGS Technology provides electronics design and manufacturing services, with fast growing EMS and medtech ODM work for telecom, industrial, and healthcare clients.
Operations: The business generates about ₹63.1b from electronics manufacturing services, primarily PCBA, box-build assemblies, testing, cables, and related solutions.
Market Cap: ₹281.1b
Syrma SGS Technology taps straight into this screener’s theme, with high growth EMS and PCB assembly work where management and analysts both see room for expansion. However, the way that growth is funded has become just as important as the demand story itself.
"The decision to treat inventory as a strategic asset in response to supply chain disruption, with net working capital days rising from 63 to 71 in Q1 FY27 and short term borrowings increasing by about ₹340 crore, raises the risk that any prolonged component tightness or demand slowdown could leave Syrma SGS Technology with elevated funding needs and weaker free cash flow than current expectations assume."
What happens to Syrma SGS Technology’s earnings quality depends heavily on whether that single balance sheet choice keeps supporting, or starts dragging on, growth.
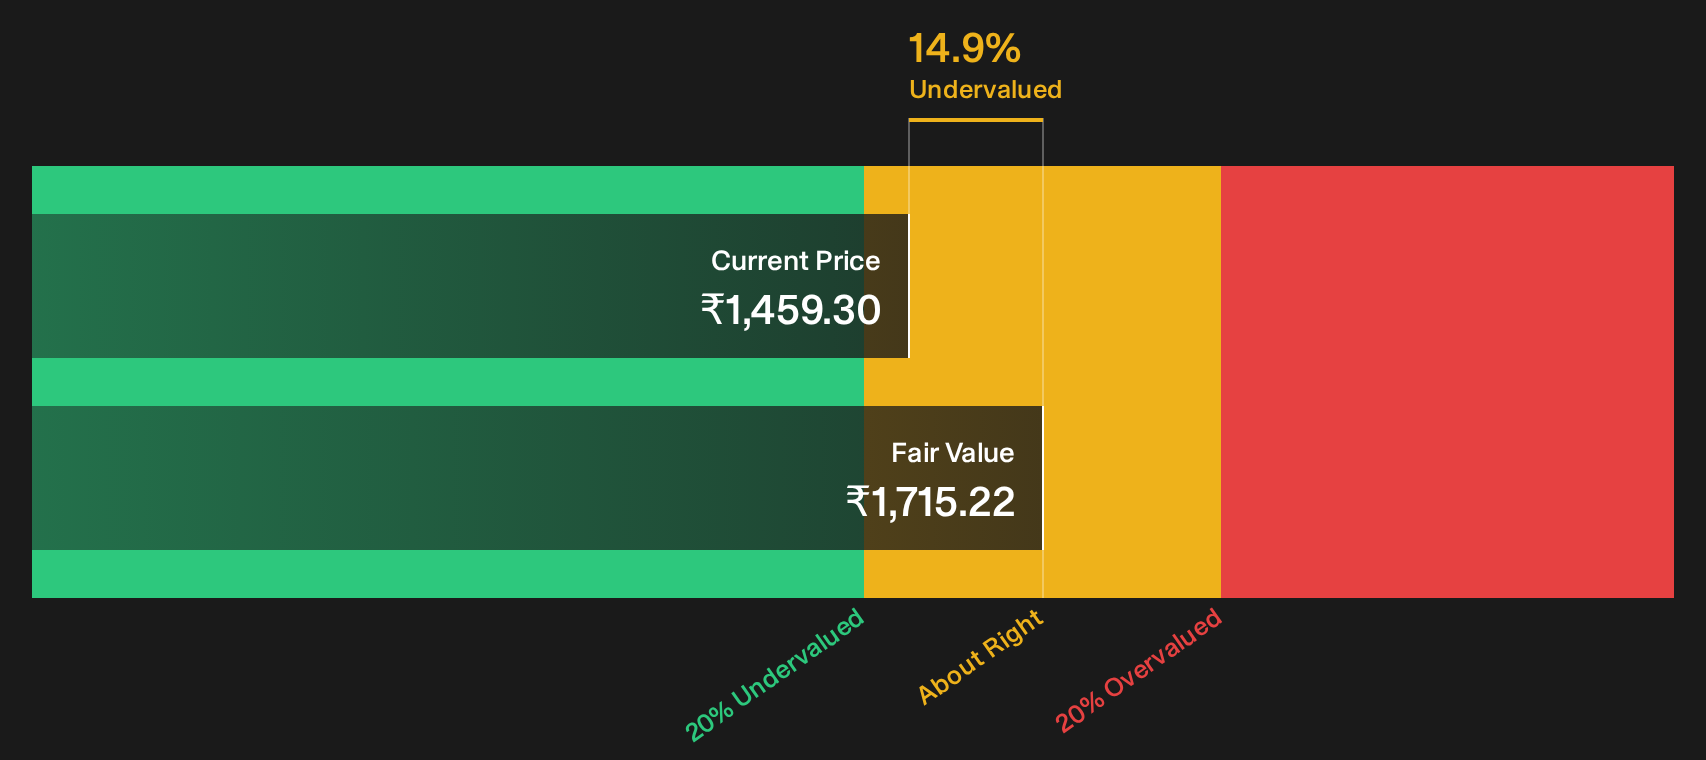
If you want to see how that funding choice could either mask or accelerate Syrma SGS Technology’s next phase, read the full narrative for Syrma SGS Technology for the full picture.
Seeking Alternatives Before Momentum Flies
Fresh opportunities can move quickly. Some tickers may be building quiet breakout momentum under the radar for now, while others risk getting caught dropping once the crowd arrives. Consider acting based on your own time frame and research process.
- Identify resilient dividend cash flows before yield-focused investors increase attention by reviewing the curated 231 dividend fortresses that focuses on sturdy payouts.
- Look for potential long-term compounders by scanning the curated 586 high quality undiscovered gems that remains underfollowed for now and shows strong balance sheets and disciplined execution.
- Evaluate opportunities related to infrastructure and electrification by checking the focused 42 power grid technology and infrastructure stocks that highlights grid technology and critical hardware suppliers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com