


EN
Ingredion (INGR) Cuts Guidance On Earnings Miss As Valuation Debate Heats Up
Ingredion (INGR) is back in focus after Q3 2026 earnings missed expectations and management cut full year guidance, citing higher costs at its Argo facility, softer North American demand, and currency pressures.
The guidance cut quickly affected sentiment. Ingredion's share price fell 5.9% on the day and is down about 16.5% year to date, while the 1-year total shareholder return has declined 12.7%. This points to fading momentum as investors reassess execution risk.
Compare how Ingredion's reset expectations stack up against other ingredient and food producers by scanning list of solid balance sheet and fundamentals (24 results) that have weathered recent earnings shocks more resiliently.
Bulls see Ingredion as a temporarily mispriced earnings story, while bears see a structurally challenged ingredients supplier with rising execution risk. Which side does the current valuation actually support?
Most Popular Narrative: 4% Overvalued
Ingredion's most followed narrative puts fair value at $88.23, slightly below the last close at $91.72, which lines up with a modest 4% premium to that estimate and frames today’s pullback as a debate about how much to pay for a steady earner.
The acquisition of Tate & Lyle has the potential to transform Ingredion from a predominantly commodity-oriented starch and sweetener processor into a more global specialty ingredients platform. The primary upside comes from mix shift toward higher-margin functional ingredients, meaningful cross-selling opportunities with global CPG customers, and scale-driven cost synergies.
See why 9 investors see Ingredion as 4% overvalued.
Result: Fair Value of $88.23 (OVERVALUED)
Still, the Ingredion story breaks quickly if the Tate & Lyle integration drags on returns or if weaker North American demand turns into a longer volume reset.
Find out about the key risks to this Ingredion narrative.
Another View: What Ingredion's P/E Is Telling You
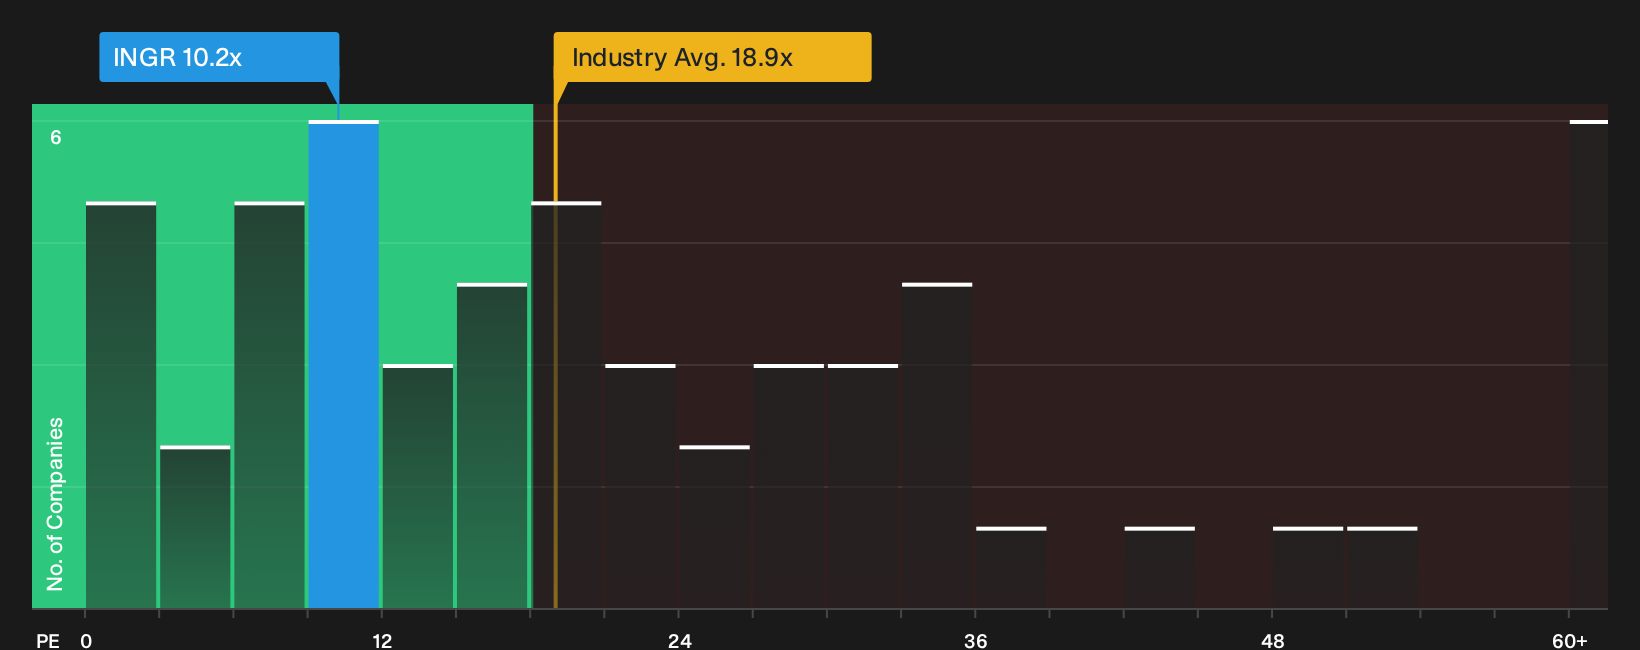
There is a different message when you look at Ingredion through its P/E ratio. The stock trades at 10.2x earnings compared with 18.5x for the broader US Food industry and 13.8x for peers, while the fair ratio is 18.4x. This suggests the market is pricing in plenty of execution risk already.
If that gap ever narrows toward the fair ratio, today’s valuation could look conservative. However, if margins stay under pressure, the discount may prove justified. Which possibility do you think the current earnings multiple is really pointing toward?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this piece might feel cautious, yet the market is rarely that simple. Move quickly to review the upside case and weigh the 5 key rewards.
Looking for more investment ideas beyond Ingredion?
If Ingredion has sharpened your focus on valuation and risk, you should not stop here. Fresh ideas often come from looking just one step further.
- Target reliable cash generators by scanning the 39 high quality undervalued stocks that combine appealing valuations with stronger fundamentals.
- Strengthen your income stream by reviewing the 8 dividend fortresses that aim for robust payouts supported by underlying business performance.
- Protect against downside surprises by filtering for the 29 resilient stocks with low risk scores that score well on balance sheet strength and risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com