


EN
Five Below (FIVE) Faces Squish Toy Questions, Is The Stock Expensive Or Undervalued?
Analyst Commentary Puts Five Below’s Toy Trend Under the Microscope
Fresh remarks from Truist Securities on Five Below (FIVE) have put the retailer’s popular squish toy trend under scrutiny, while also highlighting internal process changes that prompted higher projections for sales and earnings.
Recent trading has reflected that debate. Five Below’s share price has climbed over the past month, with a 30 day share price return of 17.66% and a year to date share price return of 24.22%. The 1 year total shareholder return of 57.80% and 3 year total shareholder return of 35.99% point to stronger longer term gains compared with the more mixed 90 day share price move, hinting that momentum has cooled in the short run even as longer horizon investors have still been rewarded.
Patrol the wider discount retail space by scanning hand picked peers with solid fundamentals and potential momentum using the list of solid balance sheet and fundamentals (24 results).For Five Below, that sharp 1 year gain alongside a flatter 90 day stretch raises a simple tension: Are investors now pricing in real business progress, or just swinging with sentiment ahead of the next set of valuation checks?
Most Popular Narrative: 23% Undervalued
Five Below’s most followed narrative pegs fair value at $310.48 per share, well above the last close at $240.30. This puts the spotlight on whether the current price fully reflects its expansion and capital deployment plans.
The main thing that has to go right is that Five Below continues to convert its store expansion runway, higher price point mix, and new store experience investments into healthy traffic, strong new store productivity, and resilient customer value perception despite rising cost and legal pressures.
See why 15 investors see Five Below as 23% undervalued.
Result: Fair Value of $310.48 (UNDERVALUED)
Still, rising fuel and trucking expenses, along with ongoing legal and regulatory actions, could pressure Five Below’s margins and weaken confidence in that 23% undervaluation story.
Find out about the key risks to this Five Below narrative.
Another View: Five Below Looks Expensive On Earnings
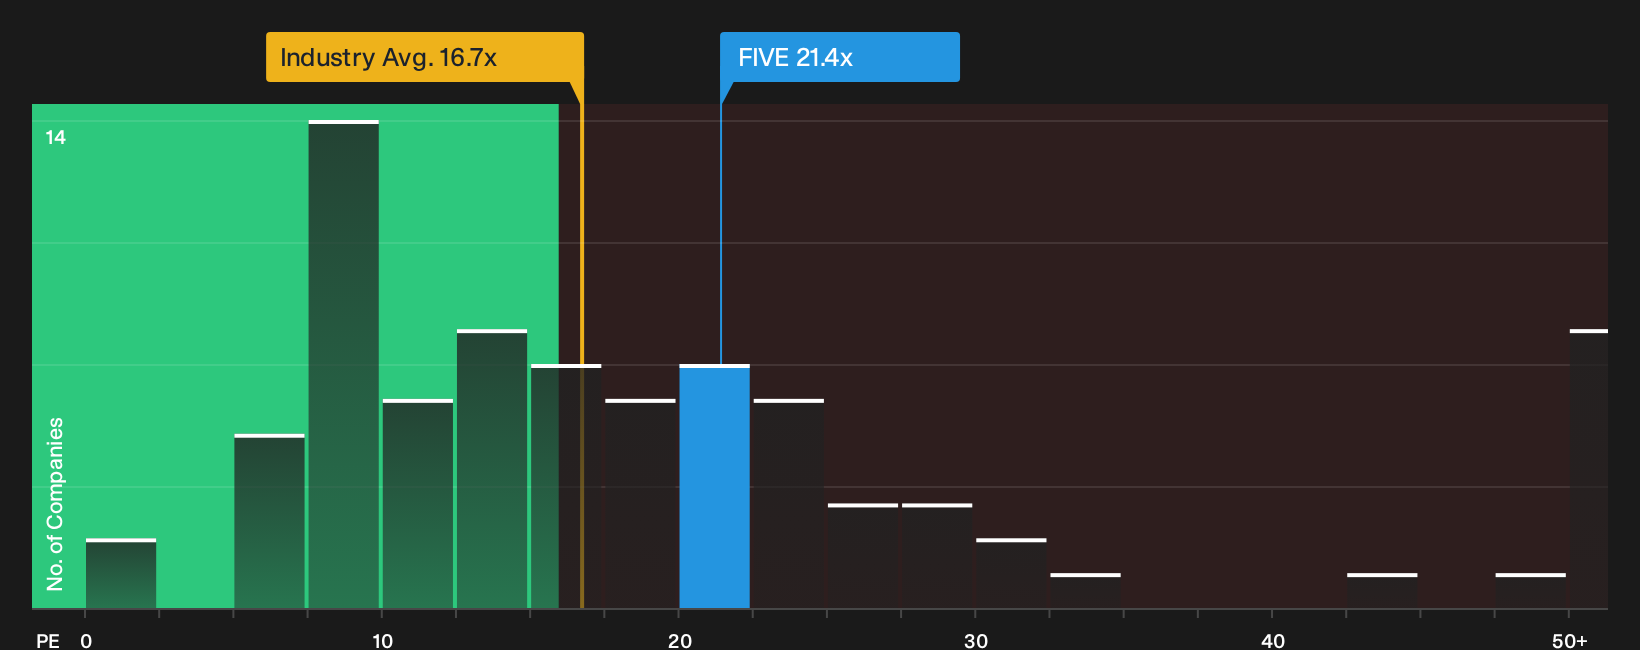
That 23% undervaluation story runs into a very different message when you look at Five Below through its P/E. The stock trades around 21.4x earnings, above the US Specialty Retail group at 16.9x and above its own fair ratio of 15.2x. This points to valuation risk if expectations slip.
To see how this earnings based view compares with a more detailed cash flow approach, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Five Below can either feel like noise or a useful stress test of your own thesis. Press into the data yourself and weigh both the concerns and the upside potential by reviewing the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Five Below?
Do not stop your research with Five Below. Broaden your watchlist with targeted ideas that match different goals so you are not relying on a single story.
Scan for dependable balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (24 results).
Hunt for mispriced opportunities that pair quality with a possible valuation gap through the 39 high quality undervalued stocks.
Target income focused opportunities that aim to combine higher yields with resilience using the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com