


EN
Missed ABN AMRO Bank's Run? What Holders Had To Believe
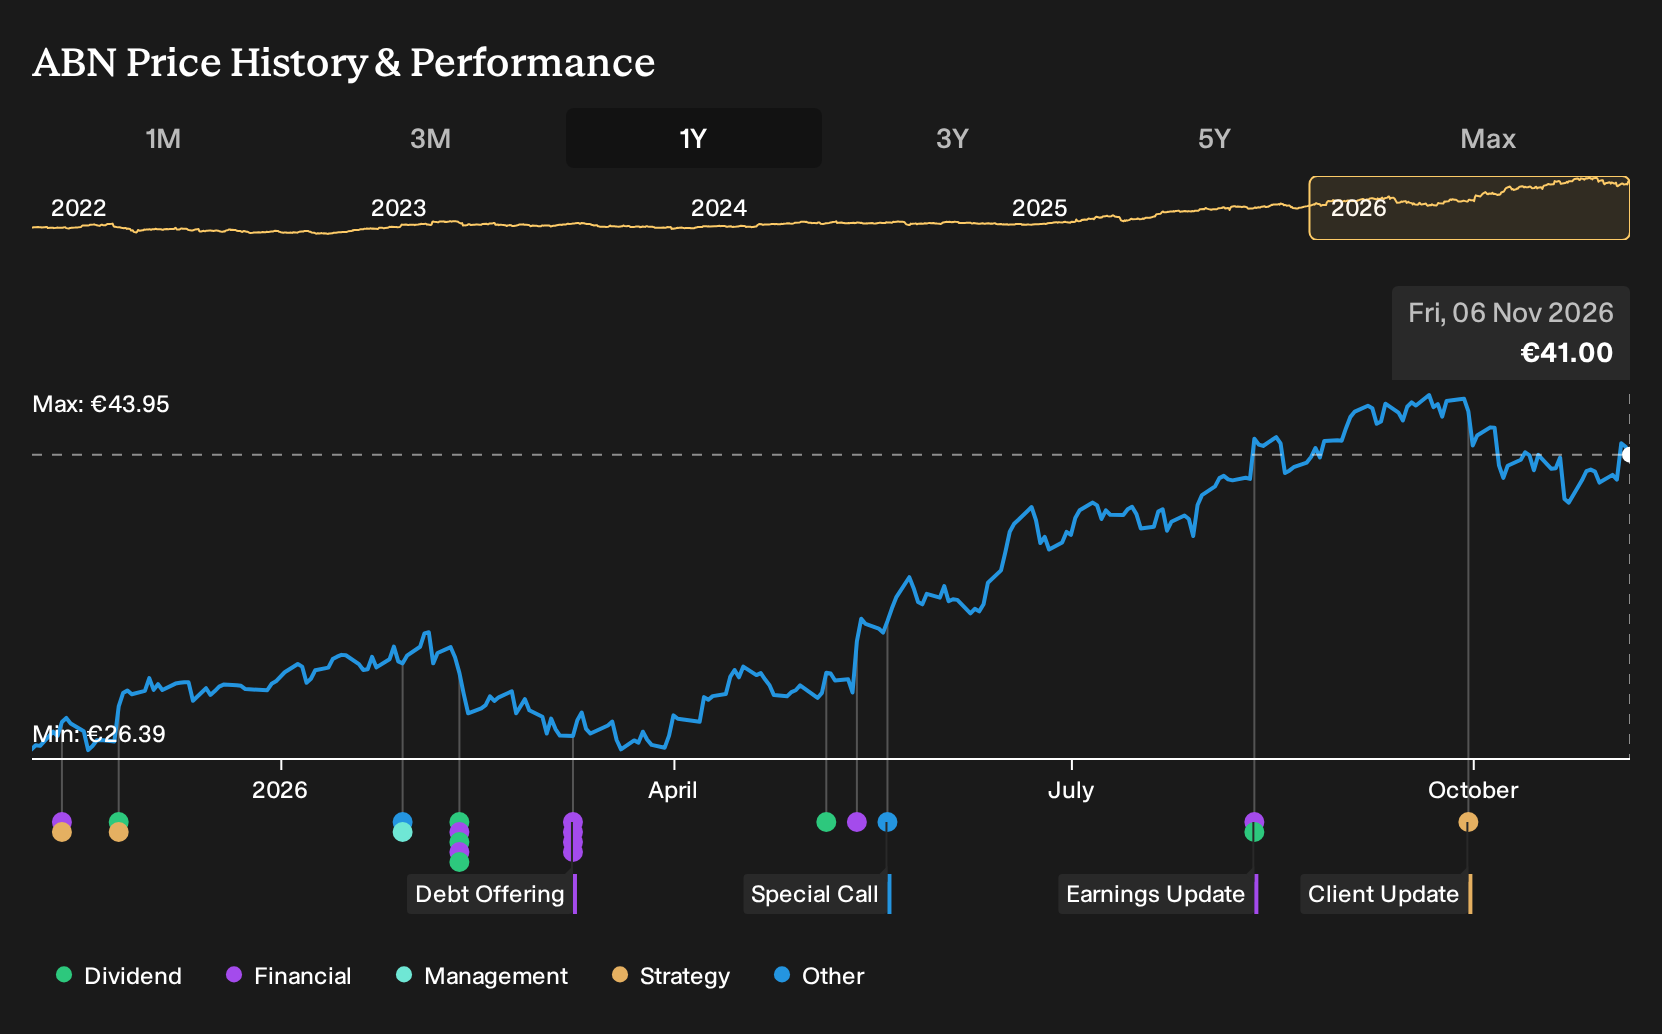
If you only glanced at ABN AMRO Bank’s headlines this year, you saw a mix of strong quarterly profits, regulatory fines, AI partnerships, and even staff strike threats. Holding ABN AMRO Bank over the past year would have returned 62.2%, including dividends. If you had been weighing that decision back on 6 November 2025, with bulls and bears split almost €11 apart on fair value, what would you have focused on to judge the trade off between digital ambition and regulatory risk?
The easy part of this move is behind ABN AMRO Bank. Zero in on 224 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing On ABN AMRO Bank
The shares cost €26.63 at the start of the period, so every call on ABN AMRO Bank came down to which story about the future you trusted more.
The bullish narrative pointed to a Fair Value of €29, a rough guide to what the stock might be worth if stronger digital fees and lower costs came through. It leaned on assumptions such as resilient deposit volumes supporting higher net interest income.
The bearish view set Fair Value at €17.3 and treated the same facts as warning signs. It stressed risks such as declining revenue of 0.8% a year and shrinking profit margins toward 18.5% as fintech rivals and ESG pressures squeezed returns.
What The Results Changed For The ABN AMRO Bank Debate
ABN AMRO Bank’s Q2 2026 results showed revenue of €2,400 million and net income of €781 million, compared with €2,147 million and €606 million in Q2 2025, with net margin rising from 28.2% to 32.5%. That combination supported the bullish view that cost cuts and fee growth could lift profitability, while the €8.5 million AML fine kept the regulatory risk in the bearish case alive. Overall, the evidence cut both ways.
The hinge assumption here was whether efficiency gains would outweigh compliance drag. For any other bank, you would test that by tracking cost guidance, reported operating expenses and net margin trends against each side of the original thesis.
What ABN AMRO Bank’s Price Now Asks You To Believe
With the share price at €41, this Narrative’s Fair Value sits below the current price. This means it treats ABN AMRO Bank as fully pricing in a lot of good execution.
The Narrative hinges on mortgage margin pressure, compliance costs and AI driven efficiency. A buyer today is effectively assuming cost savings and fee growth hold up. How secure do those expectations look beside the compliance and housing market risks in the selected Narrative?
"Although ABN AMRO Bank is rolling out around 50 AI use cases with higher than planned software development efficiency gains and dedicated tools for KYC and AML analysts, the recent fine for serious and structural AML control failures suggests compliance processes may still lag regulatory expectations, which could require additional investment and weigh on net margins."
The price and this Narrative do not agree. → Uncover what this Narrative says ABN AMRO Bank is actually worth
Looking Beyond ABN AMRO Bank
Once you understand ABN AMRO Bank’s trade off, another angle appears.
Your deposits and payments still need a stable home as AI and security needs grow more complex.
One major global institution leans into that demand, uniting consumer banking, markets activity, and transaction processing.
Its role is to help clients move money, raise capital, and manage risk, even with heavier technology commitments.
If that broader model keeps drawing activity, it could reshape how investors compare ABN AMRO Bank with global peers.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 25% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com