


EN
Does Record Earnings Change The Bull Case For Royal Gold Stock (RGLD)?
- Royal Gold reported record third quarter 2026 results, with sales of US$461.27 million and net income of US$227.42 million, supported by strong operating cash flow and a debt free balance sheet.
- The business paired record earnings with full repayment of its revolver, leaving about US$1.4 billion in available liquidity for future royalty and streaming opportunities.
- This article examines how Royal Gold's record revenue and debt free position could influence the existing investment narrative around the stock.
Scan how Royal Gold's record quarter compares with other miners by reviewing the hand picked 33 elite gold producer stocks that share strong cash generation and balance sheet strength.
Royal Gold Investment Narrative Recap
To own Royal Gold, you need to be comfortable with a royalty and streaming model that leans on long reserve lives, high EBITDA margins of about 83%, and a broad pipeline of projects rather than operating mines directly. The record Q3 and nine month results, plus a debt free balance sheet, support that model without dramatically changing the near term story.
The key near term swing factor remains how effectively Royal Gold converts its development pipeline into producing streams while keeping capital allocation disciplined. The biggest risk is that recent earnings strength proves lumpy, which, paired with past estimate cuts and insider selling, could keep confidence in the earnings trajectory more fragile.
The clearest link to the latest quarter is Royal Gold’s unchanged 2026 volume guidance for gold, silver, and copper. Management is effectively saying recent record revenue and cash generation are being delivered within previously outlined production expectations. This points attention back to price, portfolio mix, and deal flow as the levers investors are watching.
For catalysts, that steady guidance shifts the focus to execution on new royalty and streaming opportunities, especially with about US$1.4b of available liquidity and no debt. Any issues at producing assets, such as operational interruptions like the Antamina suspension, underline how volume reliability across the diversified portfolio remains a central operational risk to track.
Royal Gold Forecasts And Valuation Anchors
Royal Gold's story now rests on what analysts think the next few years look like on paper. The record quarter gives you a high quality snapshot, while the consensus forecasts sketch out where the income statement could head by the end of the decade.
Royal Gold's narrative projects US$2.1b revenue and US$1.2b earnings by 2029. This assumes 11.8% yearly revenue growth and an earnings increase of about US$462m from US$738.0m today.
Analysts are effectively building their models around profit rising from US$738.0m today to US$1.2b by 2029, with profit margins moving from 48.1% toward 56.5%. That combination implies the business would convert a larger share of its projected US$2.1b top line into bottom line profit, which matters more to long term shareholders than revenue alone.
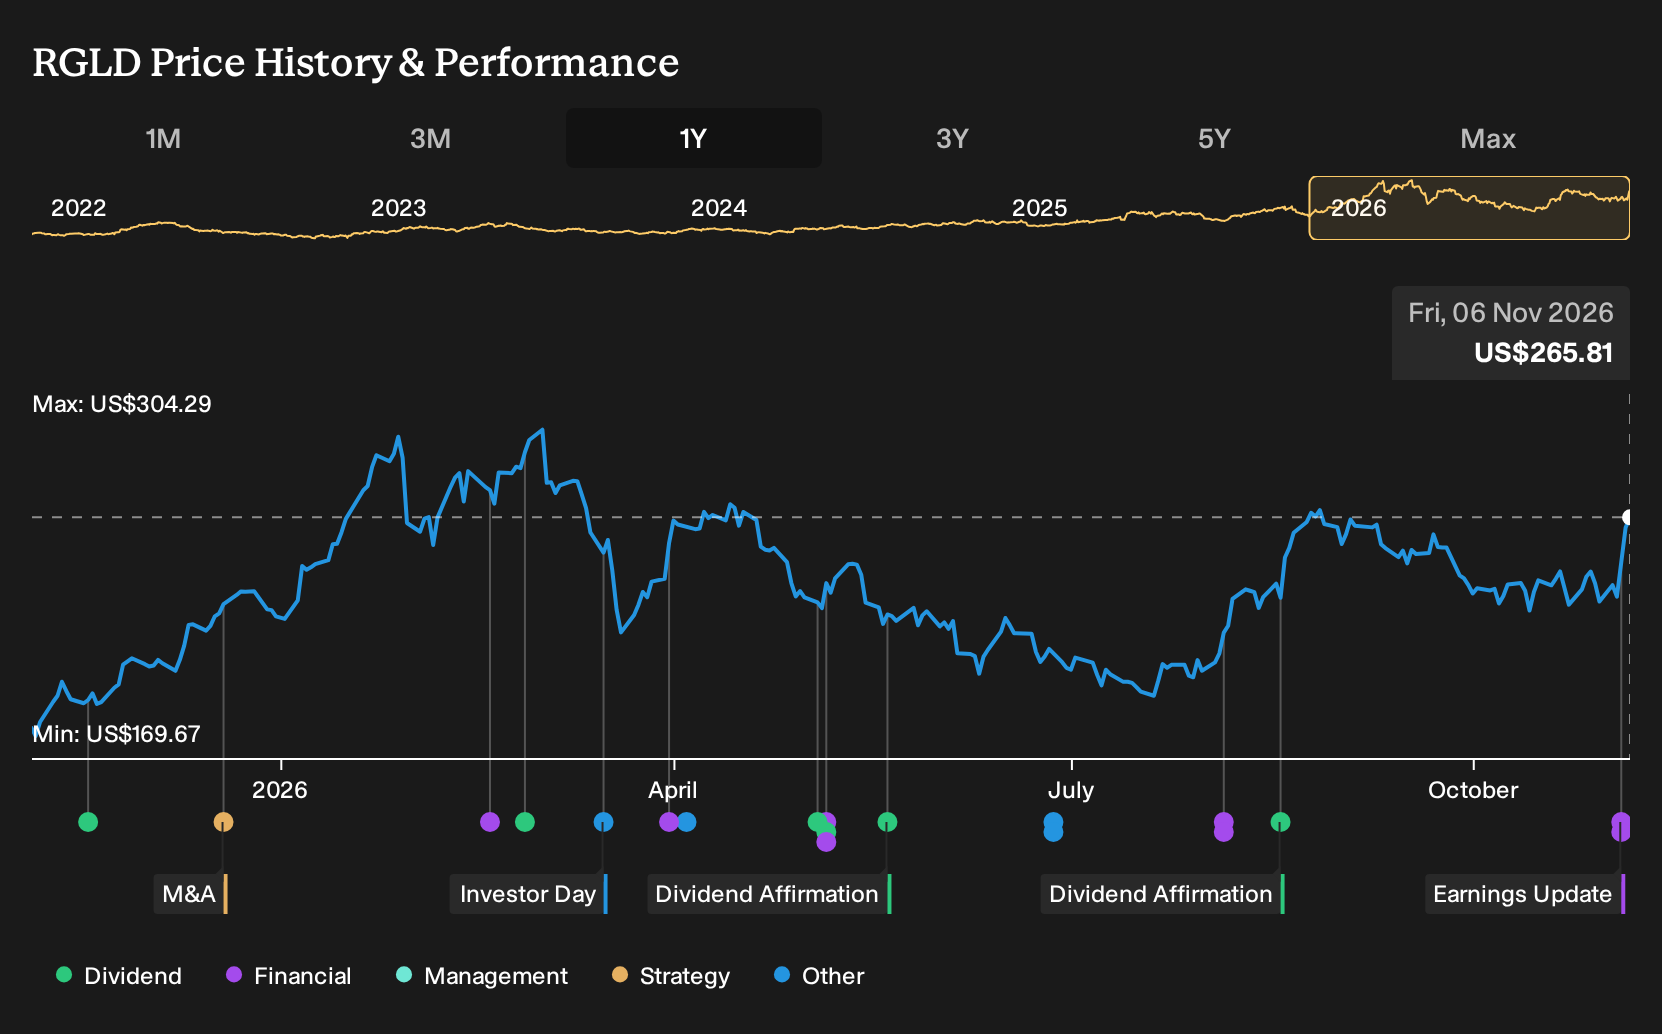
The price targets in the current research range from US$218.0 to US$380.0, with a consensus of US$309.83 against a share price of US$234.64 as of the latest report. To line up with that central target, investors would need to assume Royal Gold trades on a P/E of 28.2x in 2029, compared with 26.9x today and 19.9x for the broader US Metals and Mining group.
That higher implied P/E multiple, combined with the forecast revenue compound rate of 11.8% and the larger earnings base, shows how much of the current Royal Gold thesis rests on sustained royalty and streaming growth rather than a one off record quarter. It also makes the execution risks around volume reliability, deal quality, and disciplined use of the roughly US$1.4b liquidity pool more important when you stress test those projections.
Uncover how Royal Gold's fair value indicates a 17% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate Royal Gold story puts far more weight on rising costs per gold equivalent ounce and higher DD&A as the key risk. Those cautious analysts were still penciling in about US$2.2b of 2029 revenue and roughly US$1.2b of earnings before this record quarter, yet their lower price targets show how sharply opinions can split. Use this earnings beat as a prompt to compare both playbooks and decide which assumptions fit your own view.
Explore 5 other Royal Gold fair value estimates, including one that suggests there could be as much as 12% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Royal Gold research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Royal Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Royal Gold's overall financial health at a glance.
Looking for more Royal Gold style ideas?
If the Royal Gold story has sharpened your thinking about quality, income, and risk, you can use this momentum to widen your watchlist with a few focused stock searches.
- For investors who care most about valuation support and strong fundamentals, start with a curated group of 39 high quality undervalued stocks that already combine quality and pricing discipline.
- If capital preservation and a smoother ride matter more to you than chasing every high flyer, concentrate on a focused pool of 29 resilient stocks with low risk scores that score well on resilience.
- When you want balance sheet strength and solid operations to sit at the center of your process, zero in on a targeted list of solid balance sheet and fundamentals (24 results) that can broaden your opportunity set beyond Royal Gold.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com