


EN
Arcadis (ENXTAM:ARCAD) Wins Major Infrastructure Roles, Is The Stock Still Below Fair Value?
Arcadis (ENXTAM:ARCAD) just landed two major infrastructure roles, including Operator's Engineer for the Contrecœur Container Terminal in Montréal, highlighting its engineering capabilities for investors who follow long term project pipelines.
These wins arrive as Arcadis trades at €46.2, with a share price return of almost 30% year to date and a 1 year total shareholder return of about 33%. This suggests momentum has built over 2026, even as investors weigh contract driven growth against execution and project risk.
Scan beyond Arcadis and track other infrastructure and engineering plays that combine long project backlogs with resilient balance sheets using our hand picked list of solid balance sheet and fundamentals (193 results).
Arcadis now sits on a strong run of contract wins and a share price that has climbed about 30% in 2026. How much of that move reflects sturdier fundamentals, rather than a mood shift in the market around infrastructure plays?
Most Popular Narrative: 50% Undervalued
Against the most widely followed narrative fair value of €46.44, Arcadis at €46.20 screens as slightly below that mark and well below the €115.95 future cash flow value used in the same framework. This puts recent contract momentum in the context of a still discounted long term story.
Capital light, cash generative economics, reflected in low annual capex of €20 million to €30 million, improving working capital metrics such as DSO and book to bill above 1x, and stated intentions to convert a high share of operating EBITDA into free cash flow, provide room for dividends, selective bolt on M&A and potential buybacks, which can influence earnings per share.
See why 28 investors see Arcadis as 1% undervalued.
Result: Fair Value of €46.44 (UNDERVALUED)
Still, the Arcadis narrative can shift if the Reset program underdelivers on margin gains or if ongoing weakness in Places continues to weigh on group performance.
Find out about the key risks to this Arcadis narrative.
Another View: Arcadis Through The P/E Lens
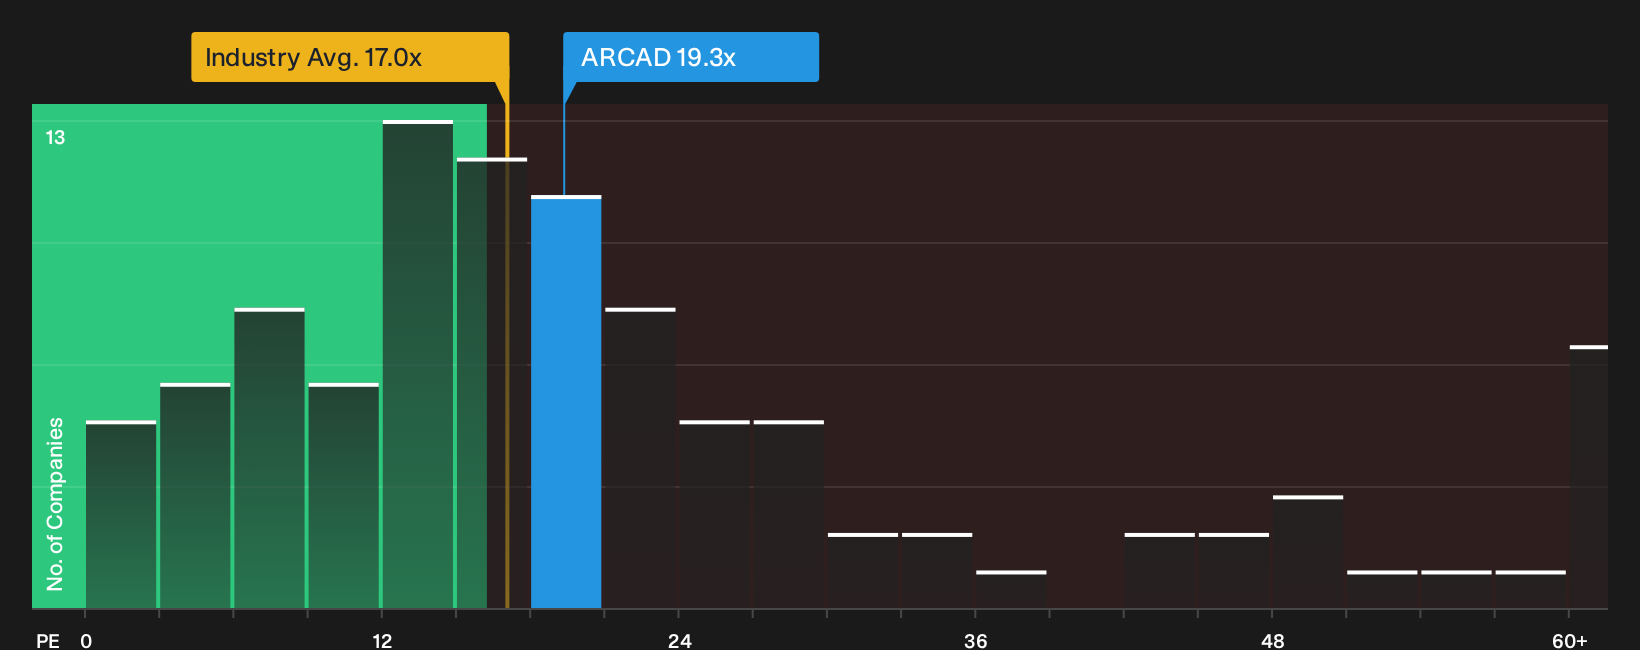
Look past the discounted cash flow output and the picture shifts. On a P/E of 19.3x, Arcadis trades above the European Professional Services average of 17.3x yet below a fair ratio of 21.3x and the peer average of 25.9x. That mix of premium and discount raises a simple question: Is the risk bigger that expectations are already full, or that the market edges closer to the higher peer and fair ratios over time?
To see how this earnings multiple story stacks up against other companies with similar metrics, take a look at the valuation breakdown in our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across Arcadis valuation, contract momentum and perceived execution risk can feel messy, so move quickly and pressure test the data against your own framework using our 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Arcadis?
Do not stop your research at Arcadis. Fresh opportunities often sit just outside the obvious shortlist, and missing them can hold back your portfolio over time.
- Target potential mispricings by scanning a curated set of quality companies through the 224 high quality undervalued stocks that filters for fundamentals, not hype.
- Strengthen your income stream by reviewing resilient payers in the 232 dividend fortresses that focuses on higher yielding businesses with support from underlying cash flows.
- Protect your downside by checking the 212 resilient stocks with low risk scores that highlights businesses with sturdier balance sheets and calmer historical risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com