


EN
Is Weak Q3 Earnings Altering The Investment Case For Owens Corning Stock?
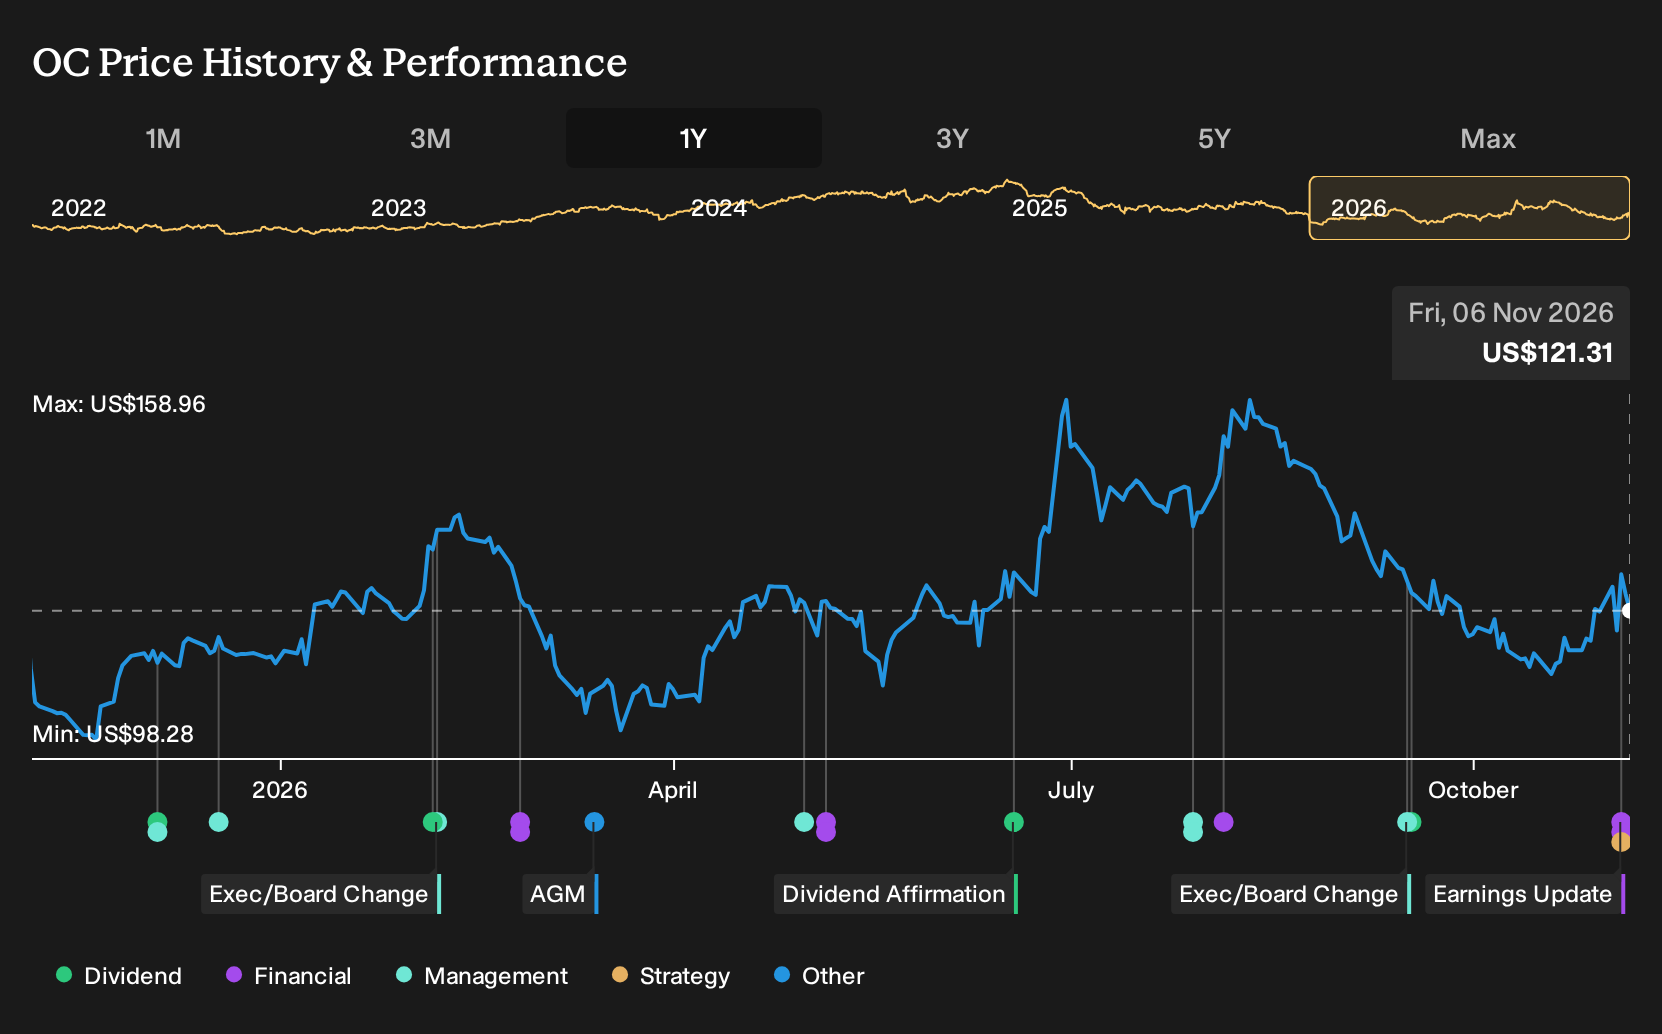
- Owens Corning reported third quarter 2026 sales of US$2.489b and a net loss of US$250 million, with results affected by weaker residential demand, inflationary transportation and material costs, and sizeable non cash impairment charges in its Doors business.
- The construction materials group paired those headline losses with a 20% adjusted EBITDA margin, US$622 million of free cash flow, and plans for new low cost production assets. This indicates that management is focusing on efficiency and capital investment while issuing cautious fourth quarter revenue guidance of US$2.0b to US$2.2b.
- We will now look at how Owens Corning's investment narrative is shaped by these weak Q3 results and sizeable impairment charges.
Scan beyond Owens Corning and evaluate other construction focused plays that face similar demand and cost pressures with our hand picked list of solid balance sheet and fundamentals (24 results).
What Is Owens Corning's Investment Narrative?
Owens Corning appeals to shareholders who buy into a fairly simple idea. You are backing a construction materials platform with meaningful exposure to Roofing, Insulation, and Doors, where execution on costs, plant efficiency, and capital projects matters as much as end market demand. The latest quarter fits that script. Weak residential activity and inflation in freight and inputs pressured reported earnings, yet adjusted EBITDA margins held at 20% and free cash flow reached US$622 million, which helps fund those new low cost production assets.
The impairment in the Doors segment and cautious Q4 revenue outlook of US$2.0b to US$2.2b put the key short term swing factors in sharp focus. In the near term, the story hinges on how Owens Corning manages downtime, inflation, and pricing in Roofing and Doors while keeping Insulation momentum intact. Bigger risks sit around the firm’s high debt load, an uncovered 2.6% dividend, and the fact the group is currently loss making, so any stumble on execution or housing demand can feed directly into the equity case.
Yet all of that operational progress sits alongside one uncomfortable pressure point that could matter far more if ...
There's only one way to know the right time to buy, sell or hold Owens Corning. Head to Simply Wall St's company report for the latest analysis of Owens Corning's Fair Value.
Exploring Other Perspectives
Some of the most optimistic analysts were treating Owens Corning’s Doors integration as a clear earnings lever, baking in Q2 adjusted EBITDA of US$660 million on US$2.8b of revenue and projecting profit margins rising from 4.4% loss levels to 15.0%. You can see how that upbeat story may now be tested, so it is worth comparing several viewpoints before deciding how this earnings miss and impairment change your own thesis.
Explore 2 other Owens Corning fair value estimates, including one that suggests there could be as much as 59% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Owens Corning research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Owens Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Owens Corning's overall financial health at a glance.
Looking For More Investment Ideas Beyond Owens Corning?
Owens Corning might be the focus today, but your portfolio probably needs a broader bench of opportunities. Use the Simply Wall St screener to quickly surface companies that fit different risk, income, and quality profiles, then pressure test them against your own framework.
- If you want income to do more of the heavy lifting, scan for companies offering reliable payouts with our curated 8 dividend fortresses.
- For investors who care most about balance sheet strength and fundamental resilience, focus your next watchlist refresh around the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for under followed potential, broaden your opportunity set with a hand picked pool of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com