


EN
Jana Push Could Be A Big Moment For Casella Waste Systems Stock (CWST)
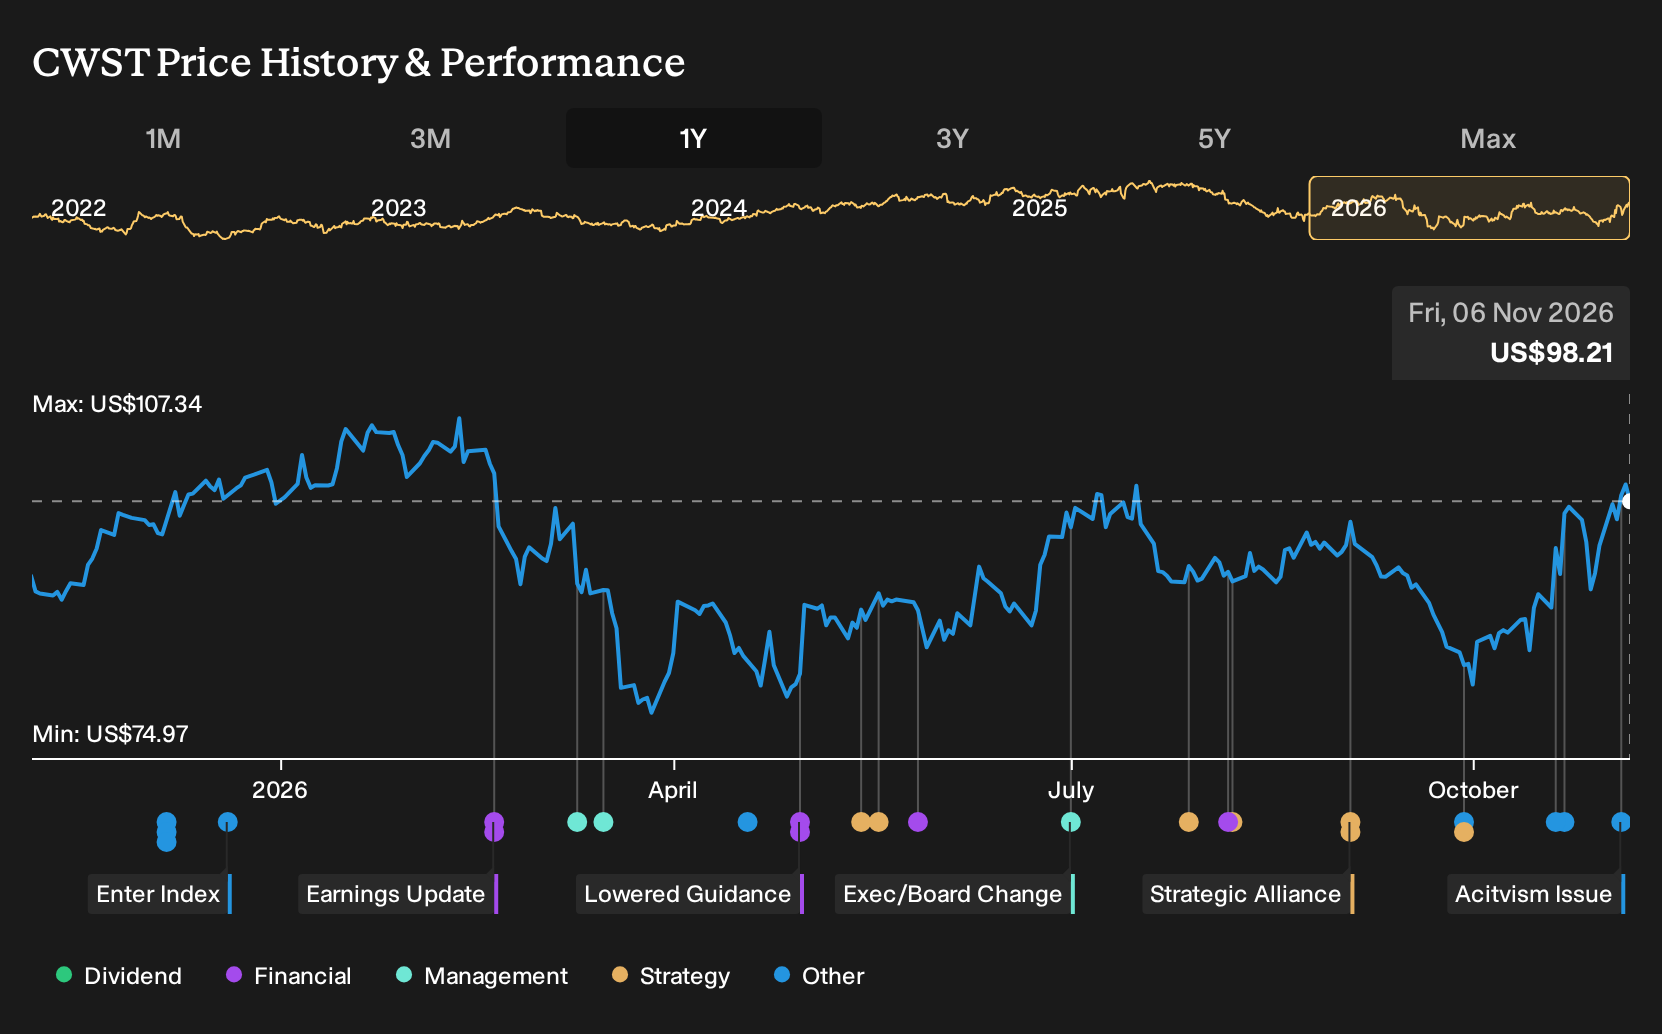
- On 4 November 2026, Jana Partners publicly pressed Casella Waste Systems to lift profitability, tighten capital allocation, and link executive pay more directly to shareholder outcomes during an ongoing debate about valuation.
- The activism focuses on how Casella Waste Systems converts its spending on acquisitions, automation, and landfill assets into tangible returns, putting operational efficiency and governance under sharper scrutiny.
- We will look at how Casella Waste Systems' investment narrative is tested as Jana pushes for tighter capital discipline and a stronger focus on profitability.
Scan how activist pressure at Casella Waste Systems compares with peers facing similar scrutiny on profitability and capital discipline by reviewing the 29 resilient stocks with low risk scores that still screen well on resilience.
Casella Waste Systems Investment Narrative Recap
To own Casella Waste Systems, you need to be comfortable with a waste services business that leans heavily on acquisitions, landfill build outs and automation to support earnings over time, while current net margins are slim at 0.3% and interest costs are not fully covered by earnings. Jana Partners’ campaign zeroes in on these pressure points, but the investment case still depends most on how efficiently Casella turns its existing capital base into cash.
In the near term, the key catalyst sits with execution on route density, landfill internalization and cost programs, especially around the Mid Atlantic integration and automation savings flagged for 2026. The biggest risk is that Q3 2026 numbers and subsequent quarters show ongoing margin compression or weak net income relative to revenue growth, which could keep questions around returns on invested capital front and center regardless of Jana’s pressure.
The upcoming third quarter 2026 earnings release on 9 November is the announcement that matters most against this activist backdrop. Casella Waste Systems is flagged as one of three business services stocks that some external research expects could beat earnings estimates this season, helped by an earnings ESP framework and its Zacks Rank, but the company is also facing forecasts of revenue growth alongside a possible earnings decline versus last year.
That mix sets up a clean test of Jana’s core critique. If revenue trends in areas like the Northeast and Mid Atlantic remain healthy while earnings or margins show strain from integration costs, landfill expansion or automation spend, investors get more evidence on whether Casella is converting capital into profitable growth. If the opposite plays out and profitability holds up better than feared, the Q3 print may ease some of the immediate concern around capital discipline and returns on ongoing investments.
Casella Waste Systems' analyst narrative points to revenues of US$2.5b and earnings of US$70.5 million by 2029, based on 8.4% yearly revenue growth and an earnings increase of about US$64.8 million from US$5.7 million today.
Uncover why Casella Waste Systems' fair value indicates an 8% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$106.5 to US$159.6, which shows how far views on Casella Waste Systems can stretch before activist pressure or fresh earnings data are even factored in. With Q3 2026 results and Jana’s campaign in play, you should expect opinions to differ and explore those alternate views directly.
Explore another Casella Waste Systems fair value estimate, including one that suggests up to 63% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Casella Waste Systems research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Casella Waste Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Casella Waste Systems' overall financial health at a glance.
Looking for more investment ideas beyond Casella Waste Systems?
Once you have a view on Casella Waste Systems, it often helps to line it up against other opportunities so you can judge risk, quality and income potential side by side using the Simply Wall St Screener.
- For investors who care most about balance sheet strength and fundamental resilience, start with this list of solid balance sheet and fundamentals (24 results) that consistently clear our filters for financial robustness.
- If you are hunting for potential mispricing, compare Casella against a 39 high quality undervalued stocks that combine quality metrics with attractive valuation signals.
- For readers looking to broaden the watchlist with fresher stories, scan a 19 high quality undiscovered gems that still show solid fundamentals but attract less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com