


EN
GRAIL (GRAL) Could Be 8% Undervalued On Galleri FDA Momentum
Event driven focus on GRAIL stock
GRAIL (GRAL) entered the spotlight after reporting third quarter 2026 results that combined modest revenue growth with a sizeable net loss, as investors weighed progress on Galleri against ongoing cash burn.
The recent 1-day share price return of 1.94% to US$121.44 only partly offsets a 7-day share price pullback of 15.33%. However, the 90-day share price return of 74.78% and 1-year total shareholder return of 52.95% suggest GRAIL’s momentum remains strong, with earnings, clinical data and the FDA advisory committee outcome now driving the story more than short-term volatility.
Spot emerging momentum stories beyond GRAIL by scanning a hand-picked set of oncology and healthcare disruptors in the 35 healthcare AI stocks.Bulls see GRAIL’s Galleri franchise and FDA momentum as justification for a rich story stock, while bears point to heavy losses and pricing pressure. Do the current numbers support that optimism, or do they lean toward caution on valuation?
Most Popular Narrative: 8% Undervalued
With GRAIL last closing at $121.44 against a widely followed fair value estimate of $131.30, the stock sits slightly below that narrative anchor, leaving the debate focused on whether Galleri execution can justify the implied expectations.
Ongoing positive clinical trial results, including substantially higher cancer detection and positive predictive value with consistent specificity for Galleri in population-scale studies, are setting the stage for robust FDA approval and broad payer reimbursement, which could unlock significant new revenue streams and accelerate top-line growth.
See why 20 investors see GRAIL as 8% undervalued.
Result: Fair Value of $131.30 (UNDERVALUED)
Still, execution risk looms large, with GRAIL posting an annual net loss of US$406.2 million and analysts highlighting ongoing cash burn and reimbursement uncertainty.
Find out about the key risks to this GRAIL narrative.
Another View: What GRAIL’s Price-To-Sales Says
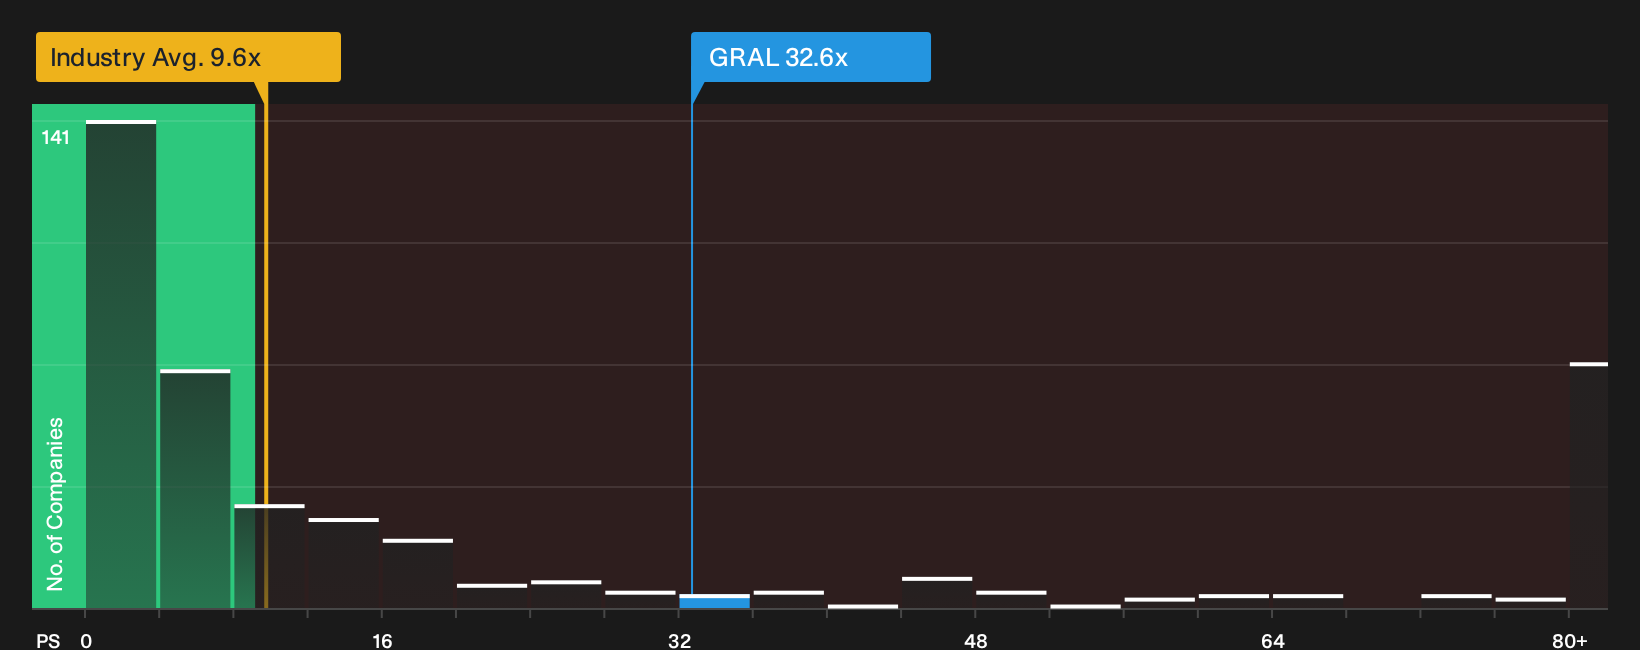
GRAIL may look appealing against a fair value estimate of $131.30, yet its current P/S ratio of 32.6x tells a very different story. The US Biotechs industry sits at 10.1x and peers at 12.3x, while GRAIL’s fair ratio is estimated at 7.7x. That kind of gap points to meaningful valuation risk if sentiment cools.
To stress test whether this kind of premium still feels reasonable for you, it helps to unpack how much of GRAIL’s future success is already priced in and how much downside there could be if the market leans back toward that 7.7x fair ratio, or closer to sector and peer norms.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
GRAIL inspires both excitement and hesitation right now, so move quickly past the headlines and weigh the data for yourself, including the 2 key rewards and 5 important warning signs.
Looking for more GRAIL-sized ideas?
If GRAIL has your attention, do not stop there. Use the screener to widen your opportunity set and pressure test your thesis against fresh ideas.
- Target steady cash payouts and income resilience by scanning companies that show up in the 8 dividend fortresses.
- Hunt for mispriced quality by running through the 19 high quality undiscovered gems before the broader market catches on.
- Prioritize sleep-at-night holdings by focusing on businesses highlighted in the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com