


EN
Hims Partnership Could Be A Big Deal For Eli Lilly (LLY)
- Eli Lilly and Hims & Hers Health announced a partnership in early November 2026 that lets eligible patients obtain Zepbound and Foundayo on the Hims & Hers telehealth platform at Lilly’s self pay prices, with prescriptions written by independent clinicians and medicines shipped directly to patients’ homes.
- The move extends Eli Lilly’s obesity portfolio into a large consumer digital channel at the same time the company has lifted 2026 revenue guidance to US$91b to US$92b. This ties demand for GLP 1 therapies more tightly to how effectively the business can scale access across self pay and telehealth routes.
- The focus now shifts to how Eli Lilly’s expanded Hims & Hers access could reshape the existing investment narrative built around GLP 1 scale.
Scan how telehealth driven obesity treatment demand is reshaping opportunities beyond Eli Lilly by reviewing a hand picked 35 healthcare AI stocks.
Eli Lilly Investment Narrative Recap
Eli Lilly is now largely a bet on incretin scale and execution. To be a shareholder, you need to believe the firm can keep translating strong demand for GLP 1 medicines into reliable access and supply, while pricing pressure and legal noise stay manageable. The raised 2026 revenue outlook to US$91b to US$92b keeps the near term catalyst focused on obesity and diabetes volumes rather than new product areas.
The Hims & Hers and LifeMD deals tighten the link between telehealth and that guidance. They make it easier to convert patient interest into prescriptions at Lilly’s self pay prices, which supports volume as long as manufacturing, reimbursement and legal risks do not crowd out margins or brand strength.
The Hims & Hers agreement is the clearest tie in to this story. It plugs Zepbound and Foundayo directly into one of the largest digital health platforms and lets eligible patients move from online consult to home delivery inside a single channel. For a business that already leans on self pay models for a large slice of Zepbound use, that matters operationally.
It also connects to the broader telehealth push that includes the LifeMD arrangement, where Lilly medicines are dispensed through a partner mail order pharmacy at Lilly’s list self pay prices. Together, those setups act as a live test of how far direct digital routes can offset U.S. net price pressure, while regulators, lawsuits and potential reimbursement shifts remain the main swing factors for the obesity franchise.
Eli Lilly's current analyst narrative points to US$125.3b in revenue and US$55.1b in earnings by 2029, based on expectations published as of late 2026. That profile assumes 13.2% yearly revenue growth and an earnings increase of about US$27.5b from US$27.6b today.
Uncover why Eli Lilly's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
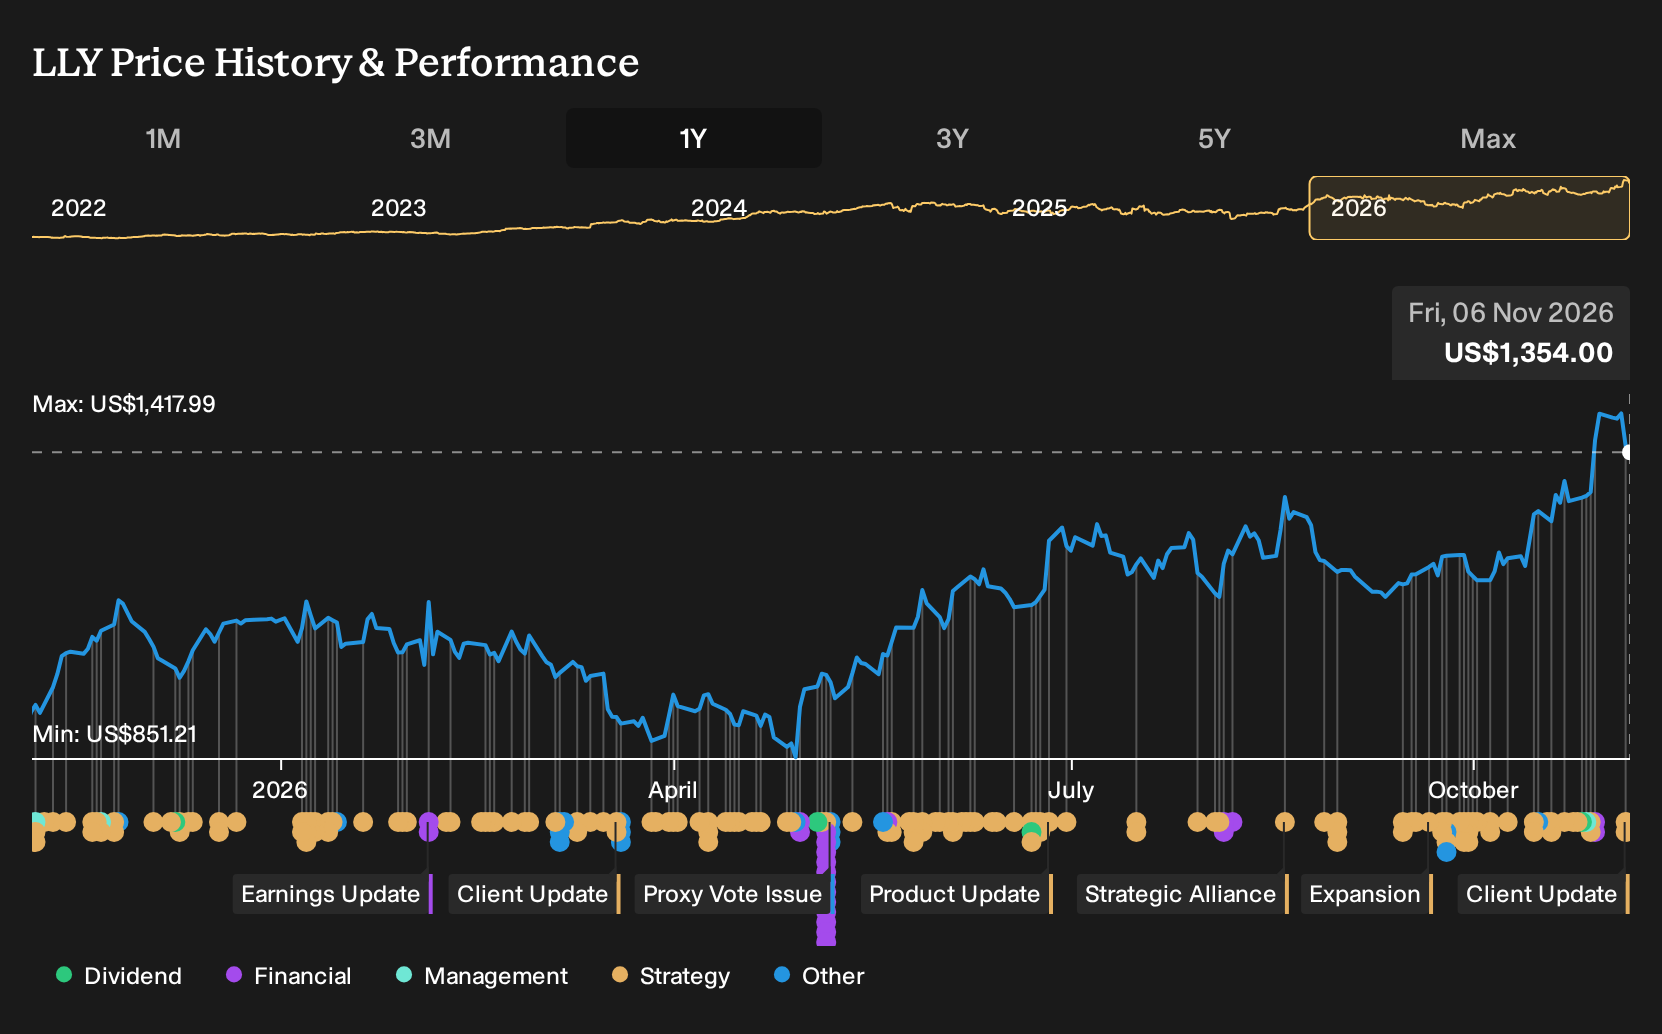
Exploring Other Perspectives
One alternate view fixates on pricing risk rather than telehealth upside. In that more cautious Eli Lilly narrative, the lowest analysts were working off 2029 earnings of about US$46.0b and revenue of roughly US$112.4b, well below the consensus path. Those estimates predate the Hims & Hers deal, so you may see opinions shift as analysts revisit their models.
Explore 13 other Eli Lilly fair value estimates, including one that suggests up to 12% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Eli Lilly research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eli Lilly. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eli Lilly's overall financial health at a glance.
Looking for more investment ideas beyond Eli Lilly?
If the Eli Lilly story has you thinking more broadly about healthcare, risk, and income, use the Simply Wall St Screener to build a shortlist that really fits your own playbook.
- For investors who care about resilience first and returns second, filter for companies with steadier profiles using a 29 resilient stocks with low risk scores that can help you lean toward calmer rides through volatility.
- If balance sheet strength matters more to you than headline growth, start with a list of solid balance sheet and fundamentals (24 results) and focus on businesses that pair financial stability with fundamental support.
- Those hunting for ideas off the beaten path can scan a 19 high quality undiscovered gems and see which lesser known stocks combine strong metrics with under followed stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com