


EN
Are Nine Month Earnings Altering The Investment Case For Pirelli Stock?
- Pirelli & C reported nine month 2026 sales of €5,278 million and net income of €389.07 million, with basic EPS from continuing operations at €0.359.
- The earnings release shows sales and profit both above the prior year period, while basic EPS from continuing operations moved in the opposite direction.
- We will now look at how Pirelli & C's higher nine month net income shapes the investment narrative that investors have been using.
Compare Pirelli & C's latest earnings with those of its peers and use our curated list of solid balance sheet and fundamentals (193 results) as a starting point to identify other companies with strong fundamentals.
Pirelli & C Investment Narrative Recap
To be a shareholder in Pirelli & C, you need to believe the tyre maker can keep pushing its mix toward high value and EV compatible products while holding onto efficiency gains. The latest nine month figures show higher sales and net income, yet slightly softer basic EPS from continuing operations serves as a reminder that execution on costs and mix still matters.
Right now the key short term swing factor is whether raw material inflation and a weaker net financial position eat into margins as earlier guidance suggested. The fresh earnings release does not radically change that risk balance. However, it gives some support to the view that operations remain on track.
The recent board meeting on 5 November 2026 is the most relevant governance touchpoint for this earnings story, since directors met to review and approve the nine month 2026 results. For shareholders, that matters because it confirms the numbers are now the reference point for discussions on capital allocation, efficiency programs and the roll out of premium and EV focused ranges.
Approved results also feed directly into how management frames raw material headwinds of about €70 million in the second half of 2026, the roughly €1.92b net financial position at mid 2026 and ongoing U.S. localisation efforts. Those issues link back to the core catalyst in Pirelli & C: maintaining mix upgrade and cost savings while funding expansion in North America and Asia without putting excessive strain on free cash flow.
Pirelli & C Analyst Scenario In Focus
Analysts sketch a fairly tight script for Pirelli & C over the next few years. Their base case points to revenue rising about 2.0% a year and profit margins edging from 7.5% today toward 7.9% by 2029. That may not sound dramatic, yet even small percentage moves matter when the tyre producer is working off billions of euros in annual sales.
The earnings bridge is clearer in the current research. Profit today is quoted at €524.2 million and the consensus points to €588.2 million by 2029, with some outliers closer to €682.7 million. That path implies an earnings increase of roughly €64 million from current levels, before you even factor in the expected 7.0% yearly rise in the share count, which would spread those profits over more shares.
On revenue, the working assumption is that by 2029 the business reaches about €7.5b of sales while generating the €588.2 million profit figure. That outcome is tied to a forecast P/E of 22.9x on those future earnings, compared with about 13.6x today and an industry reference point of 15.8x for the GB auto components sector. For you as a shareholder, that raises the question of whether Pirelli & C can justify a richer valuation multiple than both its own history and its direct peers.
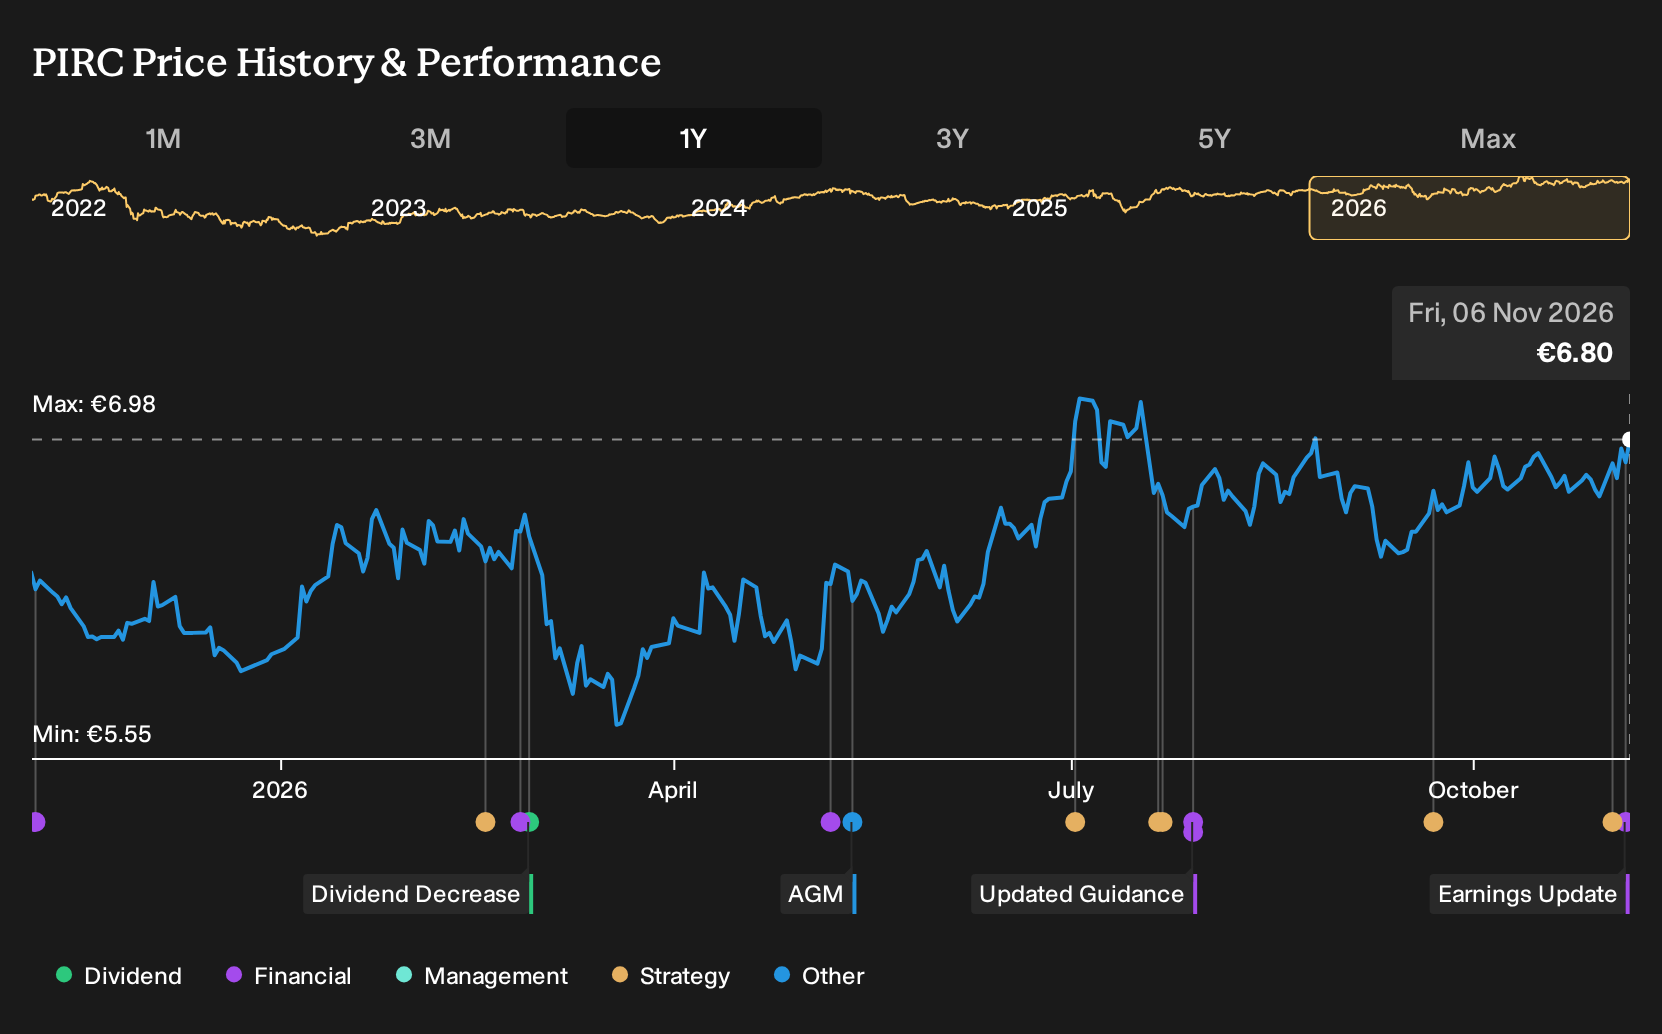
The price target math is straightforward enough. With the stock recently around €6.58 and the consensus objective at €7.21, the implied upside sits near 8.8%. Research houses frame that gap as consistent with a fairly priced security rather than something deeply misaligned with their models. If you are using these figures, the real decision is whether your own expectations on revenue growth, margin progression and capital intensity line up with the consensus, or whether you see the earnings path playing out differently.
Pirelli & C's narrative projects forecast revenue of €7.5b and earnings of €588.2 million by 2029. This rests on a 2.0% yearly revenue growth rate and an earnings increase of about €64 million from current earnings of €524.2 million.
Uncover why Pirelli & C's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster between €7.21 and €7.82, which already sits above Pirelli & C's recent share price. Those private investors have not yet factored in the latest earnings or the expected €70 million raw material headwind, so treat their views as one starting point alongside your own.
Explore another Pirelli & C fair value estimate, including one that suggests it could be worth just €7.21.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Pirelli & C research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Pirelli & C. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pirelli & C's overall financial health at a glance.
Looking For More Investment Ideas Beyond Pirelli & C?
If the Pirelli & C story has sharpened your thinking about quality, balance sheets and risk, you can use that same lens to scan the broader market. The Simply Wall St Screener provides a way to test different angles and find other businesses that fit your investment style.
- If capital preservation comes first for you, you can start with companies that pair resilience with modest risk metrics through the 212 resilient stocks with low risk scores.
- For investors looking for quality at a sensible entry point, you can filter for stronger fundamentals trading below their estimated worth using the 224 high quality undervalued stocks.
- Income focused readers can look for payout strength and higher yields supported by underlying cash generation through the 232 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com