


EN
What Trimble Stock's Updated Guidance Means For Shareholders
- Trimble reported third quarter 2026 results showing revenue of US$966.8 million and net income of US$59.1 million, alongside updated fourth quarter and full year guidance that includes expected fourth quarter revenue between US$1,031 million and US$1,061 million and a projected full year 2026 GAAP loss per share.
- Management paired this mixed earnings picture with active capital returns, completing a US$623.48 million buyback tranche since late 2025 and appointing experienced technology sector finance leader Matthew C. Brown to the board and Audit Committee in early November 2026.
- The next step is a closer look at how Trimble's heavier 2026 loss guidance compares with its longer term, subscription led investment narrative.
Trimble Investment Narrative Recap
To own Trimble, you need to believe the shift toward subscription and connected workflows will eventually matter more than near term earnings noise. The updated 2026 outlook, with US$3.91b to US$3.94b in revenue and a GAAP loss per share, keeps that tension front and center. The key near term swing factor is whether software driven annual recurring revenue can offset pressure from the Field Systems product transition and restructuring costs.
The biggest risk right now is that ongoing losses and the acknowledged weaknesses in governance and accounting controls weigh on confidence before the subscription story fully shows through in reported profit. Third quarter net income of US$59.1 million and the guided fourth quarter GAAP EPS of US$0.83 to US$0.89 indicate that earnings remain uneven. If implementation of the new internal Field Systems solution stays bumpy, reported ARR and margins could look softer than the underlying customer demand.
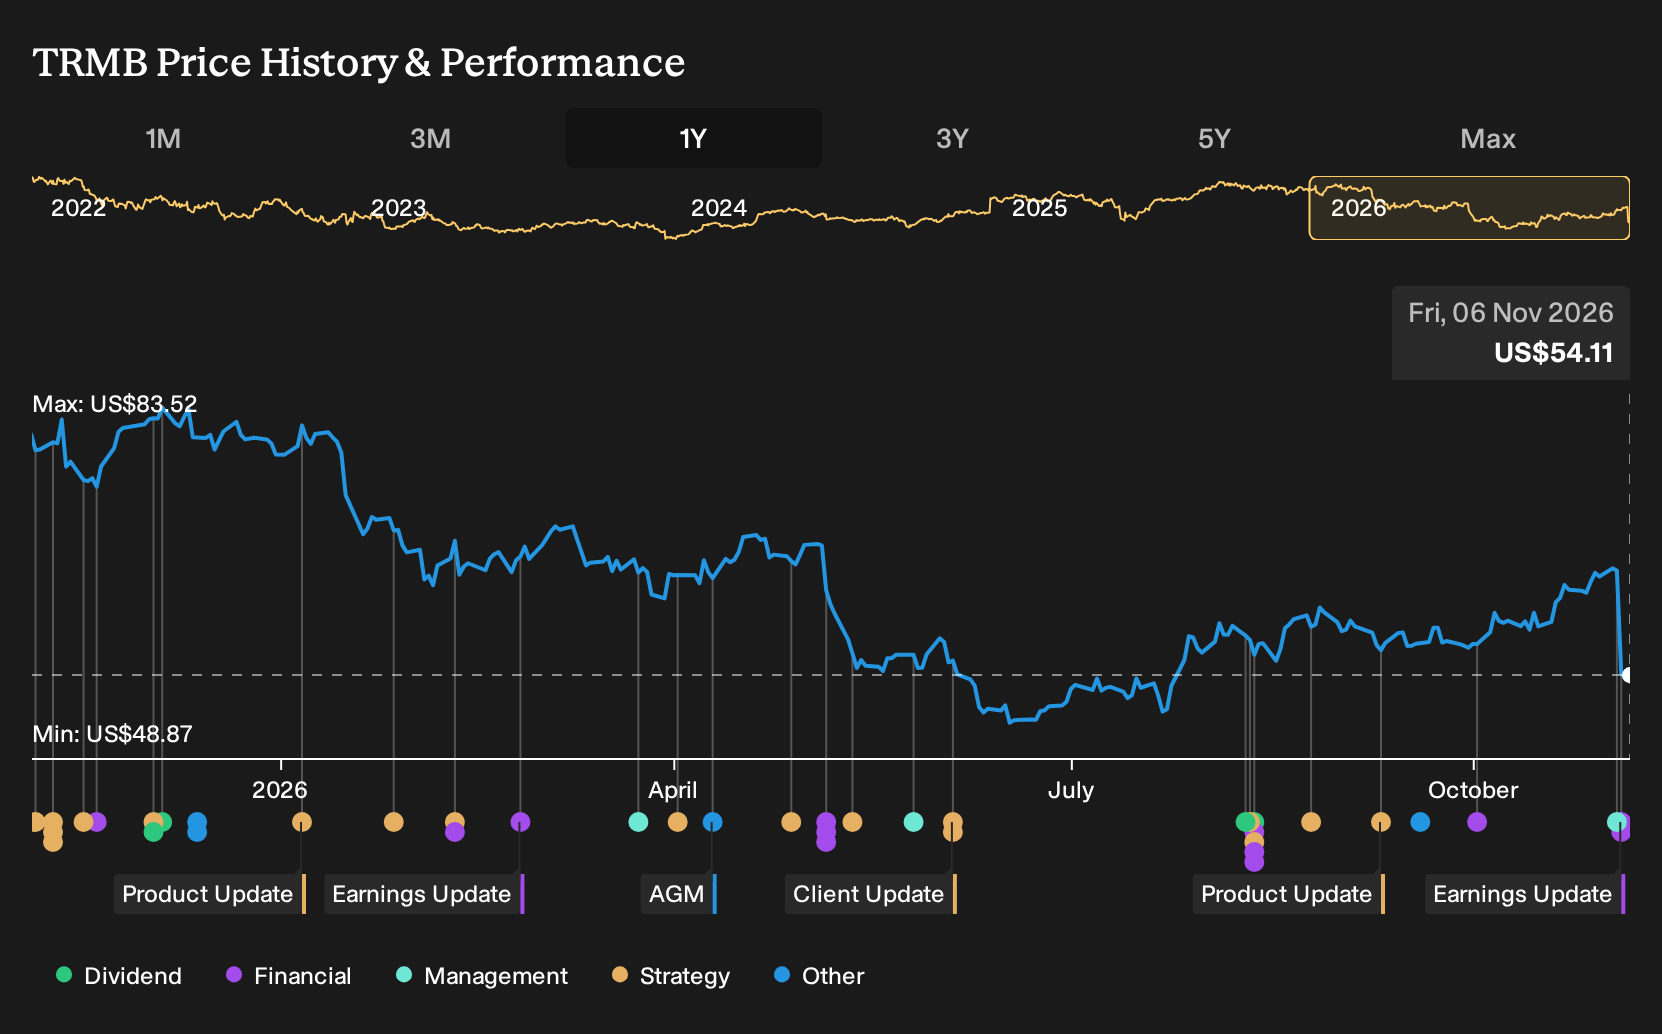
The most relevant move alongside this guidance is the completion of the US$623.48 million repurchase program that retired 9,632,446 shares, or 4.1% of the company, under the December 2025 authorization. For a stock that has fallen about 31% year to date, that is a clear signal that management is comfortable returning capital even as Trimble reports a full year loss.
That capital return sits next to a business still investing in AI enabled tools, subscription bundles and connected workflows as the main long term engine. For investors, the buyback and the appointment of Matthew C. Brown to the board and Audit Committee both relate to execution risk and potential upside. If operational delivery on ARR, margin discipline and control remediation progresses from here, those corporate moves could matter more than any single quarter of noisy earnings.
What The Long Range Trimble Forecast Assumes
Analysts sketch a very different Trimble by the late 2020s, with the consensus view pointing to US$4.8b in revenue and US$1.6b in earnings by 2029. That profile rests on projected revenue growth of 7.9% a year and an earnings swing of about US$1.7b from the current loss of US$104.7 million to the 2029 forecast profit, which would require a sharp lift in profitability on a subscription heavy model.
Uncover why Trimble's fair value indicates a 48% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Trimble, the sharpest alternate view is that the recent guidance highlights earnings risk rather than opportunity. The most bearish analysts were already assuming about US$4.8b in 2029 revenue and US$1.3b in earnings. That is still a big swing from today, yet it supports only a US$61.0 target, which shows how far opinions can stretch. These estimates came before this guidance and buyback update, so forecasts and narratives may evolve as new information becomes available.
Explore 2 other Trimble fair value estimates, including one that suggests it could be worth just $80.18!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Trimble research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Trimble. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trimble's overall financial health at a glance.
Looking for more Trimble style investment ideas?
If Trimble's subscription driven story has caught your attention, it can help to widen the lens and scan for other businesses with similar financial traits or different risk profiles that still fit your approach.
- For readers hunting for resilient balance sheets and steady fundamentals, start with this curated list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- If capital preservation matters most to you, scan a focused universe of 29 resilient stocks with low risk scores that score well on stability and downside protection.
- Those looking for under followed opportunities with quality metrics can review our hand picked 19 high quality undiscovered gems that combine solid fundamentals with quieter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com