


EN
Why Lowe's Companies (LOW) Is Back In The Spotlight
Lowe's Companies (LOW) cut its full year 2026 sales and earnings forecast, citing softer consumer demand and weaker home building, yet investors appear focused on its growing Pro, online, and home services operations.
That guidance cut comes after a sharp swing in sentiment. Lowe's Companies has seen its share price climb 7.4% over the past week and post a strong 23.7% 30 day share price return, even though the year to date share price return is still down 9.1%. Over a longer horizon, total shareholder return paints a steadier picture, with a 22.6% gain over three years and 5% over five years. This suggests momentum has recently picked up again as investors reassess the balance between lowered forecasts and the perceived value of the Pro, online, and services push.
Spot emerging home improvement peers moving on similar guidance resets and Pro demand trends by scanning our curated list of 39 high quality undervalued stocks.Lowe's Companies now trades well below some fair value estimates yet only slightly under others after the guidance cut and sharp rebound. Is that gap a genuine margin of safety or a mirage from shifting sentiment?
Most Popular Narrative: 11.9% Undervalued
On the most followed view, Lowe's Companies carries an estimated fair value of $255 against a last close of $224.55. That gap sits at the center of a story that leans heavily on Pro-focused expansion and acquisitions.
Lowe’s is accelerating its shift toward professional contractors while strengthening its Total Home strategy for DIY and “Do It For Me” customers. Through major acquisitions (Foundation Building Materials / FBM and Artisan Design Group / ADG) plus digital investments, the company aims to deepen relationships with Pros, especially small- and medium-sized ones, and expand into specialty building materials, flooring, and installation services. This expands its reach in a large, fragmented Pro market and positions Lowe’s to gain share when housing activity recovers.
See why 8 investors see Lowe's Companies as 12% undervalued.
According to Andrei_Niculescu, that Pro and services push helps support a narrative fair value that sits about 11.9% above the market price. The narrative uses a discount rate of 9.05% and assumes a profit margin of 7.33%, which frames Lowe's Companies as undervalued relative to its projected cash generation under those inputs.
That story lines up with Simply Wall St's DCF output in a broad sense, which currently indicates Lowe's Companies trading at roughly 2.7% below an estimated future cash flow value of $230.85. While that DCF result suggests only a modest gap, it still places the recent $224.55 share price on the cheaper side of that modeled range.
Result: Fair Value of $255 (UNDERVALUED)
Still, Lowe's Companies faces clear pressure points, including weaker DIY spending and potential acquisition integration problems that could quickly undercut this Pro led valuation story.
Find out about the key risks to this Lowe's Companies narrative.
Another View: What Lowe's Companies' P/E Says
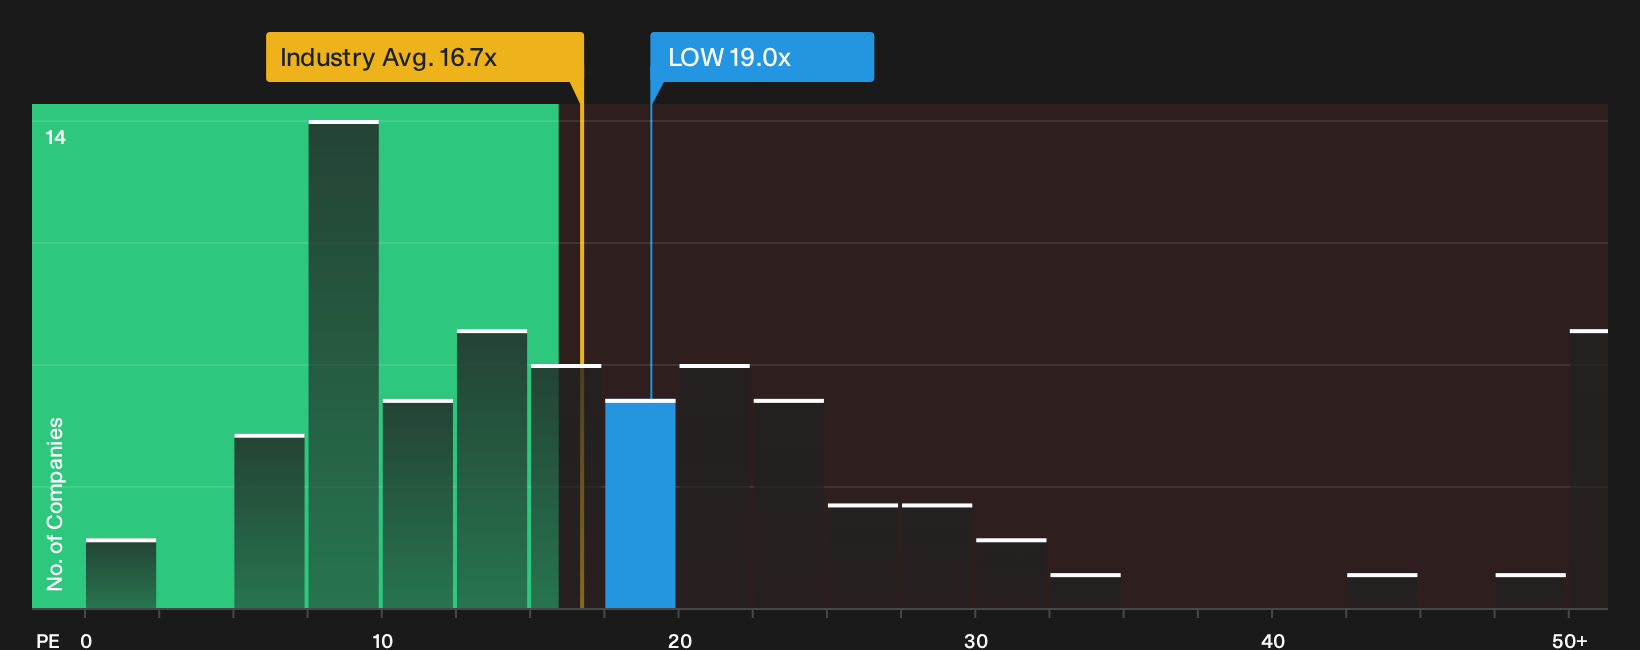
Our DCF work points to Lowe's Companies trading about 2.7% below an estimated future cash flow value of $230.85, which leans slightly toward undervalued. The market is pricing the shares at a P/E of 19x, while the estimated fair ratio is 21.9x.
Relative to the US Specialty Retail industry on 16.7x and peers closer to 24.7x, Lowe's Companies sits in the middle. This positioning keeps both upside and downside in play if sentiment or earnings forecasts shift. The key consideration for investors is which reference point will be most influential when the next significant move occurs.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Lowe's Companies so far. Act while the data is fresh, review both the upside and the pressure points, then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lowe's Companies?
If Lowe's Companies has you thinking more broadly about where to put fresh capital, do not stop here. Cast a wider net and test your thesis across other opportunities.
- Target income resilience by reviewing companies that screen as potential 8 dividend fortresses while you assess how they might complement your existing holdings.
- Hunt for quality at a discount and scan the 19 high quality undiscovered gems that may not yet be widely followed but still show solid underlying metrics.
- Tighten your risk profile by scanning a curated 29 resilient stocks with low risk scores that could help balance more volatile positions in your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com