


EN
Is Redwire (RDW) Undervalued After Its Mixed Quarter And New DARPA Win?
Redwire (RDW) is back in focus after a mixed third quarter, where record gross margins and a swelling backlog met a revenue shortfall, persistent losses, and fresh contract wins with U.S. defense customers.
Redwire’s share price has been volatile, with a 1-day share price return of 16.5% after the Q3 2026 update, but a 30-day share price return down 29.6% and a 90-day share price return down 47% as investors weigh revenue misses against new DARPA work and reaffirmed guidance. That short term weakness contrasts with a very large 3-year total shareholder return close to 20x, even though the 5-year total shareholder return is still down 35.9% from earlier levels. This suggests long term holders have seen big swings around the current US$7.21 price.
Compare Redwire’s volatile performance and defense-driven backlog with a curated set of peers by scanning 89 robotics and automation stocks in adjacent automation and space hardware plays.
Redwire now appears to be a stronger operator than it was a year ago, yet the share price has just swung sharply lower. Is that gap between business progress and market mood creating value, or is it signaling a value trap?
Most Popular Narrative: 44% Undervalued
On Simply Wall St, the most followed narrative pegs Redwire’s fair value at $12.82 compared with the recent $7.21 share price, which frames the current drop as a valuation gap rather than a simple momentum break.
The combination with Edge Autonomy and the shift to a scalable space and defense platform is already reflected in year-over-year revenue of US$103.4 million in Q3 2025 and adjusted gross margin of 27.1%. This could support further operating leverage and earnings as cost savings and lean programs flow through SG&A.
See why 43 investors see Redwire as 44% undervalued.
Result: Fair Value of $12.82 (UNDERVALUED)
Still, Redwire’s reliance on U.S. defense contracts and ongoing adjusted EBITDA losses, along with potential equity dilution from its at-the-market program, could quickly flip this undervalued thesis.
Find out about the key risks to this Redwire narrative.
Another View: Redwire Looks Expensive On Sales
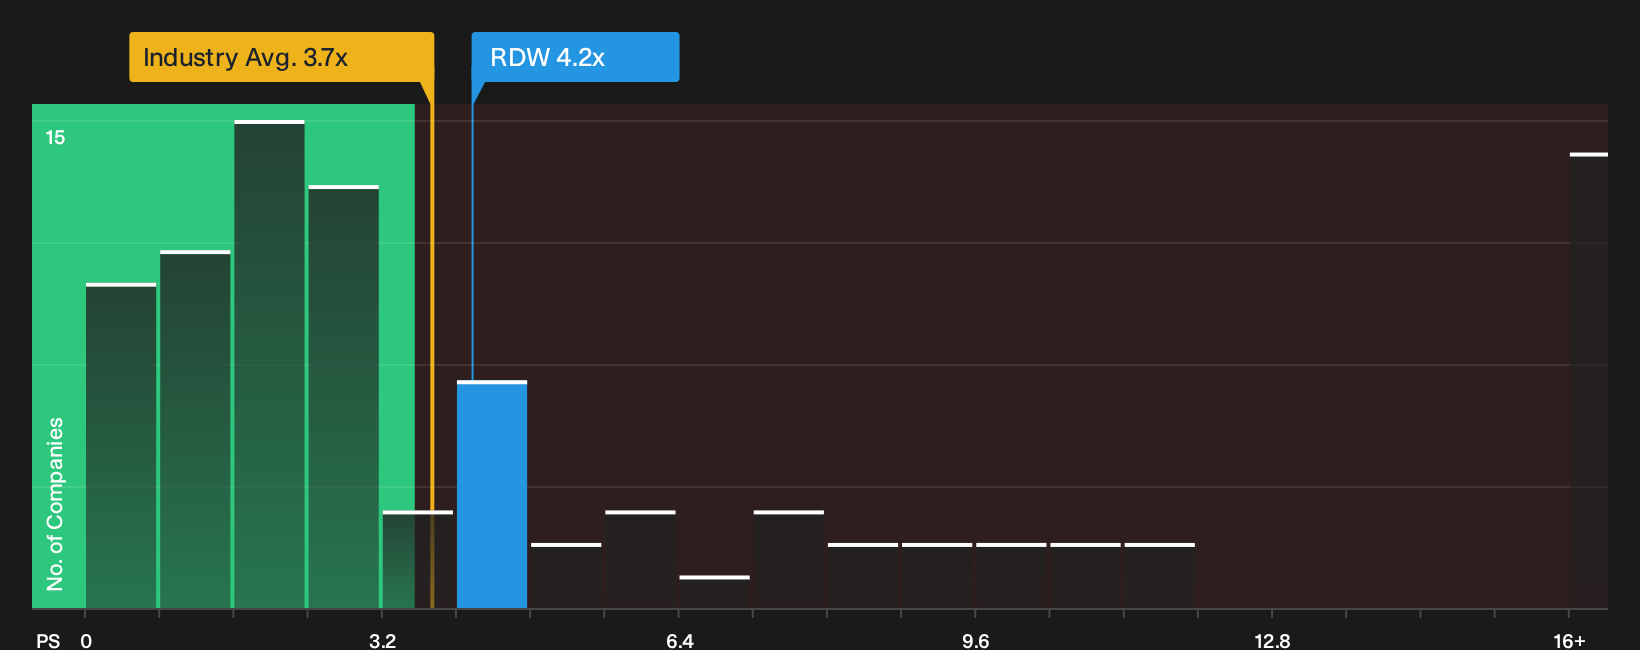
The SWS DCF model points to a fair value well above Redwire’s $7.21 share price, but the simple P/S check tells a different story. RDW trades at 4.2x sales, which is richer than both the Aerospace and Defense industry at 3.7x and its peer set at 3.3x.
The fair ratio for Redwire is 2.2x sales, a level the market could move toward if enthusiasm fades or revenue delivery disappoints. That would imply less room for error than the DCF suggests. Which signal you trust more depends on your own risk tolerance.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Redwire’s value story can tempt you to lean on headlines, but the better move is to act quickly and test the numbers yourself. Weigh both the risks and the upside before deciding where you land, starting with the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond Redwire?
If Redwire has you rethinking your watchlist, do not stop here. Broader opportunity often sits just outside the headline story you started with.
- Spot potential mispricing early and sift through companies that combine quality with attractive valuations using the 39 high quality undervalued stocks.
- Prioritize resilience and protect the downside by focusing on businesses highlighted in the 29 resilient stocks with low risk scores.
- Hunt for underfollowed opportunities that still have solid fundamentals through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com