


EN
Cardinal Health (CAH) Lifts Guidance As Investors Ask If The Story Is Fully Valued
Cardinal Health (CAH) just delivered a stronger than expected first quarter, with revenue and earnings ahead of forecasts, and full year fiscal 2027 profit guidance raised after solid specialty and pharmaceutical performance.
The stronger quarter and higher fiscal 2027 profit outlook have fed straight into momentum in Cardinal Health’s shares, with a 17.04% 1 month share price return, a 32.08% year to date share price gain and a very large 5 year total shareholder return of 484.73%. Investors appear to be treating this trend as still intact rather than fading.
Scan for other healthcare distributors that show similar earnings momentum and contract visibility using our curated list of 29 resilient stocks with low risk scores.
Cardinal Health has just sprinted to record territory and now trades within touching distance of analyst targets. The next thing to weigh is how much of the valuation case still sits in front of you rather than behind.
Most Popular Narrative: 0% Overvalued
Cardinal Health last closed at $271.72, almost exactly in line with the most followed fair value estimate of $270.94 that is based on a 7.24% discount rate and long term earnings forecasts. The key question for readers is whether the shift toward higher margin services and a repaired medical products arm can support that valuation over time.
The expansion of specialty pharma distribution, multi specialty MSO platforms in areas like oncology, urology and gastroenterology, and a rapidly scaling Biopharma Solutions business that is ahead of its prior growth plan points to a larger mix of higher value services that can influence segment profit and overall earnings.
See why 62 investors see Cardinal Health as 0% overvalued.
Result: Fair Value of $270.94 (ABOUT RIGHT)
Still, product quality issues such as the levothyroxine recalls, along with any renewed pressure on Global Medical Products and Distribution costs, could quickly challenge the Cardinal Health narrative.
Find out about the key risks to this Cardinal Health narrative.
Another View: Cardinal Health Through A Multiple Lens
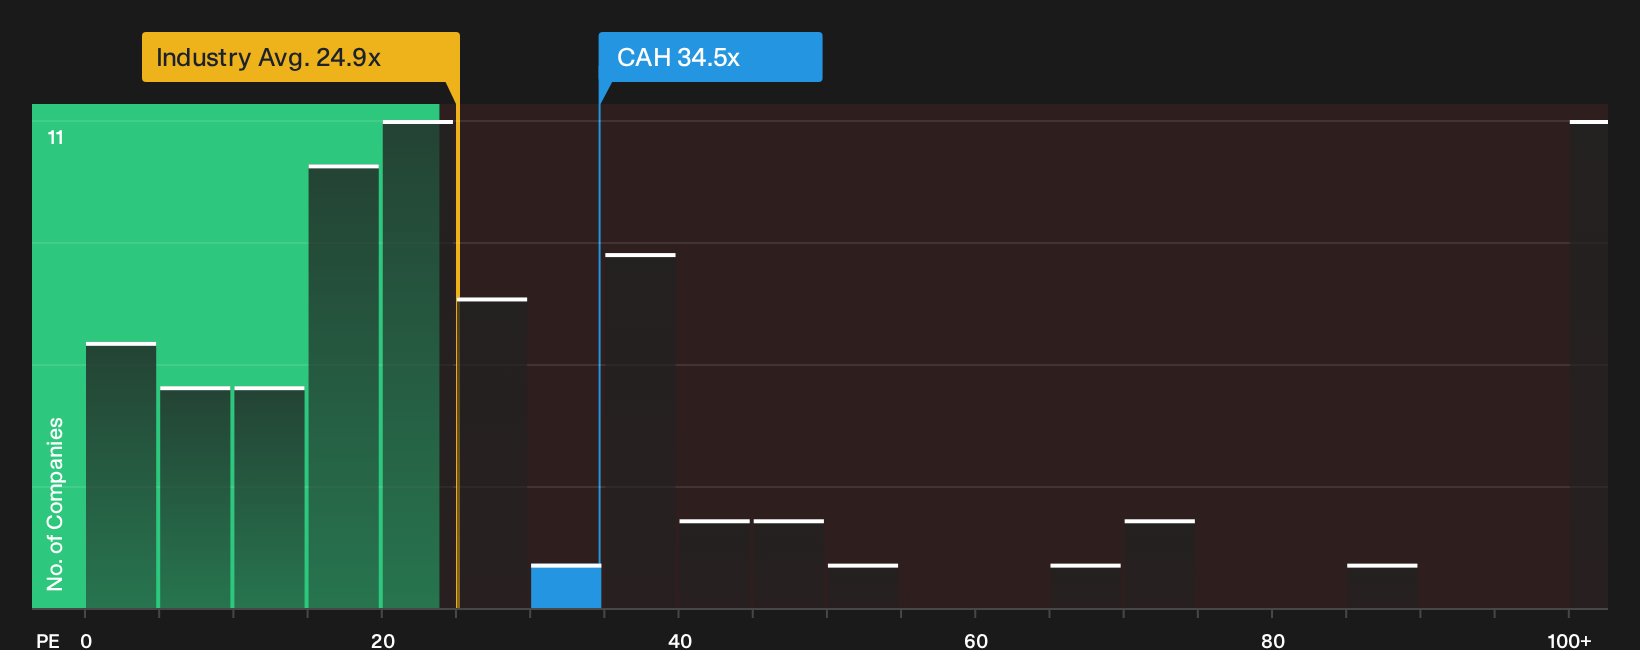
On a simple earnings multiple, Cardinal Health looks far less relaxed than the fair value narrative implies. The shares trade on a P/E of 34.5x, compared with 24.9x for the broader US Healthcare group, 27.2x for direct peers and a fair ratio of 32.6x that the market could drift toward over time.
That premium suggests investors already pay up for the current story, which leaves less room if sentiment cools or forecasts reset. The question for you is whether that extra valuation risk feels justified by the mix shift and cash flow profile you expect from here.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cardinal Health for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Cardinal Health is mixed, and that is exactly when a closer look can matter most for your portfolio decisions. Act quickly, review both the upside drivers and the pressure points, and ground your own stance in the data behind those 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Cardinal Health?
If you stop at Cardinal Health, you risk missing other opportunities that could balance your portfolio and sharpen your overall return potential.
- Target steady cash generators by scanning companies that pass our 8 dividend fortresses and may offer income alongside capital growth potential.
- Hunt for quality at a discount by focusing on businesses in the 39 high quality undervalued stocks that pair stronger fundamentals with more modest expectations.
- Strengthen your downside protection by building a watchlist from the list of solid balance sheet and fundamentals (24 results) so sudden shocks do not dominate your holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com