


EN
Learn Why The Bull Case For Pacira BioSciences Shares Could Change Following Earnings Results
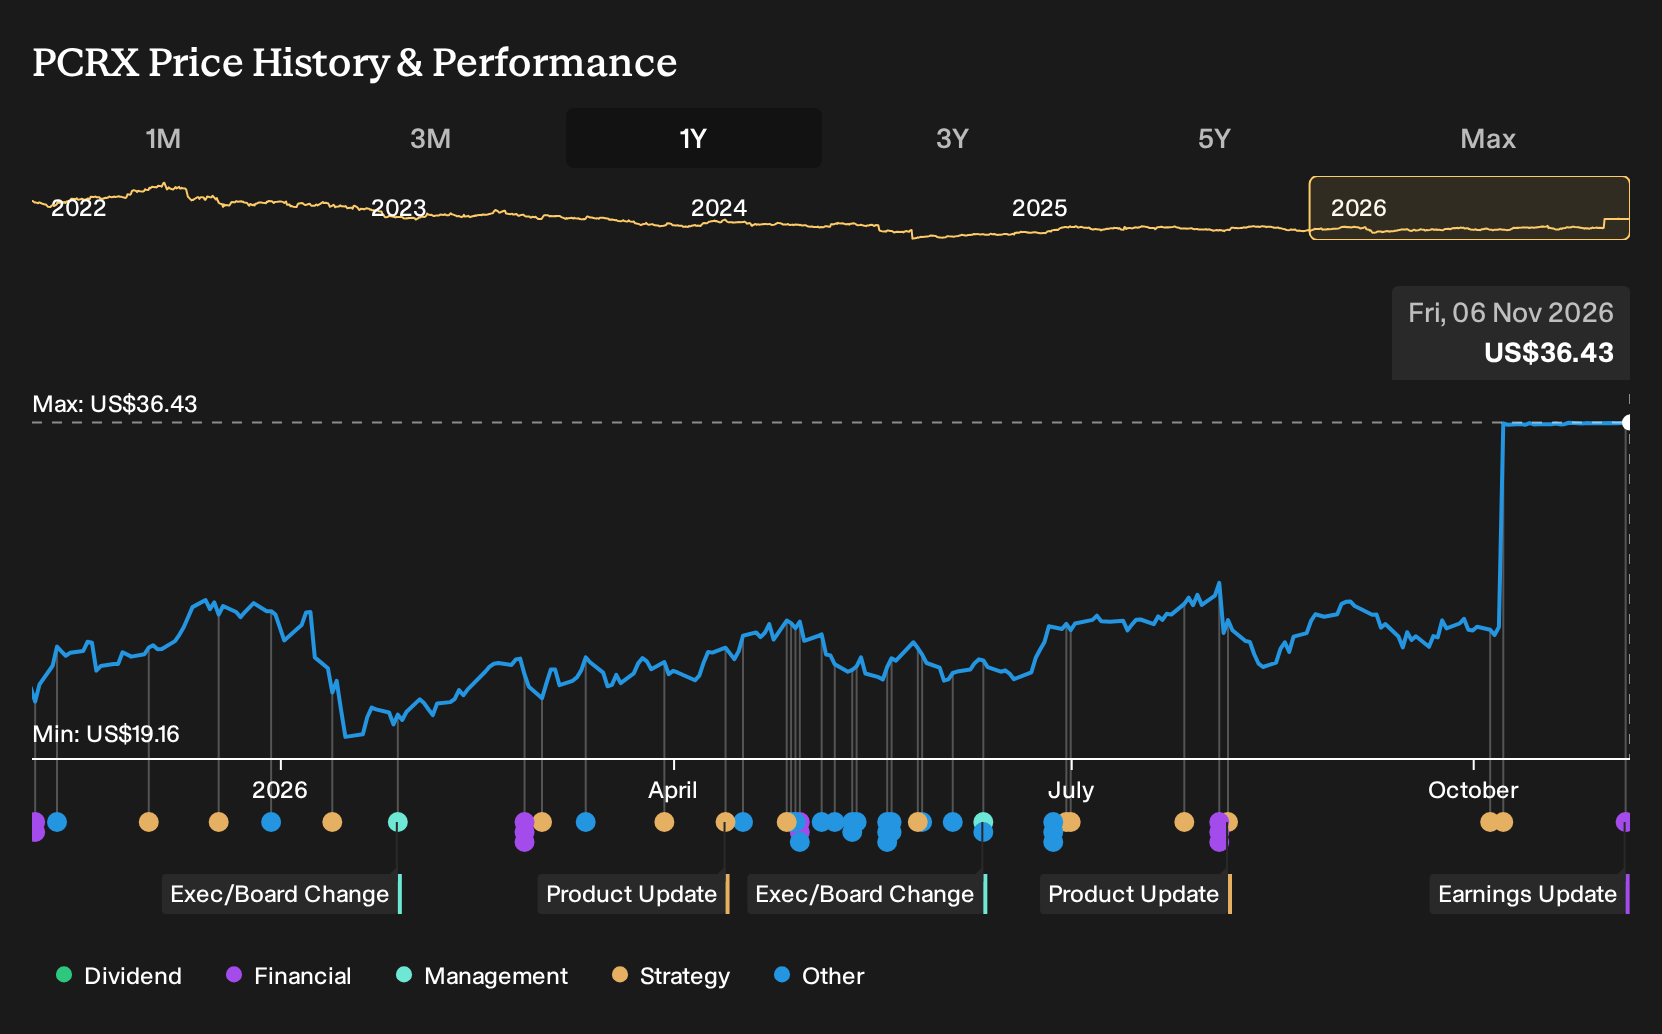
- Pacira BioSciences reported third quarter 2026 revenue of US$176.65 million and net income of US$28.52 million, with diluted EPS from continuing operations of US$0.70, alongside nine month revenue of US$546.43 million and net income of US$36.09 million.
- The sharp step up in earnings relative to roughly flat revenue points to meaningful shifts in cost control, product mix or pricing that change how efficiently Pacira BioSciences converts sales into profit.
- Now the focus turns to how Pacira BioSciences' investment narrative adapts to this stronger profitability profile, especially the jump in net income.
Pressure test Pacira BioSciences' earnings jump by comparing it with a hand picked group of financially resilient businesses using the 29 resilient stocks with low risk scores.
Pacira BioSciences Investment Narrative Recap
For Pacira BioSciences, the core belief is that EXPAREL and ZILRETTA can keep gaining traction in outpatient and ambulatory settings, while the early gene therapy work on PCRX-201 eventually broadens the pain and musculoskeletal franchise. The latest results show net income and earnings per share scaling faster than revenue, which points to a business that is currently converting sales into profit more efficiently.
The near term swing factor is whether this profitability step up is sustainable as reimbursement, procedure volumes and product mix move around quarter to quarter. The biggest risk remains heavy reliance on EXPAREL and reimbursement support, with the NOPAIN Act expiry in 2027 and any slower than expected adoption at new providers both capable of cooling that earnings momentum.
The stand out announcement tied to this discussion is the third quarter 2026 report itself. Pacira BioSciences posted US$176.65 million of quarterly revenue against US$179.52 million a year earlier, yet net income moved to US$28.52 million from US$5.43 million, with diluted EPS from continuing operations at US$0.70 versus US$0.12.
Over the first nine months of 2026, the business generated US$546.43 million in revenue and US$36.09 million in net income, compared with US$529.54 million and US$5.40 million in the prior period. For you as an investor, the question is whether this improved earnings profile is a sign that Pacira BioSciences can support future R&D on assets like PCRX-201 and PCRX-2002 while still managing the reimbursement and product concentration risks already on the radar.
Pacira BioSciences' current earnings are US$14.6 million, with analysts assuming revenue growth of 5.5% per year and consensus earnings of US$70.8 million by 2029. This implies roughly a 5x increase in earnings from today and forecast revenue of US$875.0 million in that same year.
Uncover why Pacira BioSciences' fair value indicates an 8% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Pacira BioSciences looks very different if you focus on the bearish angle that rising R&D could squeeze profits. The lowest analysts were penciling in 3.1% annual revenue growth and earnings of about US$63.8 million by 2029 before this earnings surprise. That more cautious story may shift, so explore several viewpoints before deciding what makes sense to you.
Explore 2 other Pacira BioSciences fair value estimates, including one that suggests as much as 8% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Pacira BioSciences research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pacira BioSciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pacira BioSciences' overall financial health at a glance.
Looking For More Investment Ideas Beyond Pacira BioSciences?
Once you have a view on Pacira BioSciences, it often helps to widen the lens and compare it with other businesses that fit different risk, income, or valuation profiles using the Simply Wall St Screener.
- If you want a starting point for potential mispricing opportunities, check out a curated set of 39 high quality undervalued stocks that pair solid fundamentals with compressed expectations.
- For readers who care about balance sheet strength first and share price second, scan the list of solid balance sheet and fundamentals (24 results) to focus on companies with sturdier financial foundations.
- If you prefer to hunt where fewer investors are looking, use the 19 high quality undiscovered gems and focus on under-followed businesses with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com