


EN
Klaviyo (KVYO) Stock May Be Undervalued On Raised Revenue Guidance
Klaviyo has seen its share price move around over the past year, yet the core question for anyone looking at the stock today is how well that market value lines up with the revenue the business is actually generating. With investors reacting to fresh results and corporate actions, the issue is whether the current valuation is grounded in its sales profile or drifting away from it.
- The stock has fallen 32.1% over the past year, which puts a spotlight on whether the current market value still makes sense when set against Klaviyo's sales base.
- Recent results showed revenue of US$387.2 million and an uplift in net revenue retention to 108%, figures that can shape how much investors are prepared to pay for each dollar of future sales.
- Your read on Klaviyo is one view; the desks covering it have another. See what analysts think Klaviyo's shares could be worth.
The issue now is whether Klaviyo's current share price is adequately supported by its sales, given this mix of share performance and recent business updates.
If you want to test whether Klaviyo's sales based valuation question also shows up in similar stories, compare it against companies in the 39 high quality undervalued stocks
Is Klaviyo Still Cheap on Sales?
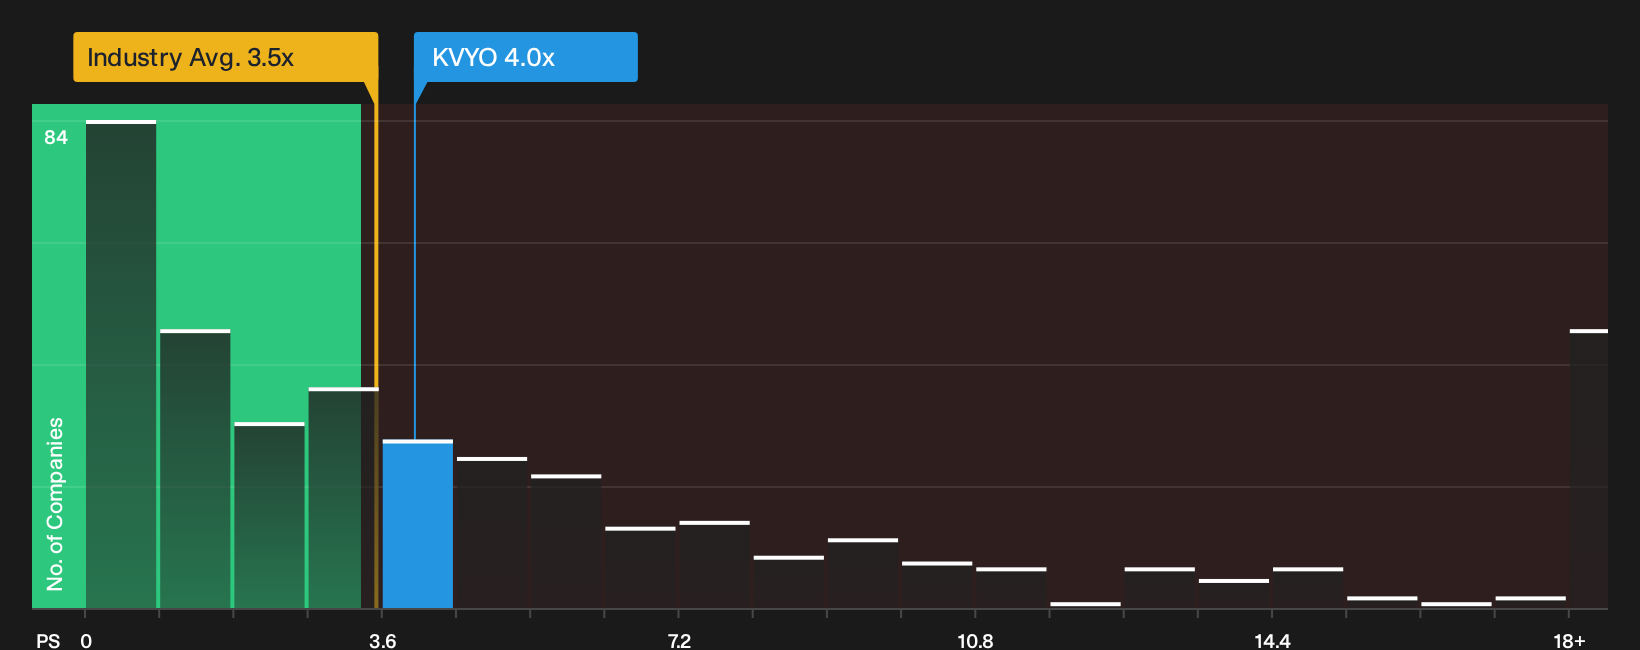
P/S can be a useful yardstick for Klaviyo because top line trends are often easier to compare across software platforms than earnings that can swing with investment spending. On that measure, Klaviyo trades on a P/S of 4.0x, which is above the broader software sector average of 3.5x yet below a peer basket closer to 11.5x.
The fair P/S multiple implied by Simply Wall St's model, which adjusts for Klaviyo's growth profile, profitability and risk, sits above the current 4.0x level, so the shares screen as undervalued on this framework. Because the business recently raised its 2026 revenue guidance and announced a US$300 million buyback, the current discount to that tailored P/S yardstick suggests the market is pricing Klaviyo more cautiously than the model's assumptions. Explore the numbers behind Klaviyo's P/S valuation.
The Klaviyo Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Klaviyo pick up where that price to sales puzzle leaves off. They spell out which combinations of future growth, profitability and earnings power would need to play out for Klaviyo's valuation to move meaningfully higher or lower than today's quote. Each narrative links its number to a clear view on how revenue momentum, margin levels and business risks might evolve, giving you something concrete to revisit as fresh results come through.
Community views on Klaviyo are split between those who see underappreciated AI and international upside and those who worry that margins and monetization blunt the payoff.
Bull case: 21% undervalued
"Rapid early uptake of AI agents such as Composer, which reached more than 95,000 users in its first month with meaningful weekly activity, and Customer Agent, where usage grew 40% quarter on quarter and helped brands generate incremental revenue, positions Klaviyo to monetize automated marketing and service workflows…"
Discover why this Narrative puts Klaviyo at 21% undervalued.
Bear case: 9% overvalued
"Although Klaviyo reports rapid adoption of Composer and Customer Agent, the recent downgrade that questions visibility on how these AI agents will be priced and packaged raises the risk that high usage does not translate into meaningful incremental revenue or earnings contribution…"
Explore why this Narrative puts Klaviyo at 9% overvalued.
One more piece of the Klaviyo puzzle is still off the page
The last angle that can sharpen how you view Klaviyo today is where professional forecasts place its revenue and earnings power a few years from now, and how that compares with the current sticker price. Explore where analysts expect Klaviyo to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com