


EN
BrightSpring Health Services (BTSG) Could Be 5% Undervalued Following Raised 2026 Outlook
BrightSpring Health Services (BTSG) is back in focus after third quarter results showed higher revenue and earnings, management raised 2026 guidance, and major funds increased exposure to the stock in recent sessions.
The strong third quarter and raised 2026 outlook have come alongside a sharp re-rating in BrightSpring Health Services, with the share price at $67.15 after a 74.87% year-to-date share price return and a 1-year total shareholder return of 102.63%. This is signalling momentum that investors are treating as confirmation of a stronger growth and risk profile rather than a short-lived bounce.
Scan how BrightSpring Health Services compares with other fast-moving healthcare names by reviewing the hand picked 35 healthcare AI stocks that are riding similar momentum and policy sensitive themes.
The share price now tracks well ahead of some estimates while still showing a sizeable gap to others. Where does fair value for BrightSpring Health Services really sit after this run, and what do the current models imply?
Most Popular Narrative: 4.9% Undervalued
At a last close of $67.15, the most followed narrative on BrightSpring Health Services points to a fair value of $70.59, which frames the recent rally as still leaving modest upside according to that framework.
The real business is not home health. It is pharmacy.
Roughly 80% of revenue comes from specialty and institutional pharmacy services.
This is where the structural moat exists.
Patients are not “customers” in the retail sense, they are clinically managed cases. Once a patient enters an infusion or specialty pharmacy program, switching providers is rare because:
This creates low churn, recurring revenue, and embedded payer relationships.
In short: BrightSpring is closer to a healthcare infrastructure platform than a traditional pharmacy company.
See why 7 investors see BrightSpring Health Services as 5% undervalued.
Result: Fair Value of $70.59 (UNDERVALUED)
Still, the BrightSpring Health Services story could be knocked off course by tighter reimbursement for Medicare or Medicaid services, as well as slower pharmacy segment execution.
Find out about the key risks to this BrightSpring Health Services narrative.
Another View: BrightSpring Health Services Looks Expensive On P/E
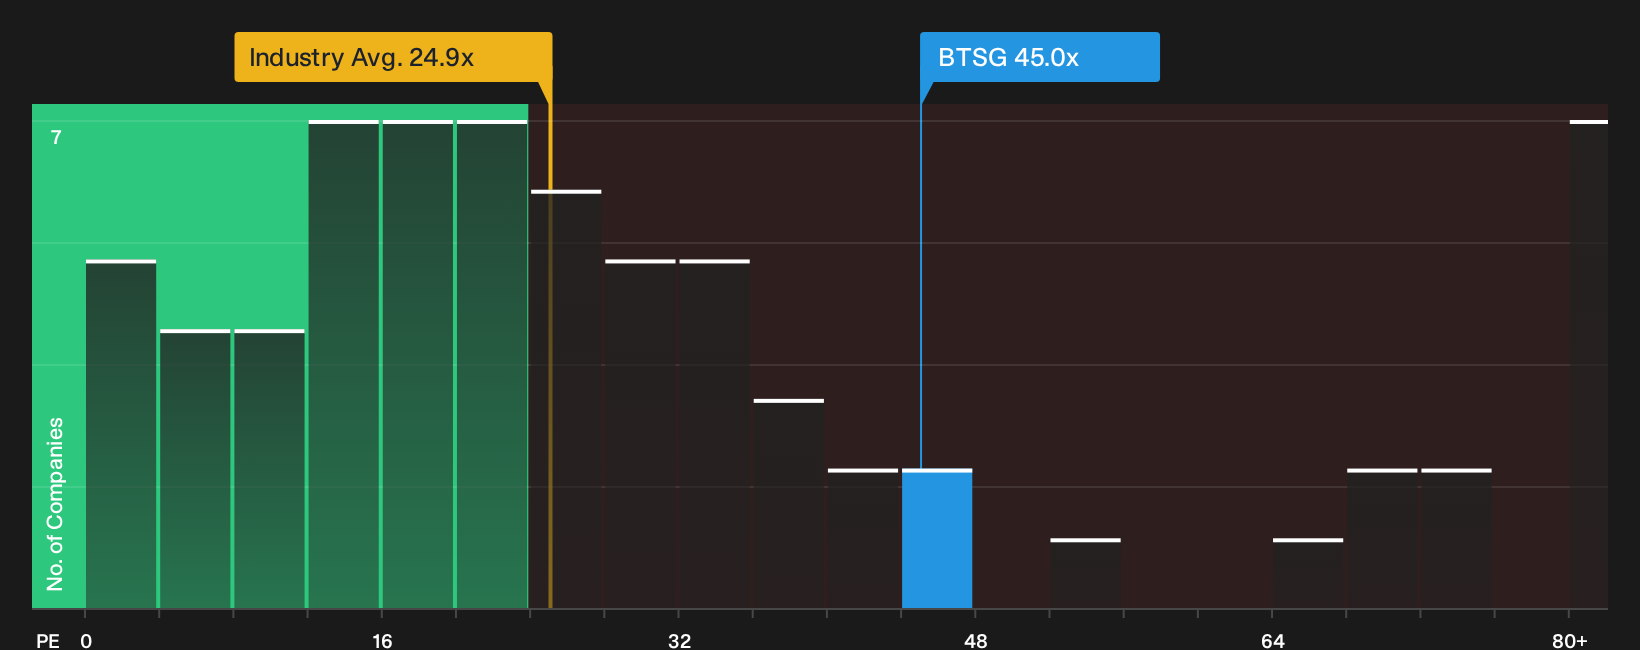
On the flip side of the undervalued narrative, BrightSpring Health Services trades on a P/E of 45x, compared with 21.9x for peers, 24.9x for the wider US Healthcare group, and a fair ratio of 36.5x. That premium suggests less room for error if the story stumbles from here.
See what the numbers say about this price in more depth with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages so far on BrightSpring Health Services. Price is hot, but both risk and reward signals are flashing. Make up your own mind by checking the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond BrightSpring Health Services?
If BrightSpring Health Services has your attention, do not stop here. Broadening your watchlist with a few targeted themes can sharpen your next move.
- Target dependable cash flows by reviewing companies built around strong payouts in the 8 dividend fortresses.
- Hunt for quality at a discount by scanning the 39 high quality undervalued stocks that pair fundamentals with attractive pricing.
- Prioritise resilience by focusing on businesses in the 29 resilient stocks with low risk scores that keep risk scores in check while still offering upside potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com