


EN
Is Jerónimo Martins SGPS (ENXTLS:JMT) Undervalued After Mixed Third Quarter Earnings?
Why Jerónimo Martins SGPS Earnings Matter For ENXTLS:JMT Investors
Jerónimo Martins SGPS (ENXTLS:JMT) has put fresh numbers on the table, with third quarter and nine month 2026 results showing higher sales alongside lower net income and earnings per share.
This blend of stronger revenue and weaker profitability gives investors new information on how the food retail group is balancing volume, pricing, and costs across markets such as Portugal, Poland, and Colombia.
Recent trading around Jerónimo Martins SGPS reflects that tension between stronger sales and softer earnings. The share price has climbed, with a 14.65% 30 day return and a 10.52% 90 day share price return; yet the 1 year total shareholder return of 7.64% and 3 year total shareholder return of 3.93% indicate momentum is still rebuilding rather than fully established.
Compare Jerónimo Martins SGPS with other food and consumer retailers under pressure on margins by scanning the hand-picked 224 high quality undervalued stocks that pair balance-sheet strength with earnings resilience.
Bulls see Jerónimo Martins SGPS as a quality retailer on sale after the recent setback in yearly returns. Bears point to softer earnings and question whether the valuation already reflects that risk.
Most Popular Narrative: 14% Undervalued
Jerónimo Martins SGPS closed at €19.33, while the most followed narrative framework points to a fair value of €22.38. This frames the recent share price recovery as only a partial catch up.
Sustained store network expansion and remodeling across Poland, Colombia, Portugal and the newer Slovakia operation, supported by around €1.2b of annual CapEx and additional logistics capacity, extends Jerónimo Martins SGPS reach and supports revenue trends and operating leverage.
See why 59 investors see Jerónimo Martins SGPS as 14% undervalued.
Result: Fair Value of €22.38 (UNDERVALUED)
Still, rising labor costs and sustained annual CapEx of about €1.2b could squeeze cash flow and weaken the Jerónimo Martins SGPS earnings narrative if trading softens.
Find out about the key risks to this Jerónimo Martins SGPS narrative.
Another View: Jerónimo Martins SGPS Through The P/E Lens
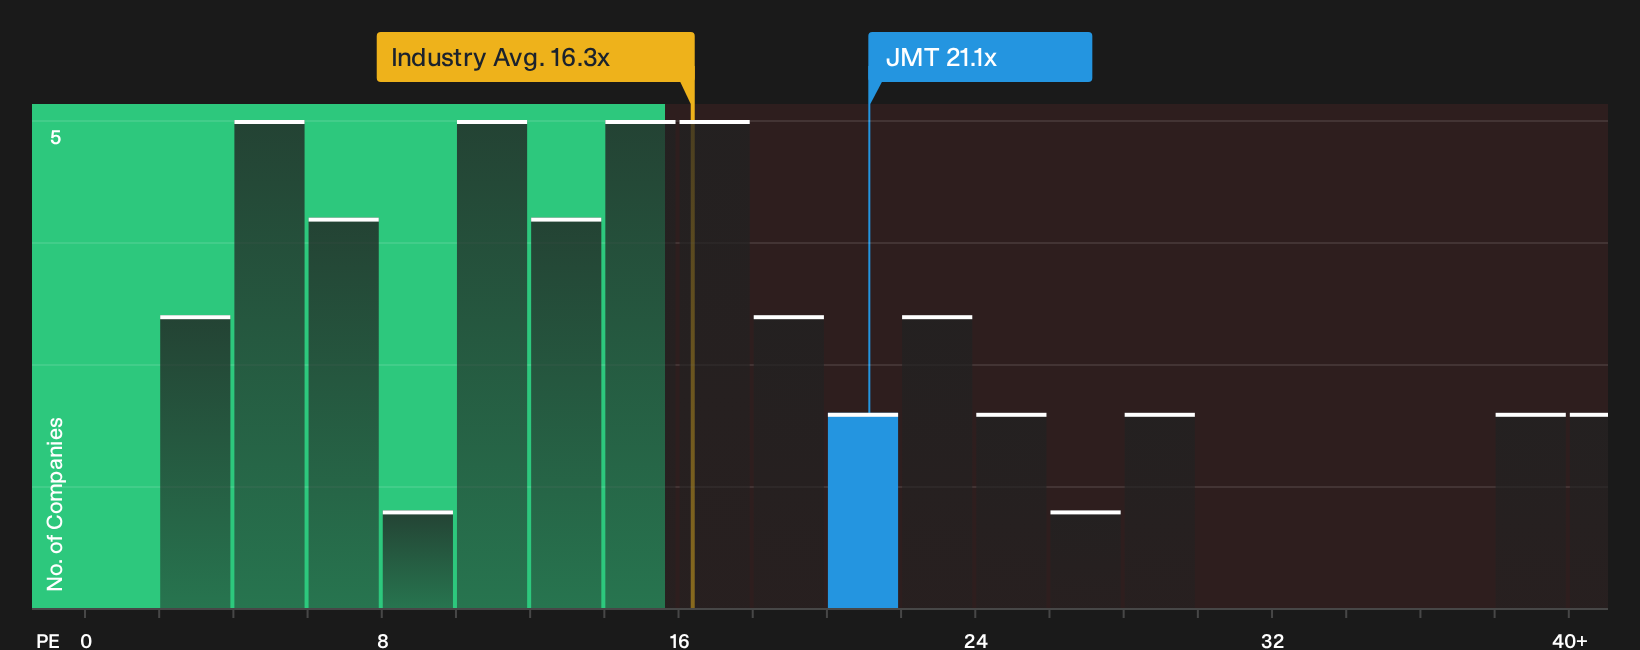
Jerónimo Martins SGPS screens as undervalued on future cash flows, yet the P/E picture is less generous. The stock trades on 21.1x earnings, above both the European Consumer Retailing group at 16.4x and an estimated fair ratio of 20x. That premium narrows the margin for error if profit growth disappoints, so consider how comfortable you are paying up for this earnings profile.
To see how that valuation gap is built from the ground up, and what it could mean if sentiment shifts toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Jerónimo Martins SGPS valuation and earnings can pull you in either direction, so move quickly, review the data, and weigh both the upside and the red flags in the 2 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Jerónimo Martins SGPS?
If Jerónimo Martins SGPS has sharpened your focus on valuation and quality, you may want to broaden your watchlist with a few focused screens that highlight different types of opportunities.
- Target generous income potential and see which companies qualify as 232 dividend fortresses for yield focused portfolios.
- Look for quality at a discount and review the 588 high quality undiscovered gems that many investors may be overlooking.
- Prioritise resilience and scan a list of solid balance sheet and fundamentals (193 results) before the crowd catches up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com