


EN
Delek US Holdings (DK) Stock Looks In Line With Its Earnings Power
Delek US Holdings has had a powerful multi‑year run, yet the stock has recently pulled back, which puts fresh focus on whether the current share price can still be explained by the earnings that support it. With a volatile track record in the near term but very strong longer term returns, investors are asking how much of that story is already reflected in the valuation.
- Over the past 5 years the stock has gained 310.3%, which puts a lot of past success on the line when judging what its earnings are worth today.
- The business relies heavily on how efficiently it converts refining operations into profits and cash, which can influence how much investors are prepared to pay for every dollar of earnings.
- The analysts covering Delek US Holdings have run their own numbers. See what analysts think Delek US Holdings's shares could be worth.
The issue now is whether Delek US Holdings' recent share price still lines up with what its earnings suggest investors should be willing to pay.
If you want a broader starting point before focusing back on Delek US Holdings, apply the same earnings lens across a basket of 39 high quality undervalued stocks.
Is Delek US Holdings Fairly Priced on Earnings?
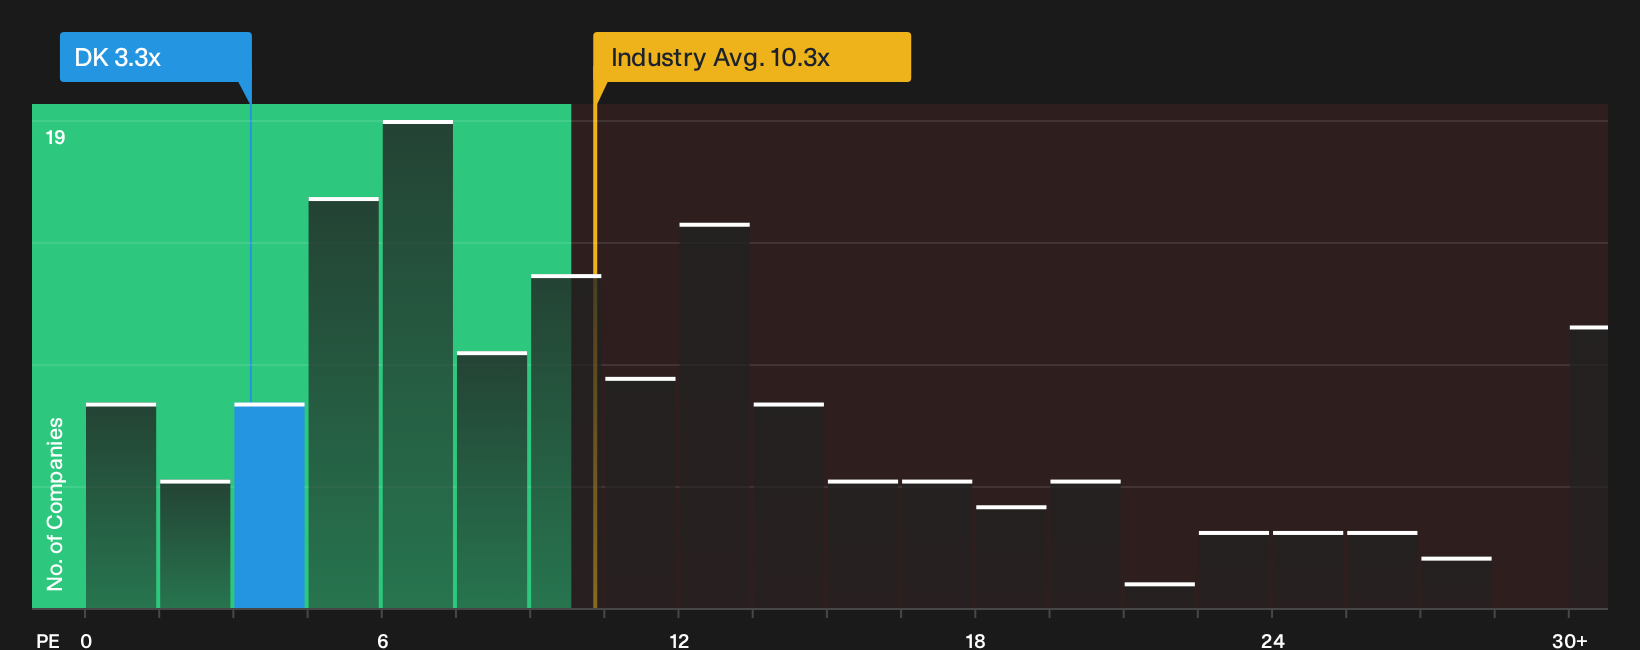
The P/E ratio works well for Delek US Holdings because earnings remain a key driver for how this refiner is judged. The current P/E sits at 3.3x, which is well below the Oil and Gas industry average of 10.3x and also under the peer group average of 8.0x. On raw comparison, the market is paying far less for each dollar of Delek US Holdings earnings than it does for similar businesses.
The model based fair multiple, which blends factors such as profitability, risk profile and size, points to a level quite close to where the shares trade today. That suggests the low headline P/E ratio lines up broadly with what those fundamentals currently support, even if it looks inexpensive next to sector benchmarks. To judge whether that gap to the industry should close or persist, you would need to weigh how durable current earnings are across cycles and how much volatility you are willing to accept. Explore the numbers behind Delek US Holdings's P/E valuation.
The Delek US Holdings Narrative: What Would Justify Today's Price?
Narratives for Delek US Holdings pick up where the valuation puzzle leaves off by setting out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today, based on scenarios shared on Simply Wall St's Community page. Where a single ratio or model gives you one neat figure, Narratives unpack the earnings paths and business conditions behind that number so you can watch how reality lines up over time.
Community views on Delek US Holdings are split between those who see more upside in the current setup and those who think expectations already look full.
Bull case: 25% undervalued
"Substantial investment in logistics and midstream infrastructure, especially the ramp-up of growth projects at DKL, is expected to materially lower feedstock and transportation costs…"
Discover why this Narrative puts Delek US Holdings at 25% undervalued.
Bear case: roughly fairly valued
"Regulatory decisions on small refinery exemptions remain critical, and despite a recent 2025 exemption decision that Delek US Holdings welcomed, the company still faces a projected 2026 Renewable Fuel Standard cost…"
Explore why this Narrative puts Delek US Holdings at roughly fairly valued.
Delek US Holdings: what expectations are already pencilled in?
Price and current earnings only tell part of the story, because analysts have laid out where they think this refiner could be a few years from now, giving you another yardstick to compare with today's valuation. Explore where analysts expect Delek US Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com