


EN
Agilent Technologies (A), What Is Drawing Fresh Attention To The Stock?
Agilent Technologies (A) is back in focus after launching its 5987A mass selective detector with GC Assist and MassHunter 14 software, tying fresh product news to an already closely watched Q4 earnings setup.
Against that backdrop, Agilent Technologies has quietly built momentum, with a 90 day share price return of 19.72% and a year to date share price gain of 26.68%, while total shareholder return over the past 3 years sits at 64.75%. This reflects growing interest as product launches, acquisitions like Proscia, and the new University of Chicago energy materials collaboration reshape how investors are weighing both growth potential and execution risk.
Scan for other lab instrumentation and life sciences stocks showing similar momentum and product catalysts to Agilent Technologies with our curated 39 high quality undervalued stocks.
Bulls see Agilent Technologies converting product wins and partnerships into durable earnings power. Bears see a crowded sector and Q4 event risk. Which side does the current valuation actually support?
Most Popular Narrative: 4% Undervalued
Agilent Technologies last closed at $174.76, compared with a widely followed fair value anchor of $181.05. This places the current setup in mildly undervalued territory and puts real weight on the execution of its operating model and replacement cycles.
The Ignite operating model continues to roll through Agilent Technologies, with management now attributing more than 100 basis points of expected FY26 operating margin expansion and about 200 basis points of strategic pricing benefit per quarter to this system. This can support net margin and EPS growth if it keeps offsetting inflation, tariffs and new capacity ramp costs.
See why 38 investors see Agilent Technologies as 3% undervalued.
Result: Fair Value of $181.05 (UNDERVALUED)
Still, the bullish story for Agilent Technologies can wobble if tariffs bite into margins again or if academia and government demand continues to soften.
Find out about the key risks to this Agilent Technologies narrative.
Another View: What Agilent Technologies’ P/E Is Really Saying
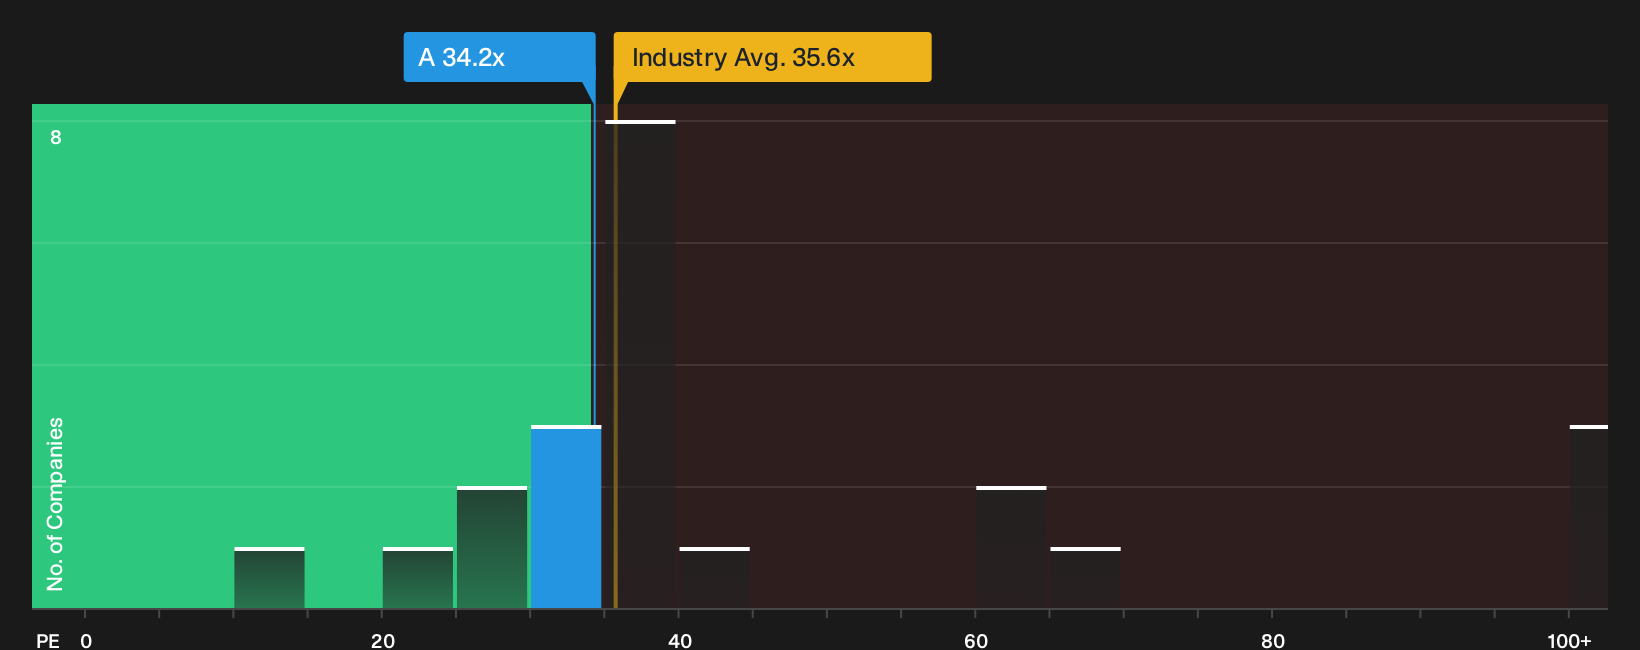
Agilent Technologies screens as 4% undervalued on that $181.05 fair value anchor, yet its 34.2x P/E tells a more demanding story. The fair ratio sits lower at 27.2x, while the peer group trades closer to 37.2x and the broader Life Sciences sector around 35.6x. That gap points to a stock that is cheaper than many rivals but still priced well above the level the market could move toward if optimism fades. Which signal do you trust more right now: the modest discount to fair value or the premium to the fair ratio?
To pressure test this pricing through a single metric view and see what the numbers imply for upside and downside risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed sentiment around Agilent Technologies leaves you undecided, consider reviewing the data first hand and stress testing your own thesis with 3 key rewards.
Looking for more investment ideas beyond Agilent Technologies?
Do not stop with Agilent Technologies. Broaden your watchlist and pressure test your thesis against other opportunities that share similar quality signals and momentum.
- Target reliable income streams by reviewing companies in our 8 dividend fortresses and see which payouts might deserve a closer look.
- Hunt for resilient balance sheets through the list of solid balance sheet and fundamentals (24 results) so you are not caught off guard when conditions get tougher.
- Spot potential early movers by scanning the 19 high quality undiscovered gems before attention and capital crowd into the same familiar tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com