


EN
Is Raised Earnings Guidance Altering The Investment Case For McKesson Stock (MCK)?
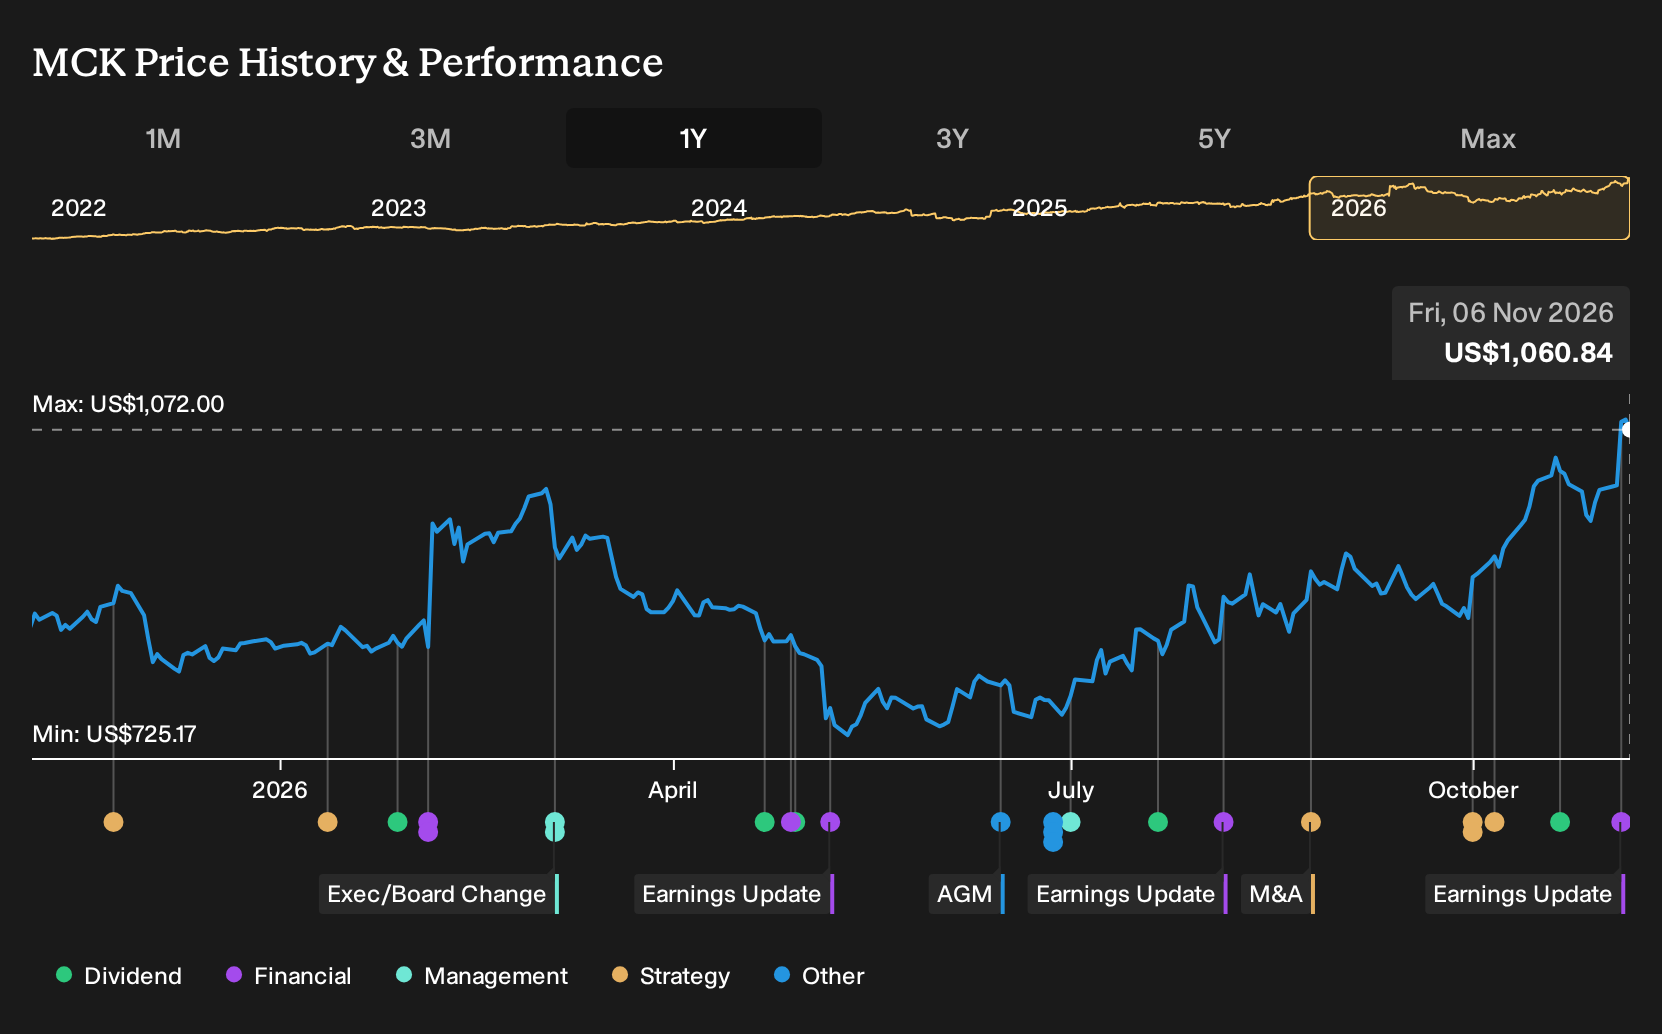
- McKesson reported past second quarter sales of US$110.96b and net income of US$1.22b, lifted earnings guidance for fiscal 2027, and closed the US$2.25b Precision Medicine Group acquisition alongside extending its CVS Health distribution agreement.
- The mix of higher adjusted earnings targets, oncology focused services from Precision Medicine Group, and a proposed Option Care Health stake indicates that McKesson is leaning further into specialty and service driven profit pools.
- We will now look at how McKesson's higher fiscal 2027 earnings guidance could reshape the broader investment narrative around the business.
Scan beyond McKesson and see how other healthcare distributors and service focused players stack up on earnings power and balance sheet strength with the curated list of solid balance sheet and fundamentals (24 results)
McKesson Investment Narrative Recap
To own McKesson, you need to believe the business can keep compounding earnings by leaning into specialty distribution, oncology services, and tech enabled access platforms while holding its razor thin margins. The latest quarter points in that direction, with higher sales, higher quarterly net income, and raised fiscal 2027 adjusted EPS guidance anchoring the near term story.
The key upside catalyst right now is execution in oncology and specialty services, including integrating Precision Medicine Group and expanding high value platforms like US Oncology Network and RxTS. The biggest risk remains on the cost and policy side. Tighter drug pricing rules, GLP 1 coverage changes, or higher cyber and security spend could quickly squeeze profitability.
The most relevant update here is McKesson lifting fiscal 2027 adjusted EPS guidance to US$45.60 to US$46.40, paired with the completed US$2.25b Precision Medicine Group deal. That combination indicates management is relying on oncology and biopharma services to carry more of the earnings burden over the next few years.
For you as a shareholder, the question is less about the guidance number and more about execution risk. Precision Medicine Group needs to be integrated cleanly into the existing oncology ecosystem, without distracting from RxTS rollouts or stressing an already leveraged balance sheet. Any stumble on integration, cyber resilience, or drug policy could blunt the catalyst investors are focused on.
On current analyst numbers, McKesson's setup assumes revenues of US$499.7b and earnings of US$6.4b by 2029. This rests on 6.7% yearly top line growth and an earnings increase of about US$1.8b from US$4.6b today.
Uncover how McKesson's fair value indicates a 3% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
Fair value views on McKesson from 3 members of the Simply Wall St Community run from about US$1,026 per share up to roughly US$1,691, a wide span that underlines how far opinions can stretch. When you set that beside regulatory and cyber risks, as well as oncology related catalysts, it highlights why exploring several viewpoints matters.
Explore 2 other McKesson fair value estimates, including one that suggests as much as 59% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your McKesson research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for McKesson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McKesson's overall financial health at a glance.
Looking For More Investment Ideas Beyond McKesson?
If McKesson has sharpened your focus on earnings quality, balance sheet strength, and clear business models, it can be useful to compare that framework across a broader watchlist using the Simply Wall St Screener.
- For investors who want income with resilience, start with companies that aim to combine robust cash generation with meaningful payouts through the 8 dividend fortresses.
- If capital preservation and steadier risk profiles matter most to you, narrow the field to businesses screened for resilient balance sheets and fewer red flags using the 29 resilient stocks with low risk scores.
- When you are hunting for underappreciated opportunities with sound fundamentals, scan for stocks that pair quality metrics with more modest valuations through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com