


EN
LifeStance Health Group (LFST) Shares Climbed, What Is Behind The Move?
LifeStance Health Group (LFST) just delivered a strong one two punch for investors, beating third quarter earnings expectations and lifting full year 2026 revenue and adjusted EBITDA guidance on the back of higher visit volumes and specialty services.
The latest numbers have quickly fed into the tape, with LifeStance Health Group now trading at US$13.77 after a 1 day share price return of 2.53% and a 30 day share price return of 13.71%. This pushed the stock to fresh highs.
Momentum has been building for much longer, as a year to date share price return of 97.84% sits alongside a 1 year total shareholder return of 118.92% and a 3 year total shareholder return of 145.45%. This suggests that the recent earnings beat and guidance raise are being treated as a continuation of an already strong trend rather than a one off reaction.
Scan other fast climbing mental health and healthcare stocks that are showing strong visit growth and improving earnings power with our curated 35 healthcare AI stocks for comparison.
After a near doubling in 2026 and fresh guidance from LifeStance Health Group, the real tension is simple: Are you still being paid enough to accept the risks at this price, or has most of the upside already been used up?
Most Popular Narrative: 5% Undervalued
LifeStance Health Group is priced at $13.77 against a most-followed fair value estimate of $14.45. This frames the current rally as still leaving a modest valuation gap on the table while putting execution in the spotlight.
The main factor that has to go right is that LifeStance successfully executes its scale and efficiency plan by expanding specialty services, rolling out its technology and AI tools, and growing into new markets while turning that growth into sustainably higher margins.
See why 5 investors see LifeStance Health Group as 5% undervalued.
Result: Fair Value of $14.45 (UNDERVALUED)
Still, the story around LifeStance Health Group can change quickly if larger tech or retail health competitors squeeze pricing, or if cash flow and returns remain weak.
Find out about the key risks to this LifeStance Health Group narrative.
Another View: What LifeStance Health Group’s P/E Is Telling You
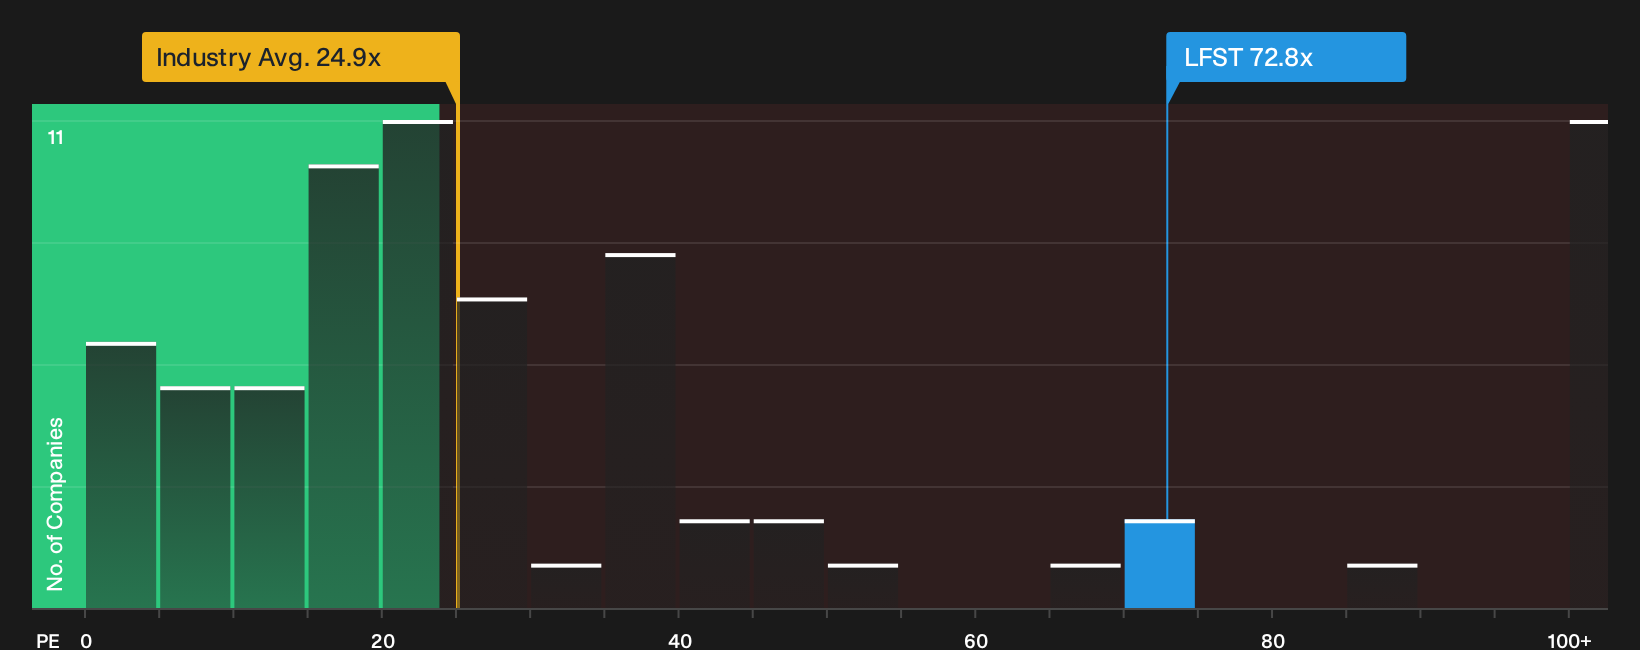
The discounted cash flow work suggests LifeStance Health Group is modestly undervalued, with the shares trading about 7% below an estimated future cash flow value of $14.81. The P/E ratio tells a very different story. At 72.8x earnings compared with the US Healthcare sector on 24.9x and a fair ratio estimate of 37.2x, investors are paying a heavy premium multiple that could compress if expectations cool.
Our P/E based work focuses on what happens if the market drifts back toward that fair ratio. It is worth stress testing both outcomes side by side before deciding how much multiple risk you are willing to carry at $13.77. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feel the mixed mood around LifeStance Health Group after the rally and rich P/E multiple. Move quickly, review both sides of the story, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond LifeStance Health Group?
If you rate the setup at LifeStance Health Group but do not want all your capital tied to a single story, broaden your opportunity set with targeted screeners.
- Target potential upside in overlooked opportunities by scanning the 19 high quality undiscovered gems that already show strong underlying fundamentals.
- Prioritize stability and capital protection by reviewing a 29 resilient stocks with low risk scores that filters for resilient businesses with lower risk profiles.
- Focus on financial strength by working through a list of solid balance sheet and fundamentals (24 results) that surfaces companies with durable balance sheets and consistent fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com