


EN
Is United Therapeutics (UTHR) Undervalued On Earnings And Its $2b Buyback?
United Therapeutics (UTHR) just paired third quarter 2026 earnings with a completed US$2.0b share repurchase, giving you fresh data on profitability, cash deployment, and how management is handling current product and pipeline spending.
United Therapeutics shares trade at US$562.02, with the price easing 6.1% over the past week but still up 3.1% over 30 days and 13.2% year to date. Total shareholder return of 25.2% over one year and more than doubling over three and five years points to momentum that has built over time as investors weigh the latest earnings dip, the completed US$2.0b buyback, and fresh clinical trial progress.
Compare United Therapeutics' buyback and pipeline mix with other healthcare groups reallocating cash into growth by scanning our hand picked 35 healthcare AI stocks.So after a softer quarter, a tight share count, and a stock that has already rewarded holders, does United Therapeutics still offer sufficient upside potential to justify the risks at this price, or has the balance shifted?
Most Popular Narrative: 16% Undervalued
On the most followed view, United Therapeutics carries a narrative fair value of about $671 per share versus a last close of $562.02. This frames the current pullback against a story built around pulmonary fibrosis, COPD related indications, and organ manufacturing.
Progress in organ replacement technologies, including three FDA authorized xenograft trials, designated pathogen free organ production facilities targeting several thousand organs per year and the approved LungFX device, lays out a path for new product lines that could add incremental revenue streams and operating leverage beyond the existing pulmonary business.
See why 34 investors see United Therapeutics as 16% undervalued.
Result: Fair Value of $670.93 (UNDERVALUED)
Still, the bullish United Therapeutics story can unravel quickly if Tyvaso uptake in pulmonary fibrosis underwhelms, or if competition erodes the shrinking base PAH franchise faster than expected.
Find out about the key risks to this United Therapeutics narrative.
Another View: What Multiples Say About United Therapeutics
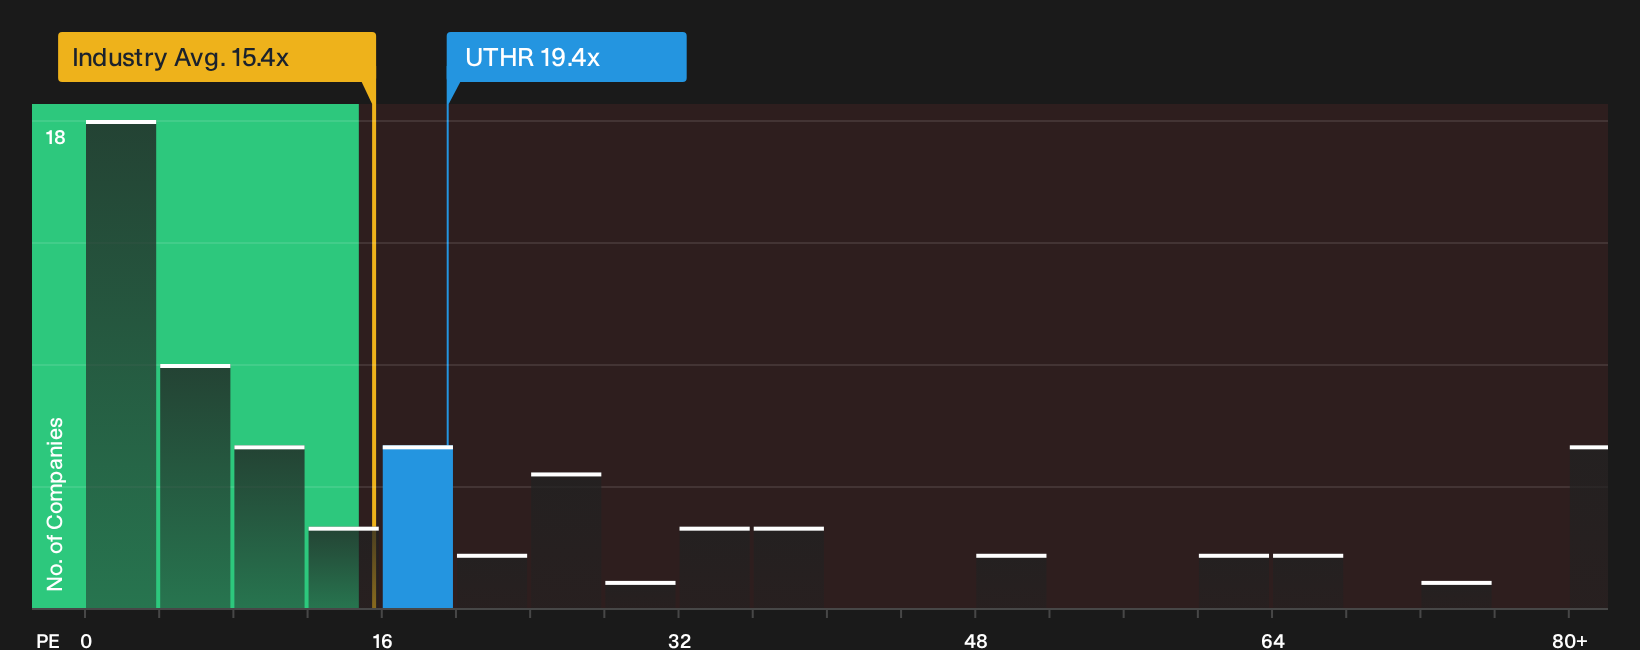
That 16% narrative discount looks appealing, but the current P/E of 19.4x already sits above the US Biotechs industry at 16.9x, even though it is well below peers at 52.2x and the fair ratio of 28x. Is the stock already pricing in a lot of good news, or is the gap to the fair ratio still worth betting on?
For a closer look at how this pricing stacks up, including where the fair ratio might pull the market over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment in this piece may lean cautiously optimistic, so move fast on your own homework and pressure test every assumption against the raw data. To see what has investors most encouraged about United Therapeutics right now, review the 2 key rewards.
Looking for more investment ideas beyond United Therapeutics?
If United Therapeutics has your attention, use that momentum and widen your watchlist with a few focused idea lists that target very different edges in the market.
- Target potential mispricings by scanning companies that combine quality fundamentals with room for rerating through the 39 high quality undervalued stocks.
- Explore potential income streams by reviewing businesses with stronger yields and resilience using the 8 dividend fortresses.
- Dial down portfolio stress by hunting for sturdier balance sheets and consistent fundamentals inside the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com