


EN
Top 3 Canadian Dividend Stocks With Yield Over 3% To Watch
Higher interest rates in the United Kingdom are squeezing mortgages and everyday borrowing, so dependable cash payouts suddenly matter a lot more. Regular income from established British dividend payers can act like a paycheck that arrives without extra effort. This article looks at a shortlist of high yielding, well covered UK dividend stocks and highlights three of the strongest candidates from that group that investors may want to keep on their radar.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding, steady dividend payers with an emphasis on coverage and consistency. However, if you want the strongest names, these 3 dividend aristocrats stocks are the top of the list.
PrairieSky Royalty (TSX:PSK)
Overview: PrairieSky Royalty generates royalty income by leasing its extensive Canadian crude oil and natural gas acreage to third party producers. This turns production on its lands into relatively stable, high margin cash flow that anchors its dividend profile.
Operations: PrairieSky Royalty earns CA$550.2 million from oil and gas exploration and production royalties in Canada, with all revenue sourced domestically from this activity.
Market Cap: CA$8.0b
PrairieSky Royalty fits the Dividend Powerhouses theme because its royalty model is designed to convert operator activity on its 9.9 million acres into steady cash, which can support a covered, recurring payout rather than capital hungry drilling budgets.
"Continued shift toward longer reach multilateral drilling and expanded waterflood and polymer flood programs on PrairieSky lands should lift recovery factors and sustain higher royalty volumes per well over time, which supports steady revenue growth and stronger earnings resilience."
The real swing factor for PrairieSky Royalty’s dividend appeal is how one evolving production trend ultimately flows through to long term cash margins.
That cash margin hinge is exactly what the full narrative for PrairieSky Royalty unpacks, revealing how drilling intensity, capital discipline and payout ambitions could be quietly accelerating the story.

Peyto Exploration & Development (TSX:PEY)
Overview: Peyto Exploration & Development is a Calgary based producer that focuses on natural gas and liquids in Alberta’s Deep Basin, using that cash flow to fund a monthly dividend within the Dividend Powerhouses (3%+ Yield) theme.
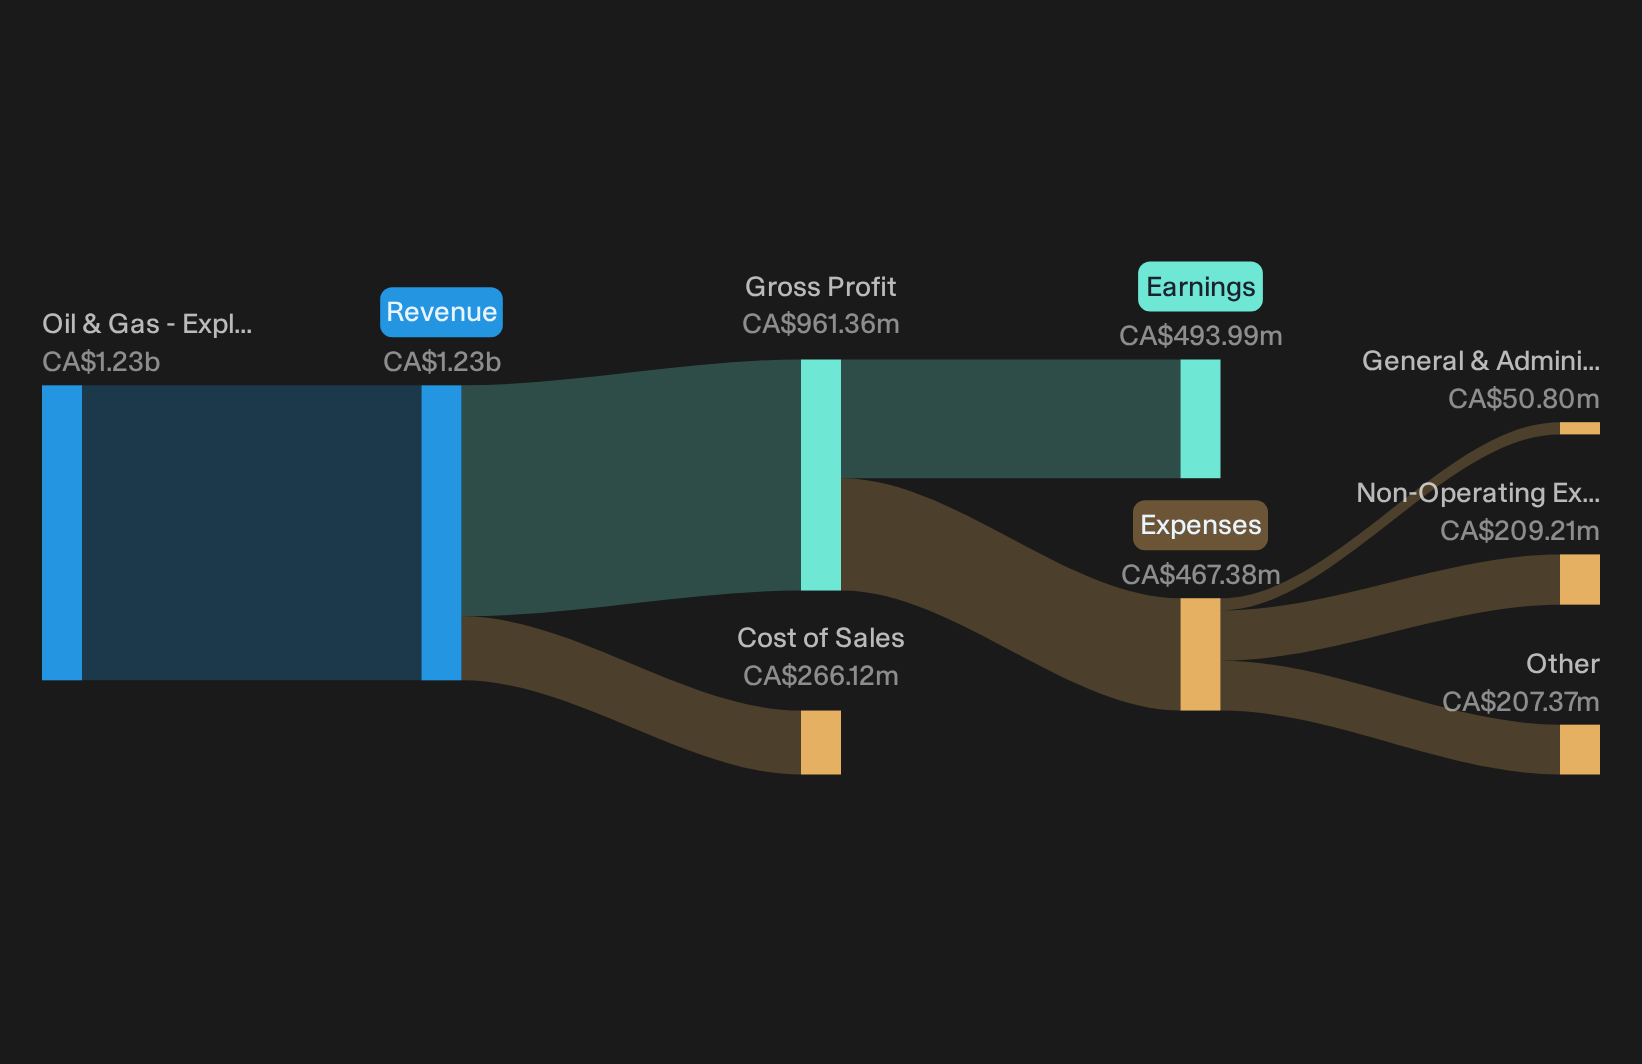
Operations: Peyto generates about CA$1.23b in revenue from oil and gas exploration and production, with all of it coming from Canadian operations.
Market Cap: CA$4.9b
Where PrairieSky leans on royalties, Peyto Exploration & Development gives you direct exposure to Deep Basin production with a monthly dividend built on operating cash flow rather than one off asset sales. That structure is often what investors look for in a high yielding, coverage focused screen.
"Peyto Exploration & Development’s consistently low controllable cash cost structure, supported by Q2 2026 costs of $1.04 per Mcfe and a 2025 PDP FD&A cost of $0.94 per Mcfe, positions the company to keep more cash flow per unit of production, which is important for net margins and earnings when sector sentiment is weak."
What really matters now is how one quiet shift in its revenue mix shapes the breathing room around that monthly payout.
That breathing room is exactly what the full narrative for Peyto Exploration & Development unpacks, showing where Peyto Exploration & Development’s payout could be quietly decoupling from headline sentiment.
Bank of Nova Scotia (TSX:BNS)
Overview: Bank of Nova Scotia is a Toronto based universal bank that earns dividend supporting cash flow from broad Canadian and international retail, commercial and wealth banking operations.
Operations: Bank of Nova Scotia generates about CA$11.9b from Canadian Banking, CA$9.6b from International Banking, CA$7.1b from Global Wealth Management and CA$6.8b from Global Banking and Markets.
Market Cap: CA$156.4b
Bank of Nova Scotia matters for this Dividend Powerhouses theme because its everyday banking and wealth franchises generate earnings that fund a covered payout, with international operations adding another layer of diversified cash flow behind that income stream.
"Expansion of banking and wealth management services in Pacific Alliance markets such as Mexico, Peru, Chile and Colombia remains a live driver, with International Banking revenue and loan growth in these regions and ROE above 16% pointing to further potential for fee income and earnings as Bank of Nova Scotia continues to deepen client relationships."
A key factor for Bank of Nova Scotia’s dividend appeal is how an evolving capital and credit trade off ultimately plays out.
How that capital and credit trade off evolves is exactly what the full narrative for Bank of Nova Scotia maps out. It highlights where Bank of Nova Scotia’s earnings power could be quietly accelerating beyond headline noise.

Curious About Dividend Alternatives?
Fresh opportunities move fast. Some ideas are building quiet breakout momentum while others get caught dropping off the radar. Scan these curated shortlists before the crowd and act now.
- Target resilient payers that still look reasonably priced and carry less drama by running a pass through the 9 resilient stocks with low risk scores while that edge is under the radar for now.
- Ride the next wave of infrastructure demand by reviewing the curated 42 power grid technology and infrastructure stocks before capital chases the same stories and valuations start flying.
- Position beside fast growing automation leaders by screening the hand picked 89 robotics and automation stocks while these themes are fresh and long term interest is still building.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com