


EN
EchoStar (ECHO) Turns Profitable Again Following A Cash And Spectrum Value Debate
Third quarter earnings swing and what it means for EchoStar
EchoStar (ECHO) just posted a sharp move back into profit for the third quarter of 2026, with earnings per share turning positive and management attention shifting to cash deployment and spectrum use.
The earnings swing has arrived alongside a mixed share price pattern for EchoStar. The 1 day share price return of 5.23% contrasts with a year to date decline of 15.65%. At the same time, the 1 year total shareholder return of 28.77% and very large 3 year total shareholder return of roughly 8.5x suggest longer term momentum has been strong, even as near term moves reflect shifting views on earnings quality, cash use and its SpaceX and spectrum exposure.
Capture this earnings swing in context by lining EchoStar up against other cash rich, asset heavy players on the list of solid balance sheet and fundamentals (24 results).EchoStar now looks like a cash rich, asset heavy operator with a share price that has only partly caught up to the earnings swing. The real issue is whether that mix still offers enough value at today’s level.
Most Popular Narrative: 27% Undervalued
EchoStar's most followed narrative puts fair value at $130.20 against a last close of $94.62, so the share price sits well below that anchor and leaves the current earnings swing framed through an asset and capital lens rather than a pure operating story.
The view on EchoStar has shifted from a growth story centered on building out satellite and hybrid connectivity networks to a broader capital allocation and asset value narrative that now focuses on cash, spectrum, and concentrated exposure to SpaceX equity.
EchoStar was viewed primarily as a growth story around building a LEO constellation, spectrum backed services and long term connectivity revenue. It is now framed around capital allocation choices, cash on hand, spectrum as a financial asset and concentrated SpaceX equity exposure.
See why 28 investors see EchoStar as 27% undervalued.
Result: Fair Value of $130.20 (UNDERVALUED)
Still, EchoStar’s narrative could be shaken if bankruptcy related claims around DISH entities absorb more cash than expected, or if SpaceX equity volatility hits reported book value.
Find out about the key risks to this EchoStar narrative.
Another View on EchoStar’s valuation
Analysts lean on future earnings to justify EchoStar at a fair value of $130.20, yet Simply Wall St’s DCF model points to a future cash flow value of $44.19. One lens implies EchoStar is undervalued, while the other suggests it trades well above fair worth. Which yardstick do you trust more for your own work?
Look into how the SWS DCF model arrives at its fair value.
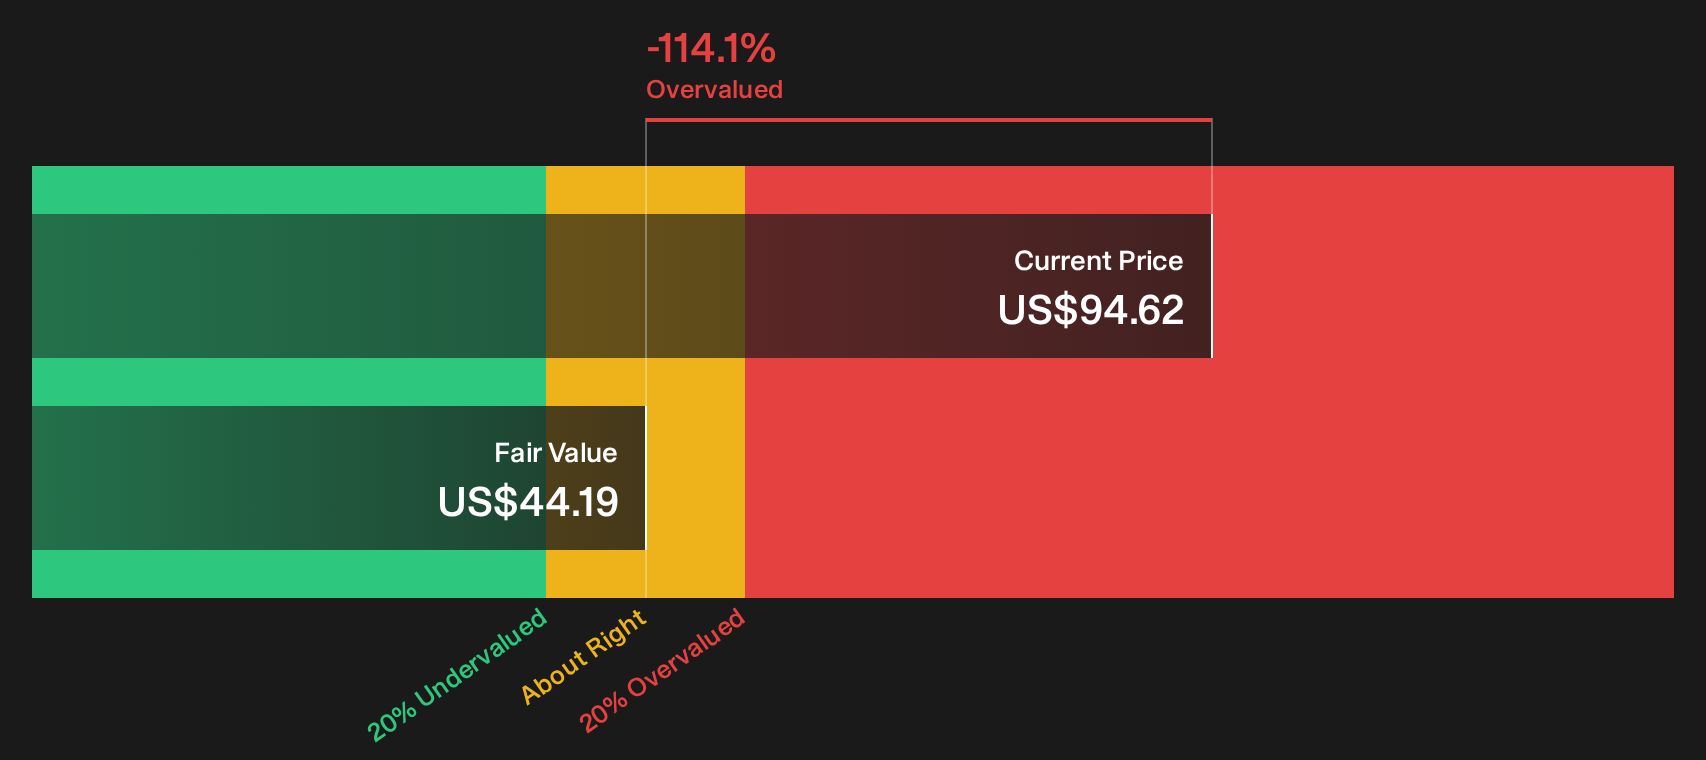
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out EchoStar for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on EchoStar is clearly split, with investors weighing both cash strength and headline risks. Move quickly, review the underlying data, and then judge the trade off for yourself by checking the 4 key rewards and 2 important warning signs.
Looking for more EchoStar style investment ideas?
If EchoStar has sharpened your focus on value and risk, do not stop there. Use the Simply Wall Street Screener to surface fresh, data driven stock ideas fast.
- Target quality at a discount by scanning for resilient businesses trading below their estimated worth through the 39 high quality undervalued stocks.
- Protect your downside by filtering for companies with stronger finances and cleaner balance sheets using the 29 resilient stocks with low risk scores.
- Get ahead of the crowd by hunting for financially robust companies that are still flying under the radar with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com