


EN
Allegion (ALLE) Leans On Demand And Deals Following A Modest Undervalued View
Event backdrop and why Allegion is on investors’ radar
Recent commentary from Allegion (NYSE:ALLE) has highlighted firm-wide demand, operational focus, and the integration of Overly Door Company and DCI Hollow Metal, along with upcoming conference remarks intended to reinforce management’s confidence message.
Allegion’s recent message on demand and acquisitions comes after a sharp 25.3% 30 day share price return and a 15.2% year to date share price gain. The 3 year total shareholder return of 87.1% signals momentum that long term holders have already felt.
Scan beyond Allegion and line up other security and industrial plays that show similar momentum and acquisition-driven stories with the curated 39 high quality undervalued stocks.
After Allegion’s sharp 30 day surge and upbeat messaging on acquisitions, the real tension now sits in the price. Does the current valuation still leave enough upside to justify fresh risk for new buyers?
Most Popular Narrative: 4% Undervalued
Allegion closed at $185.39 against a widely followed fair value estimate of $193.64, so the prevailing story in the market leans toward modest undervaluation. That view depends on how mix, margins and capital deployment evolve over time.
Robust expansion in smart and connected security solutions, with low teens electronics growth in the Americas in Q2 2026 and a pipeline of new Allegion products such as Schlage XE360 with RealSync Wi Fi and the Sense Pro smart deadbolt with Matter over Thread, supports a higher mix of recurring and software linked revenue and can lift both future revenue and adjusted operating margin.
See why 13 investors see Allegion as 4% undervalued.
Result: Fair Value of $193.64 (UNDERVALUED)
Still, Allegion’s thesis can crack if International weakness persists or if demand for electronic and mobile access cools, which would challenge the current earnings and valuation narrative.
Find out about the key risks to this Allegion narrative.
Another angle on Allegion’s valuation
While analyst fair value for Allegion sits around $193.64, Simply Wall St’s DCF model points to a future cash flow value of $157.92 with the shares at $185.39. That implies Allegion trades above this cash flow view. Which perspective do you rely on when real money is at stake?
For readers who want to see how a cash flow driven lens treats Allegion, the SWS DCF model is laid out in full in Look into how the SWS DCF model arrives at its fair value.
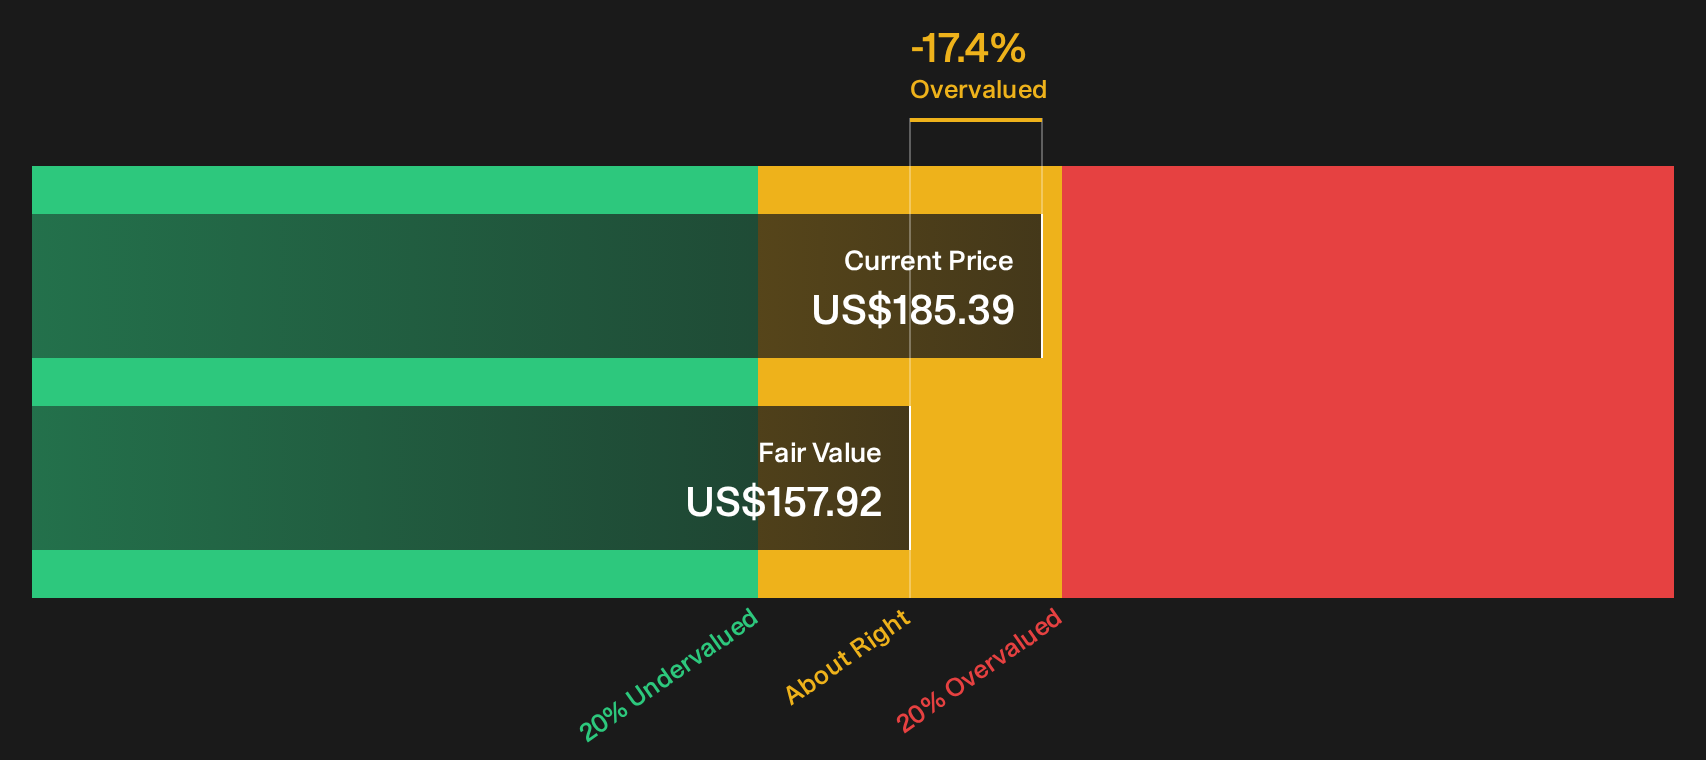
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Allegion for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Reading Allegion’s mixed signals on value, risk and momentum is one thing; testing them against your own hurdles is another. Move quickly, review the underlying data, and pressure test both the upside story and the downside worries by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Allegion?
If Allegion has sharpened your focus on quality, do not stop here. Broader opportunity often sits with the companies you have not checked yet.
- Target higher potential by scanning a focused group of smaller companies with strong metrics through the 9 elite penny stocks with strong financials.
- Tighten your margin of safety by reviewing a hand picked set of attractively priced businesses in the 39 high quality undervalued stocks.
- Steady your portfolio by filtering for robust balance sheets and resilient fundamentals via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com