


EN
Does Raised Guidance Change The Bull Case For Ensign Group (ENSG)?
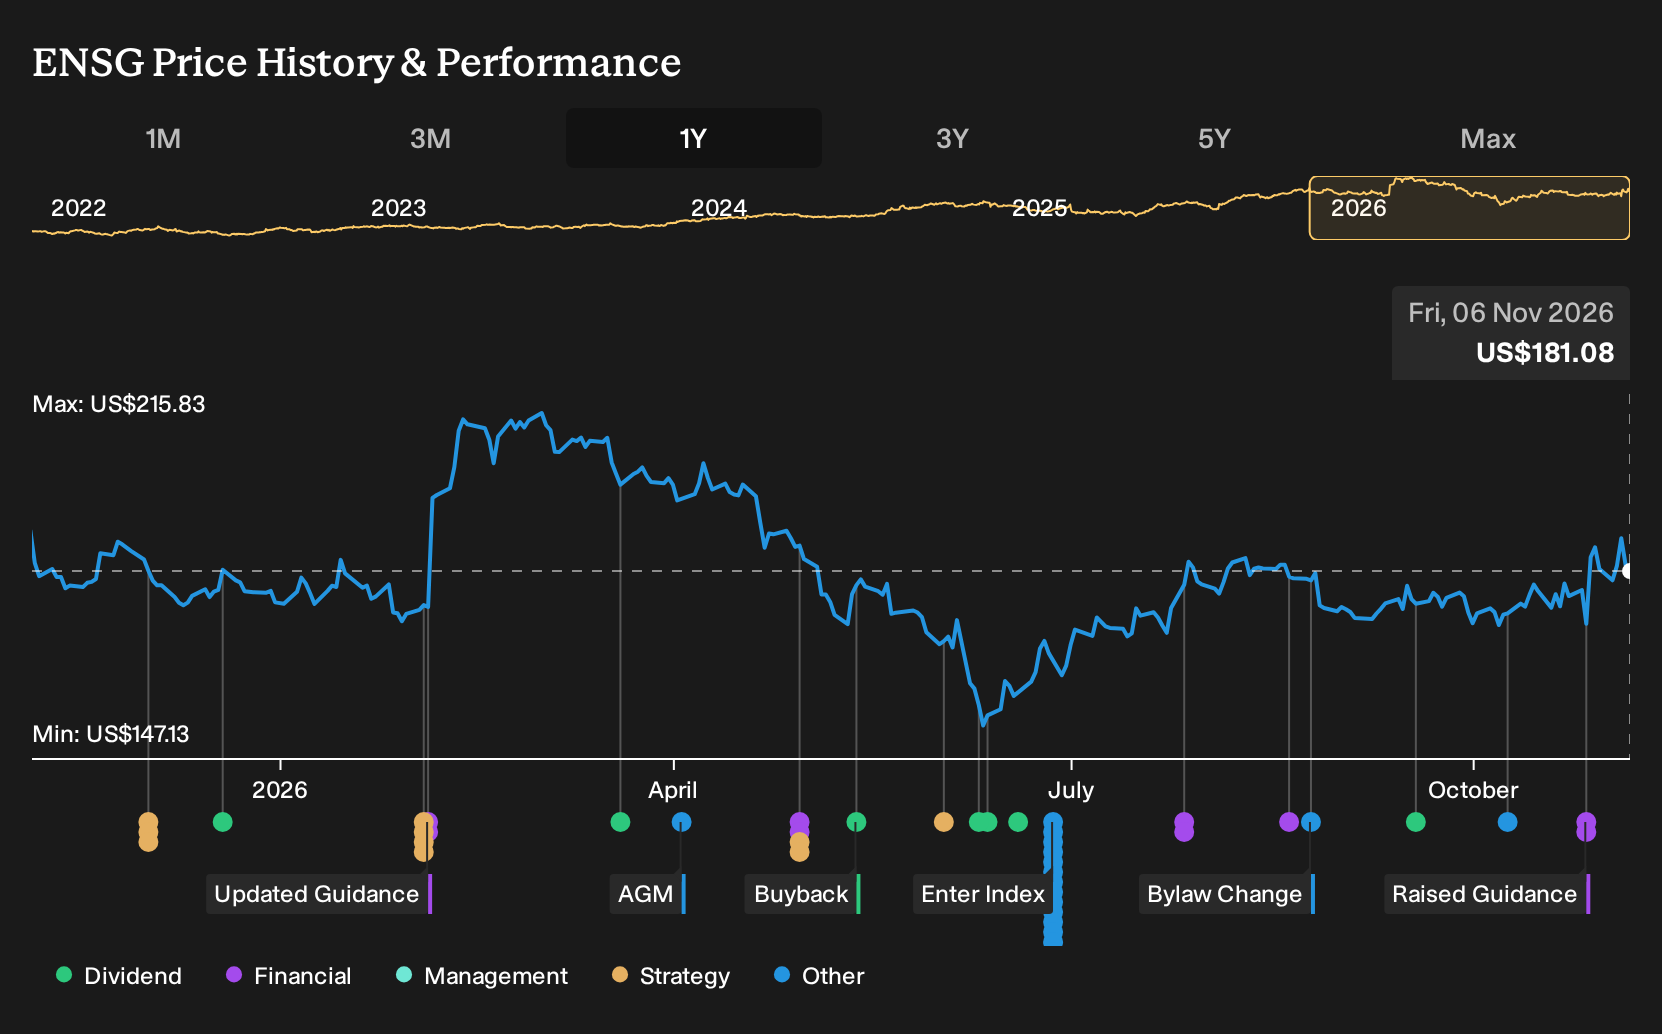
- Ensign Group raised its 2026 earnings outlook to a range of $7.94 to $8.02 per diluted share and lifted the lower end of its annual revenue guidance to $5.89b, alongside third quarter basic EPS from continuing operations of $1.80 and diluted EPS of $1.76.
- The combination of higher full year guidance and year over year EPS growth for both the third quarter and the first nine months highlights how Ensign Group’s operating model in skilled nursing and senior care is currently translating into stronger per share profitability.
- This article will examine how Ensign Group's investment narrative is influenced by the raised 2026 earnings guidance alongside strong EPS delivery.
Scan how Ensign Group’s raised guidance compares with other operators by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).
Ensign Group Investment Narrative Recap
To own Ensign Group, you need to believe its cluster model in skilled nursing and senior care can keep filling low occupancy facilities, hold staffing tight and maintain quality scores that support referrals and skilled mix. The raised 2026 EPS and revenue guidance points to management seeing enough operational traction to reflect current trends rather than a new short term catalyst.
The near term swing factor still looks like execution on recently acquired, clinically challenged sites and managing any shifts in Medicare or Medicaid reimbursement. Those same issues remain the biggest risk. The new guidance does not remove that exposure, but it suggests no fresh pressure is visible in the current run rate.
The most relevant update here is the third quarter and nine month earnings report, which showed basic EPS from continuing operations of US$1.80 in the quarter and US$5.25 year to date, with diluted EPS at US$1.76 and US$5.11 respectively. That delivery gives you concrete evidence of how the existing footprint is converting census, mix and cost control into per share earnings.
For catalysts, this EPS performance sits next to the higher 2026 guidance and ties directly to the acquisition and turnaround story. Consistent quality metrics and lower reliance on contract labor are key supports for that trajectory, while reimbursement changes and slower than expected improvement at new facilities remain the operational threats investors need to keep at the front of their minds.
Ensign Group's analyst narrative points to about US$7.9b in revenue and US$601.1 million in earnings by 2029. This aligns with a forecast revenue growth rate of 11.5% a year and an earnings increase of roughly US$202 million from US$399.1 million today.
Uncover how Ensign Group's fair value indicates a 25% potential upside to its current price that could narrow quickly if Ensign Group continues to execute its strategy.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between roughly US$161 and US$226 per share, so you are seeing a wide band of views around Ensign Group. These private investors have not yet refreshed their work for the raised 2026 guidance, which makes reimbursement risk and acquisition execution worth weighing before you rely on any single viewpoint.
Explore 2 other Ensign Group fair value estimates, including one that suggests as much as 11% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ensign Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Ensign Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ensign Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ensign Group?
After sizing up Ensign Group, it can help to widen the lens and see how other businesses with different profiles stack up on quality, value and balance sheet strength using the Simply Wall St Screener.
- If you want companies that combine financial resilience with measured risk, start by scanning a 29 resilient stocks with low risk scores that may hold up better when conditions get tougher.
- For investors who care most about quality at a sensible entry point, run through a curated 39 high quality undervalued stocks that blend stronger fundamentals with appealing pricing.
- Income focused readers can round out their watchlist by checking a 8 dividend fortresses that pair higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com