


EN
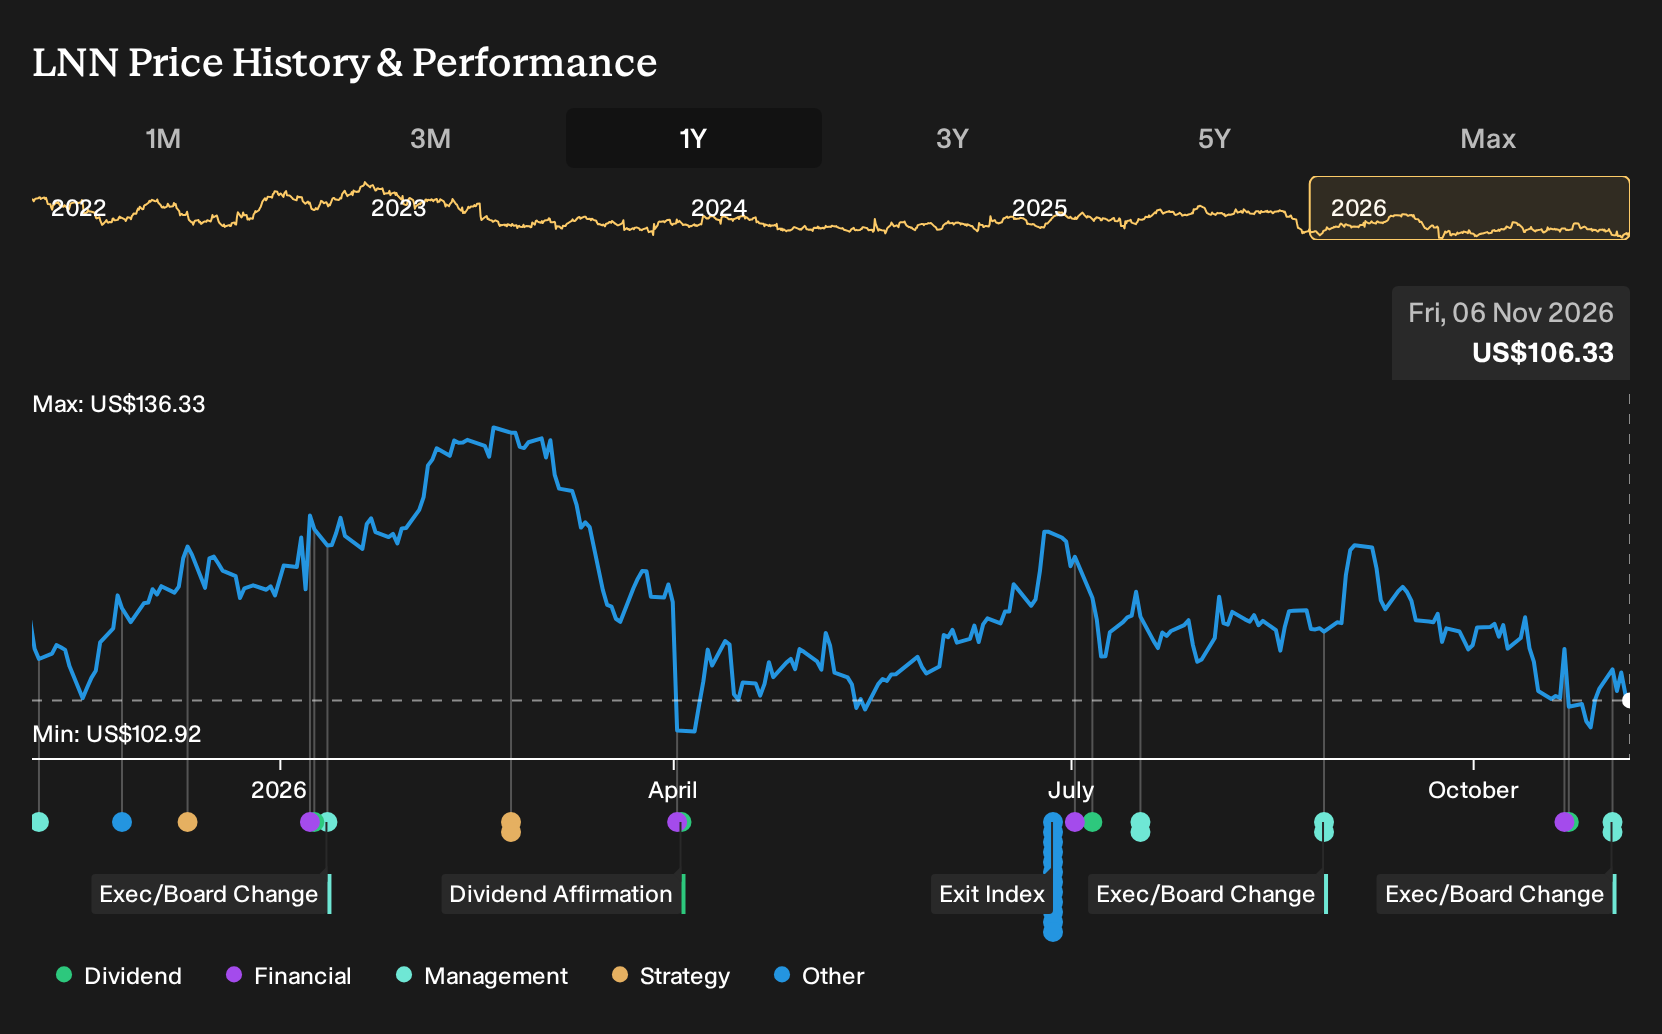
How Investors May Respond To Lindsay (LNN) New CFO Appointment
- Lindsay Corporation confirmed that interim co-CFOs Brett Coburn and Alicia Pfeifer will step back to their prior finance roles as Michael Koch, an experienced finance leader with nearly 30 years across multiple industrial and service businesses, becomes Chief Financial Officer and principal financial officer effective November 9, 2026.
- The appointment brings a CFO with a background in corporate planning, divisional P&L oversight and private equity backed environments. This background could influence how Lindsay balances irrigation and infrastructure investment, cost discipline and capital allocation in a period of mixed end market demand.
- We will explore how Lindsay Corporation's investment narrative around irrigation cyclicality, infrastructure projects and capital allocation interacts with Michael Koch's CFO appointment.
Scan how Lindsay's leadership shake-up compares with peers handling similar transitions by reviewing the handpicked list of solid balance sheet and fundamentals (24 results) in capital intensive sectors.
Lindsay Investment Narrative Recap
To own Lindsay, you need to believe the irrigation cycle eventually rewards its investments in Project Fortify, digital irrigation platforms and international projects, while infrastructure handles lumpier Road Zipper work through steadier safety product demand. In the near term, the key swing factor still appears to be execution on irrigation volumes and margins, not this CFO change.
The main operational risk stays the same. Weak North American grower sentiment, project timing in infrastructure and high capex in Nebraska put pressure on near term earnings quality. Michael Koch’s arrival gives Lindsay a seasoned finance leader for capital allocation and cost discipline, but the appointment itself does not materially change those core drivers.
The appointment of Michael Koch as Chief Financial Officer is the announcement that matters most here. His background in corporate planning, divisional P&L oversight and private equity backed environments aligns with Lindsay’s need to balance heavy Project Fortify spending with returns from irrigation technology, the MENA irrigation project and the infrastructure pipeline.
Investors watching catalysts such as the new Nebraska galvanizing facility and restructuring savings in fiscal 2027 may focus on how Koch manages depreciation, cash flow and project timing against still soft North American irrigation conditions. Execution risk around capex and margin mix remains, but this finance leadership change is directly tied to how those levers are managed.
Lindsay's current earnings sit at US$55.2 million, with analysts forecasting US$74.9 million of earnings and US$702.0 million of revenue by 2029. According to these forecasts, this would represent 3.8% yearly revenue growth and an earnings increase of roughly US$19.7 million from today.
Uncover why Lindsay's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster between US$123 and about US$139 per share, which already shows how far opinions can stretch even in a tiny sample. Those views were set before Michael Koch’s appointment and before newer irrigation and infrastructure data, so you should treat them as starting points and explore a wider spread of community perspectives around Lindsay.
Explore another Lindsay fair value estimate, including one that suggests up to 31% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Lindsay research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Lindsay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Lindsay's overall financial health at a glance.
Looking for more ideas beyond Lindsay?
If Lindsay has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you line up other companies that match your risk tolerance, return goals and time horizon.
- For investors who want potential mispricings with quality fundamentals, scan a focused 39 high quality undervalued stocks that already meet strict balance sheet and cash flow checks.
- If you care most about resilient business profiles and capital strength, filter for stability first through a curated 29 resilient stocks with low risk scores that scores well on risk factors.
- When you want to go off the beaten path and spot opportunities before they are widely followed, sort through a targeted 19 high quality undiscovered gems with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com