


EN
3 Insurance Stocks With Pricing Power In Commercial Auto
Freight crashes, nuclear jury awards, and a tightening pool of qualified truck drivers are quietly reshaping how risk gets priced in commercial auto insurance. This is not just a trucking story. It is a test of which insurers can handle heavier liability pressure without losing the plot. This article walks through three stocks from our U.S. Commercial Auto Insurance and Liability Risk Underwriters screener that may be positioned to benefit from these shifts.
The stocks covered below are only a sample, since the full U.S. Commercial Auto Insurance and Liability Risk Underwriters screen surfaced 13 more insurers and reinsurers with equally compelling liability stories that are not broken down in this article. To see the whole field and quickly identify which carriers you want to research first, go straight to the U.S. Commercial Auto Insurance and Liability Risk Underwriters screener.
Progressive (PGR)
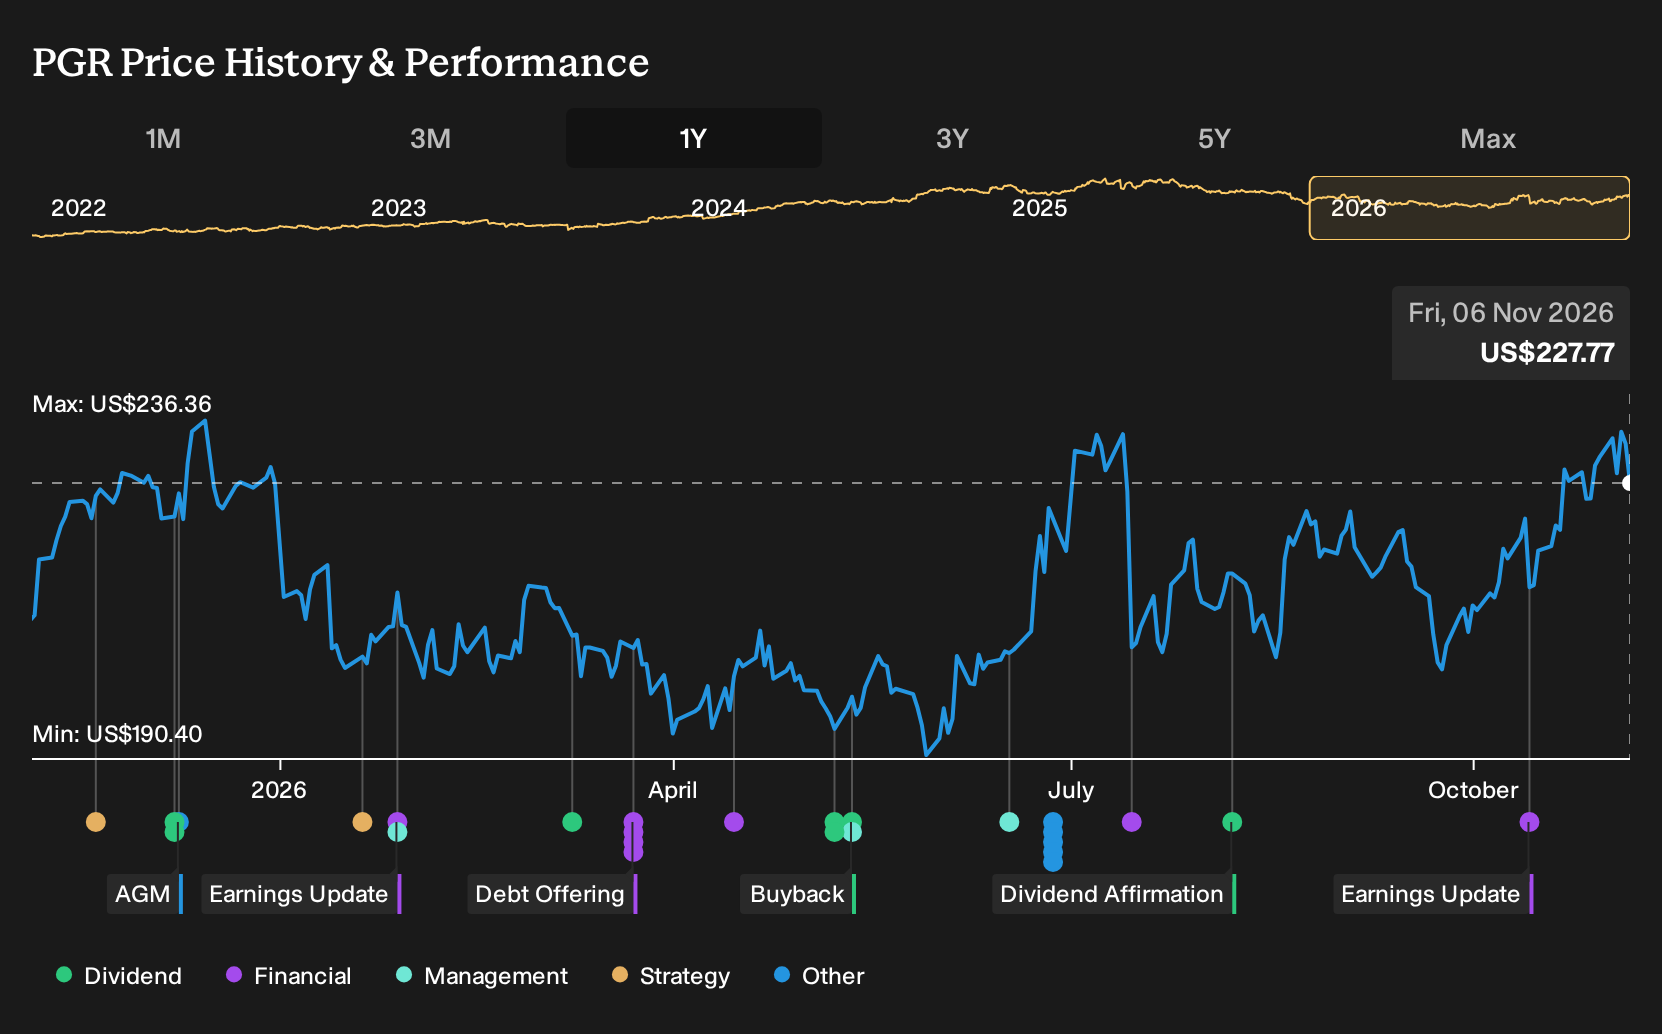
Progressive matters for this screener because its massive personal auto book sits alongside a sizable commercial portfolio that touches trucks, small fleets, and transportation liability. This gives the insurer a front row seat as crash severity, litigation risk, and freight trends reshape how commercial auto risk is priced.
"Persistent growth in U.S. vehicle ownership, population, and rising vehicle complexity expand the addressable market and increase demand for auto insurance, which can underpin Progressive's top line revenue over time."
What really moves the needle is how one evolving pressure on commercial auto claims costs feeds through into pricing power and future underwriting margins.
Progressive is a large U.S. insurer with a broad mix of personal and commercial policies, including meaningful exposure to trucking and small-business fleets that ties directly into commercial auto liability. Most revenue comes from personal lines including property at about US$75.9b, with commercial lines adding roughly US$10.8b and other items, including segment adjustments, rounding out the total. The group is sizeable, with a market value near US$135.1b.
That pricing muscle is the real hinge for Progressive, and the full narrative for Progressive shows how commercial pressure, capital discipline, and liability trends could be decoupling.
Skyward Specialty Insurance Group (SKWD)
Skyward Specialty Insurance Group focuses on complex commercial auto and liability risks that are being repriced as crash severity and litigation costs climb. This is why its niche specialty approach is particularly relevant for this screener.
"The Apollo Lloyd's platform is growing fee generating gross written premiums and underwriting fee income on a capital light basis, and management reiterates guidance for full year net underwriting fee income, which can add a recurring, less capital intensive earnings stream on top of insurance underwriting results."
The extent to which Skyward Specialty Insurance Group can develop that model will likely depend on how one less visible pressure affects future underwriting margins.
That hidden pressure is exactly what the full narrative for Skyward Specialty Insurance Group unpacks, highlighting where Skyward Specialty Insurance Group’s fee model could be masking underappreciated underwriting torque.

CNA Financial (CNA)
CNA Financial is a long-established commercial insurer with deep roots in property and casualty lines that include commercial auto, giving it direct exposure to how trucking and transportation liability is repriced. Most revenue comes from P&C Commercial at about US$6.7b, P&C Specialty adds roughly US$5.7b, International contributes about US$1.5b, and Life & Group around US$1.3b, backing a US$13.0b market cap.
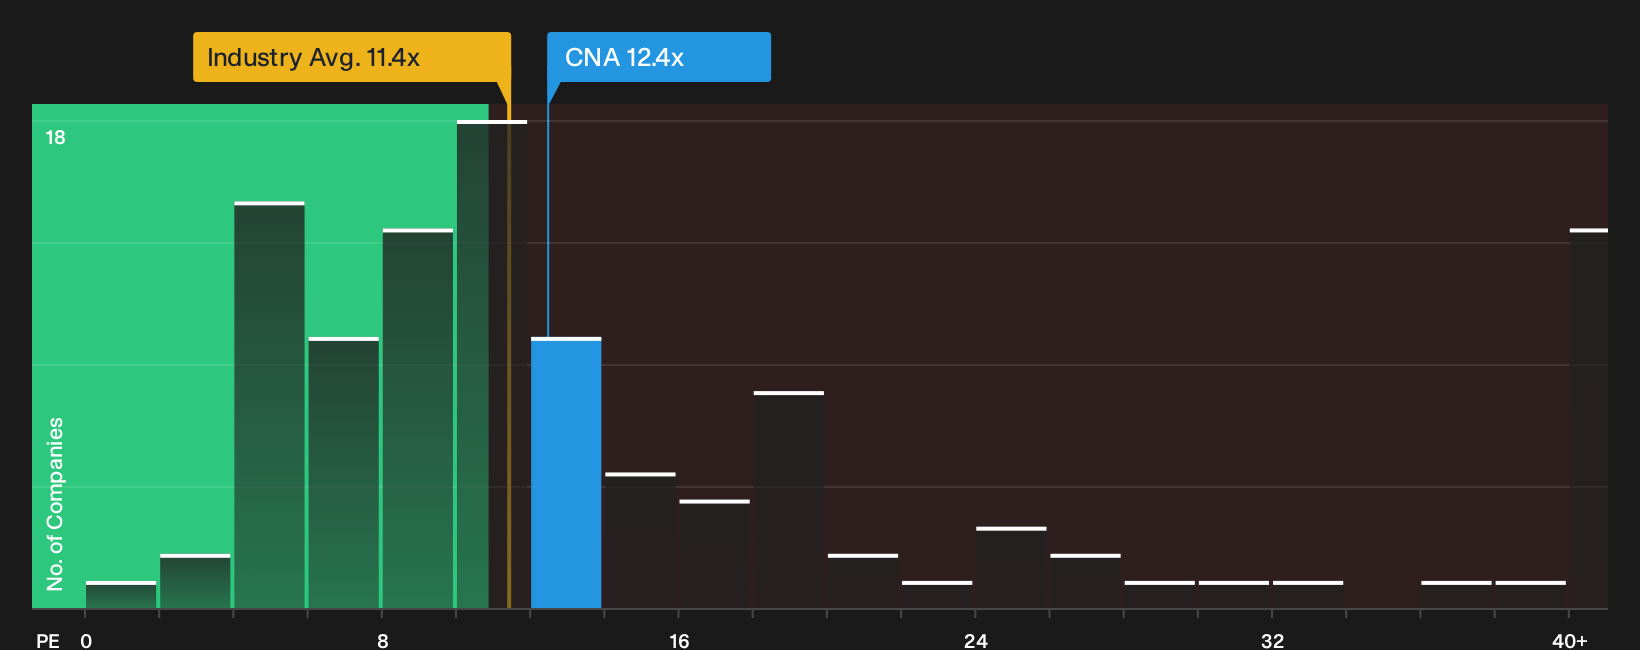
For investors tracking commercial auto and trucking liability, CNA Financial brings scale in U.S. P&C, a P/E below peers at 12.4x versus 15.7x, and a business mix where auto sits alongside workers' comp and general liability. Interest focuses on how much of that portfolio can hold or expand pricing power if a single pressure on heavy-vehicle claims costs shifts.
If that pressure on heavy-vehicle claims is what you are watching, the 3 key rewards and 2 important warning signs shows where CNA Financial’s pricing power could really start to bite.
Curious About Alternative Opportunities?
Fresh ideas move first. By the time momentum headlines hit, the earliest entries are already flying. Scan these breakout themes before the crowd and act now.
- Spot potential breakout yield stories before they get crowded by running through a curated pool of income ideas in the 8 dividend fortresses.
- Track real businesses riding the AI wave without burning cash recklessly by reviewing the hand picked set inside the 41 profitable AI stocks that aren't just burning cash.
- Get ahead of the next infrastructure build out cycle by sifting through a focused group of enablers in the 42 power grid technology and infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com