


EN
First Bancorp (FBNC) Opens Charlotte Branch, Is It Still 36% Below Fair Value?
New Charlotte branch puts First Bancorp’s regional growth in focus
First Bancorp (FBNC) just put fresh bricks in the ground. Its subsidiary First Bank opened a new SouthPark branch in Charlotte, extending the group’s reach in a key North Carolina market.
Recent trading has been firm for First Bancorp, with a 1 month share price return of 9.64% and a year to date share price gain of 26.89%. The 1 year total shareholder return of 28.51% hints that investors have been rewarding the story over time, even as the stock saw only a small move over the last quarter and a modest slip in the latest session at US$64.60. The strong 3 year total shareholder return of 133.71% suggests that confidence in the bank’s expansion moves, including the Charlotte branch and other developments such as the recent Argus target price adjustment, has been building rather than fading.
Scan a curated field of regional banks showing solid momentum and balance sheets that resemble First Bancorp by zeroing in on the list of solid balance sheet and fundamentals (24 results).
First Bancorp now trades at a clear discount to both analyst targets and an implied fair value, even after the recent rally. Is that patience being mispriced caution, or is the market flagging real risks around this expansion story?
Preferred P/E of 16.4x: Is it justified for First Bancorp?
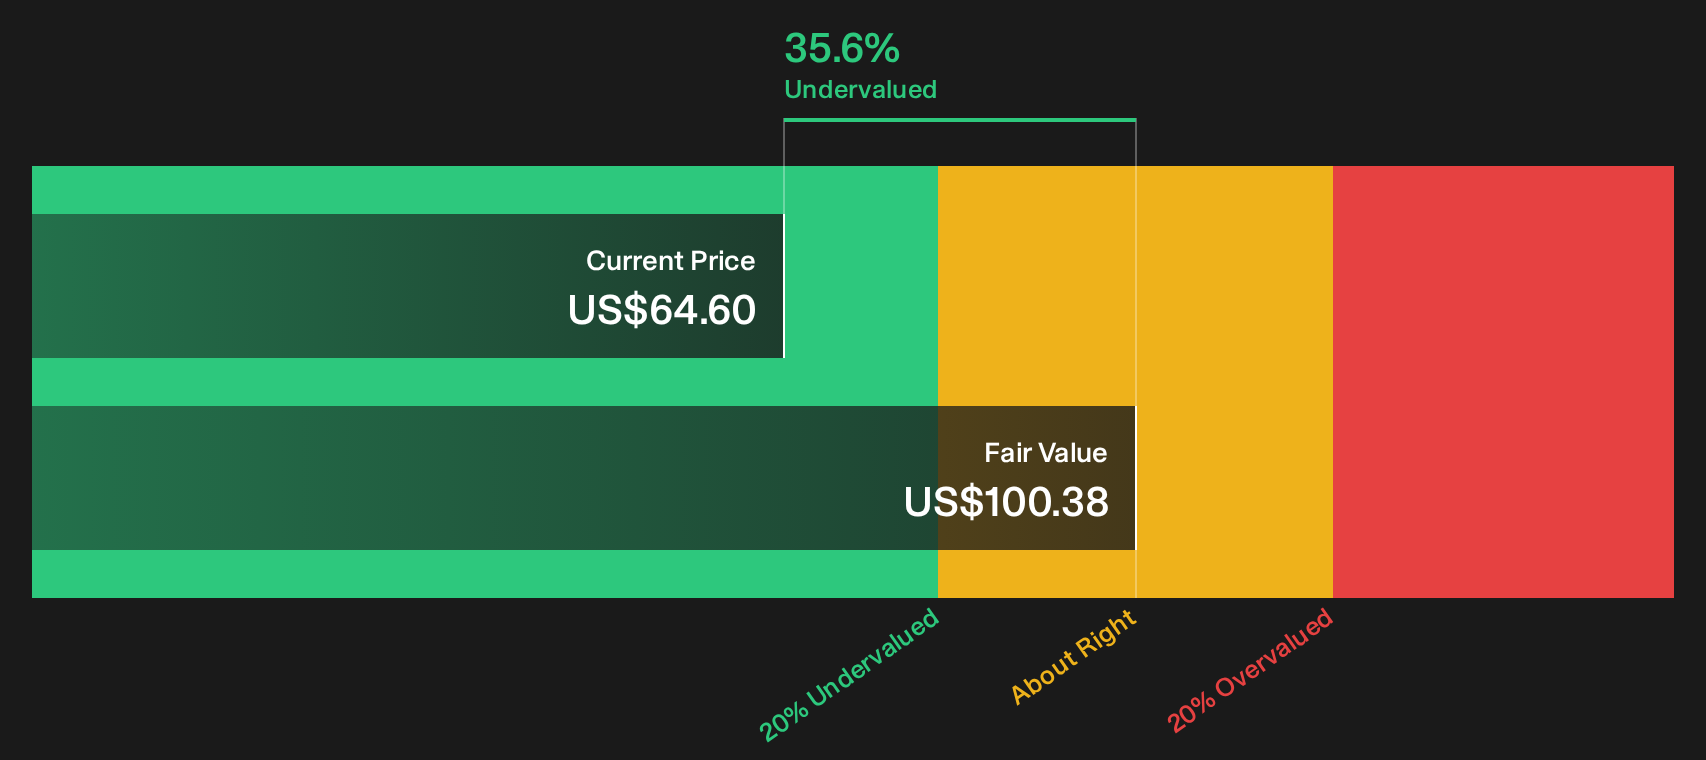
First Bancorp trades on a P/E of 16.4x while our DCF model points to a future cash flow value closer to $100.38 per share versus the last close at $64.60. That mix of a premium earnings multiple and a 35.6% discount to the SWS DCF estimate puts the Charlotte expansion story under a bright valuation spotlight.
The P/E ratio compares what investors are willing to pay today for each dollar of earnings. For a regional bank like First Bancorp, it often reflects expectations around loan growth, credit quality, and how sustainably management can turn deposits into profit over time.
FBNC is described as expensive on this yardstick compared with both direct peers at 11.9x and the broader US Banks group at 11.3x. It also screens as rich versus an estimated fair P/E of 13.3x that the fair ratio framework suggests the market could eventually lean toward if enthusiasm cools.
The tension is clear. On one side, FBNC is trading at 35.6% below the SWS DCF fair value estimate of $100.38, which is based on projected future cash flows discounted back to today. On the other side, the current 16.4x P/E already runs materially higher than peers, the wider industry, and the fair ratio level of 13.3x, which signals that the market is already paying up for that earnings profile.
Result: Price-to-earnings of 16.4x (OVERVALUED).
Explore the SWS fair ratio for First Bancorp.
Still, any slip in loan quality or a tougher funding backdrop could quickly flip First Bancorp’s premium P/E from a sign of confidence into a pressure point.
Find out about the key risks to this First Bancorp narrative.
Another view on First Bancorp’s value
Where the P/E workup paints First Bancorp as expensive, the SWS DCF model points in the opposite direction. On that lens, FBNC at $64.60 trades about 35.6% below an estimated future cash flow value of $100.38 per share. Which lens feels more convincing to you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around First Bancorp’s valuation can feel confusing. Move quickly to review the data, stress test your own assumptions, and weigh both sides of the story with the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond First Bancorp?
If First Bancorp has sharpened your focus on quality, broaden your watchlist now with other opportunities that share strong fundamentals and clear, data backed stories.
- Spot potential value plays early by scanning a curated set of quality companies that trade below their implied worth with the 39 high quality undervalued stocks.
- Build a portfolio aimed at resilience by focusing on income payers screened for yield strength and consistency using the 8 dividend fortresses.
- Reduce unpleasant surprises by concentrating on companies that score well on financial robustness with the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com