


EN
Wyndham Hotels & Resorts (WH) Expands Its Luxury Reach, Is The Upside Already Priced In?
Wyndham Hotels & Resorts (WH) is expanding its higher-end footprint by adding Vienna House by Wyndham in Istanbul and partnering with HotelREZ to bring more than 40 Elegant luxury hotels into its Registry Collection and Wyndham Rewards network.
Recent moves into higher-end and tech enabled partnerships are landing against a share price of US$77.35, with a 30 day share price return of 7.07% and a 1 year total shareholder return of 7.29%, indicating that momentum has picked up following a period of slower multi year total returns.
Spot similar momentum and loyalty driven stories beyond Wyndham Hotels & Resorts by scanning the hand picked 19 high quality undiscovered gems that combine expansion plans with solid fundamentals.Wyndham Hotels & Resorts now trades around US$77 compared with a higher set of fair value estimates, including a US$95.61 analyst target and a larger intrinsic gap. Is this recent momentum already pricing that in, or not yet?
Most Popular Narrative: 21% Undervalued
Against the last close of $77.35 for Wyndham Hotels & Resorts, the most followed narrative anchors on a fair value of about $97.59 that is built on a discounted cash flow framework using a 9.62% discount rate and analyst expectations for fee based earnings.
Record net room growth and a development pipeline of about 261,000 rooms with roughly a 30% FeePAR premium over the current system create ongoing mix uplift toward higher fee hotels. This can support faster growth in fee-related revenue and EBITDA for Wyndham Hotels & Resorts. Expansion of extended stay and upper midscale or upscale lifestyle brands such as ECHO Suites, Hawthorn, WaterWalk, Dolce, Dolce Nova, Registry and Trademark, which are forming a larger share of the pipeline, shifts the portfolio toward segments that typically support higher RevPAR and can raise royalty revenue and fee-based earnings over time.
See why 2 investors see Wyndham Hotels & Resorts as 21% undervalued.
Result: Fair Value of $97.59 (UNDERVALUED)
Still, legal and reputational fallout from the sex trafficking allegations or a prolonged soft patch in U.S. RevPAR could quickly challenge the Wyndham Hotels & Resorts upside case.
Find out about the key risks to this Wyndham Hotels & Resorts narrative.
Another View On Wyndham Hotels & Resorts
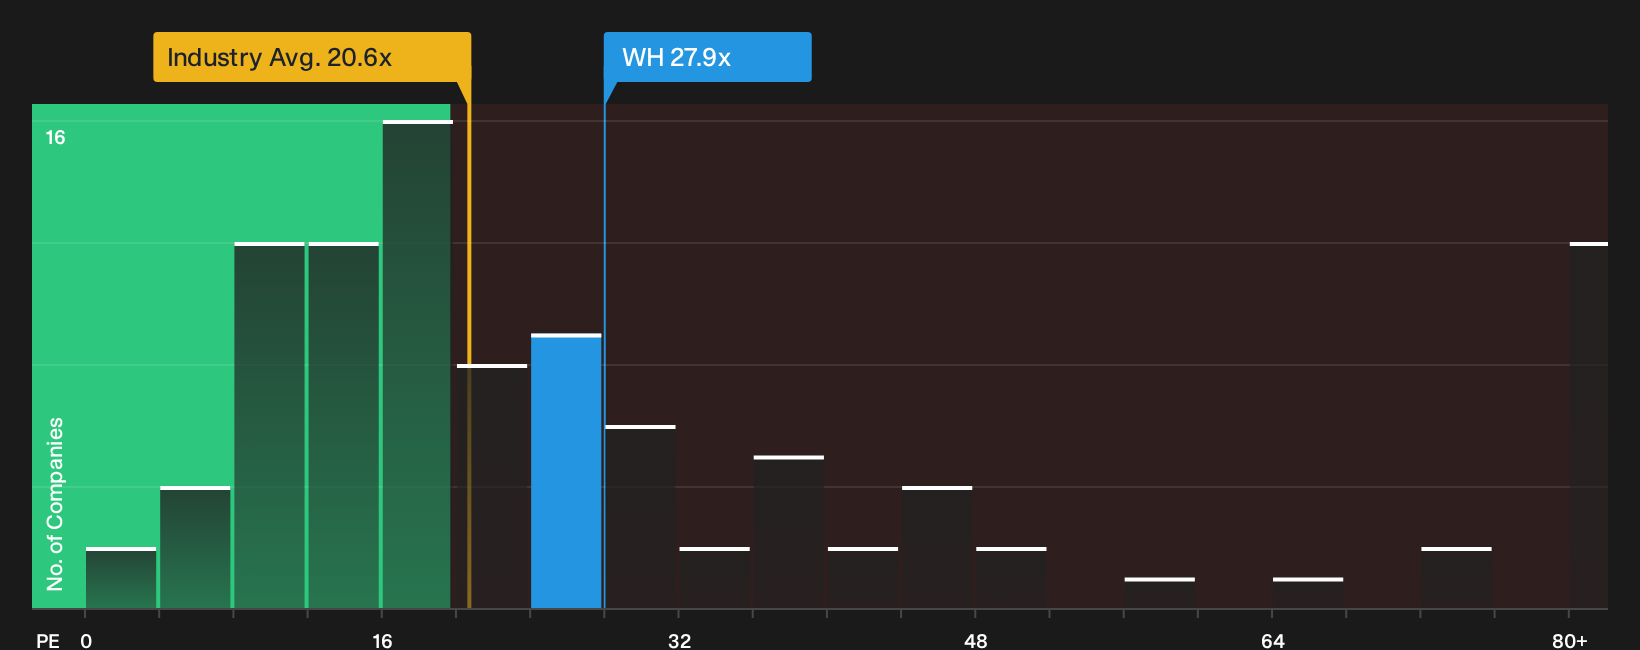
The story looks very different when switching from discounted cash flows to simple earnings multiples. Wyndham Hotels & Resorts trades on a P/E of 27.9x, which is higher than the US Hospitality industry at 20.8x and above its own fair ratio of 22.6x. That points to investors already paying a premium, so the question is whether the earnings path can justify that richer tag.
For a closer look at what this price premium implies for upside and downside, see the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Wyndham Hotels & Resorts leaves you undecided, consider acting promptly and evaluating the story against your own thresholds using the 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Wyndham Hotels & Resorts?
Do not stop with Wyndham Hotels & Resorts. Broaden your watchlist with focused stock ideas built from real fundamentals so you are not chasing headlines later.
- Target higher quality opportunities by scanning companies that look mispriced on fundamentals using the 39 high quality undervalued stocks.
- Prioritize resilience and focus on reviewing a 29 resilient stocks with low risk scores that screens for stronger balance sheets and lower risk scores.
- Stay ahead of the crowd by tracking a curated 19 high quality undiscovered gems that highlights under followed businesses with solid financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com