


EN
Does AI Board Hire Change The Bull Case For ManpowerGroup (MAN)?
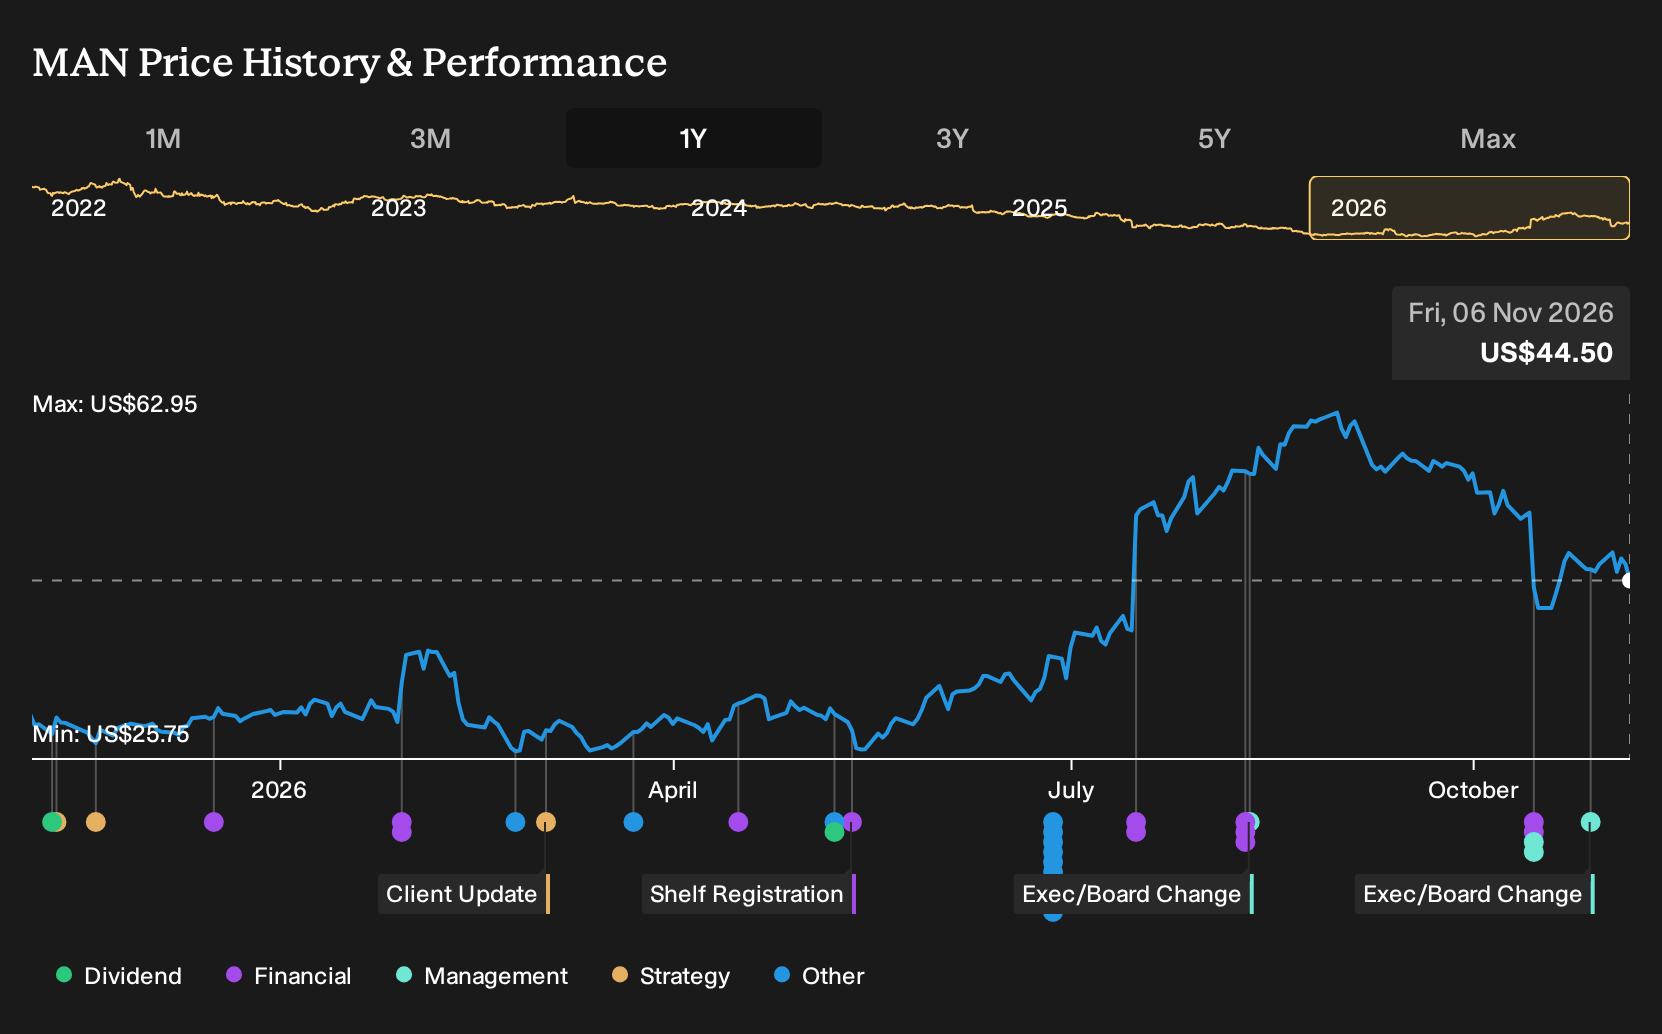
- ManpowerGroup has appointed Lidia Fonseca, former Executive Vice President and Chief Digital and Technology Officer at Pfizer, to its Board of Directors, with her election effective from 1 November 2026.
- Fonseca built Pfizer's enterprise AI program and led digital, data and technology strategy, which aligns closely with ManpowerGroup's ongoing focus on AI driven workforce solutions and process efficiency.
- This article considers how ManpowerGroup's investment narrative could be influenced by adding an enterprise scale AI leader to its board.
Scan how ManpowerGroup's AI focused board move compares with other companies preparing for similar shifts by tracking the hand picked 52 AI infrastructure stocks that is shaping the next phase of automation.
ManpowerGroup Investment Narrative Recap
To own ManpowerGroup, you need to believe its AI tools, Experis and Talent Solutions can steadily lift margins in a business that has seen flat longer term revenue and weaker earnings per share. The short term swing factor is how quickly the multi year US$200m cost program and AI platforms translate into cleaner EBITA margin progress.
The biggest risk remains pressure on gross profit, especially in staffing where mix and prior divestments already weigh, and where any further squeeze could offset efficiency gains. The Fonseca appointment looks directionally helpful for execution on AI and process work, but on its own it does not materially change near term risks.
The Fonseca board election ties most clearly to ManpowerGroup’s push around PowerSuite, Sophie AI and an AI driven sales engine that is already linked with about US$200m of incremental revenue. Her Pfizer track record in scaling enterprise AI and process excellence fits into the same operational problem set, from workflow automation to better sales targeting.
For investors, the question is whether that additional expertise improves the likelihood that AI and the US$200m cost program deliver the intended EBITA margin lift while avoiding fresh disruption. Execution still has to contend with staffing margin pressure, sensitive free cash flow and debt that is not well covered by operating cash flow.
What The Consensus Numbers Assume For ManpowerGroup
Analysts sketch a fairly specific arc for ManpowerGroup over the next few years, and it is worth testing whether that story feels realistic to you as a shareholder or potential investor. The projections lean heavily on AI driven productivity, a leaner cost base and a richer mix of higher value services, all of which the Fonseca appointment is meant to sharpen.
Revenue assumptions are clear. Forecasts build in 3.7% yearly top line growth over the next three years, which, if sustained out to 2029, feeds into projected sales of US$21.1b. That rate of expansion sits on top of a staffing and workforce solutions platform that has historically been more cyclical and volume driven, so the bet is that ManpowerGroup can rely more on differentiated services and AI supported offerings to support that pace.
Profitability expectations are even more explicit. Consensus modeling moves profit margins from 0.6% today to 1.8% in three years, effectively tripling margin on each dollar of revenue. That uplift leans on the planned US$200m cost savings program, the scaling of platforms like PowerSuite and Sophie AI, and a mix tilt toward Experis and Talent Solutions that is meant to carry richer economics than traditional staffing.
Earnings forecasts sit at the center of this. Analysts expect earnings to reach US$374.9m by around 2029, up from US$120.3m today, with the more cautious views closer to US$335.3m. That implies earnings a little over 3x current levels, which is a sizeable reset in profit power given the recent history of weaker earnings per share and softer return on invested capital.
Valuation mechanics in the consensus work off those 2029 numbers. To support the analyst price targets, the stock would need to trade on a P/E of 8.8x those forecast earnings, down from 17.3x today and also below the current 23.4x for the wider US Professional Services group. That setup suggests the scenario is not only about earnings growth but also about the market being willing to value ManpowerGroup on a lower multiple than sector peers in 2029.
ManpowerGroup's narrative projects US$21.1b revenue and US$374.9m earnings by 2029. This requires 3.7% yearly revenue growth and an earnings increase of about US$254.6m from US$120.3m today.
Assumptions around capital structure and risk round out the picture. Shares outstanding are modeled to expand by 1.3% per year for the next three years, which modestly dilutes per share metrics unless buybacks offset that issuance. The equity story also leans on a discount rate of 8.78%, in line with the Simply Wall St company report, to translate those future cash flows into today’s valuation anchor.
Price targets map these moving parts into a single number. Consensus sits at US$52.33, around 14.7% above the current US$44.64 share price, with a bullish camp up at US$65.00 and a cautious group closer to US$47.00. That spread highlights that even with detailed AI and cost roadmaps, there is still real disagreement about how much earnings power ManpowerGroup can sustainably achieve by the end of the decade.
For an investor reading this today in late 2026, the key task is not to accept or reject the analyst framework wholesale. The more practical step is to ask whether a move from 0.6% to 1.8% margins, around 3.7% annual revenue growth and a more than tripling in earnings feels consistent with your own view of what AI, cost cuts and mix change can reasonably deliver at a large, cyclical staffing and workforce solutions group like ManpowerGroup.
Uncover why ManpowerGroup's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses squarely on earnings pressure. The most cautious analysts were only modeling US$20.5b revenue and about US$328.9m earnings by 2029, which already bakes in softer permanent hiring. You now have ManpowerGroup adding an enterprise scale AI leader to the board, so those more downbeat assumptions may be revisited in time.
Explore 5 other ManpowerGroup fair value estimates, including one that suggests it could be worth just $45.19.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own research and judgment.
- A great starting point for your ManpowerGroup research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ManpowerGroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ManpowerGroup's overall financial health at a glance.
Looking For More ManpowerGroup-Sized Investment Ideas?
If the ManpowerGroup story has you rethinking how AI, balance sheets and dividends all fit into your portfolio, it can help to scan a wider opportunity set using the Simply Wall St Screener before making any moves.
- For investors who want potential mispricing with fundamentals front and center, start with a curated list of quality businesses on attractive valuations through the 39 high quality undervalued stocks.
- If capital preservation and steadier risk profiles matter most to you, focus on the 29 resilient stocks with low risk scores to see companies that score well on resilience and downside protection.
- For those who care about financial strength before anything else, filter for companies with robust balance sheets and solid fundamentals using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com