


EN
TowneBank (TOWN) Earnings Improved, Is The Stock Still Cheap?
TowneBank earnings spark fresh look at the stock
TowneBank (TOWN) just posted third quarter and year to date results that show higher net interest income, stronger net income and a sharp rise in net charge offs, giving investors fresh numbers to reassess the bank.
The new earnings are landing against a share price of US$36.39 that has climbed 4.03% on a 1 month share price return and 9.54% on a year to date share price return, yet eased over the past quarter as investors weigh the higher net charge offs. Over a longer stretch, TowneBank has delivered a 16.12% 1 year total shareholder return and a 64.48% 3 year total shareholder return, which points to momentum that has cooled recently but remains strong over multi year horizons as the market absorbs both stronger profitability and rising credit costs.
Compare how TowneBank stacks up against other regional banks being re-rated on earnings and credit trends using our curated list of list of solid balance sheet and fundamentals (24 results)
TowneBank now trades only modestly below both analyst targets and intrinsic value estimates after its recent run. Is the market already pricing the earnings strength and higher charge offs fairly, or is there still a discount worth unpacking?
Price-to-earnings of 9.3x: Is it justified?
TowneBank changes hands at a P/E of 9.3x, which sits below both peer averages and its own estimated fair level, even after the recent share price move to $36.39.
The P/E ratio compares what you pay today for each dollar of current earnings. For a regional bank like TowneBank, that yardstick helps you gauge how the market is weighing profitability, credit costs and the outlook for core lending against the rest of the sector.
On these numbers, the stock trades at a discount on several fronts. The P/E of 9.3x is lower than the peer average of 15.9x and also below the estimated fair P/E of 10.1x. This signals a level the valuation could reasonably shift toward if sentiment and fundamentals line up.
Against the wider US Banks industry, TowneBank again comes in cheaper, with its 9.3x P/E undercutting the sector average of 11.3x in a clear way.
Explore the SWS fair ratio for TowneBank.
Result: Price-to-earnings of 9.3x (UNDERVALUED)
Still, rising net charge offs and annual declines in both revenue and net income growth leave room for the TowneBank story to shift if credit quality tightens further.
Find out about the key risks to this TowneBank narrative.
Another view on TowneBank’s value
A second lens uses the SWS DCF model, which pegs TowneBank’s future cash flow value at $38.58. With the shares at $36.39, that points to roughly a 5.7% gap that tilts toward undervalued territory. Does that margin feel like a cushion or just a small buffer to you?
Look into how the SWS DCF model arrives at its fair value.
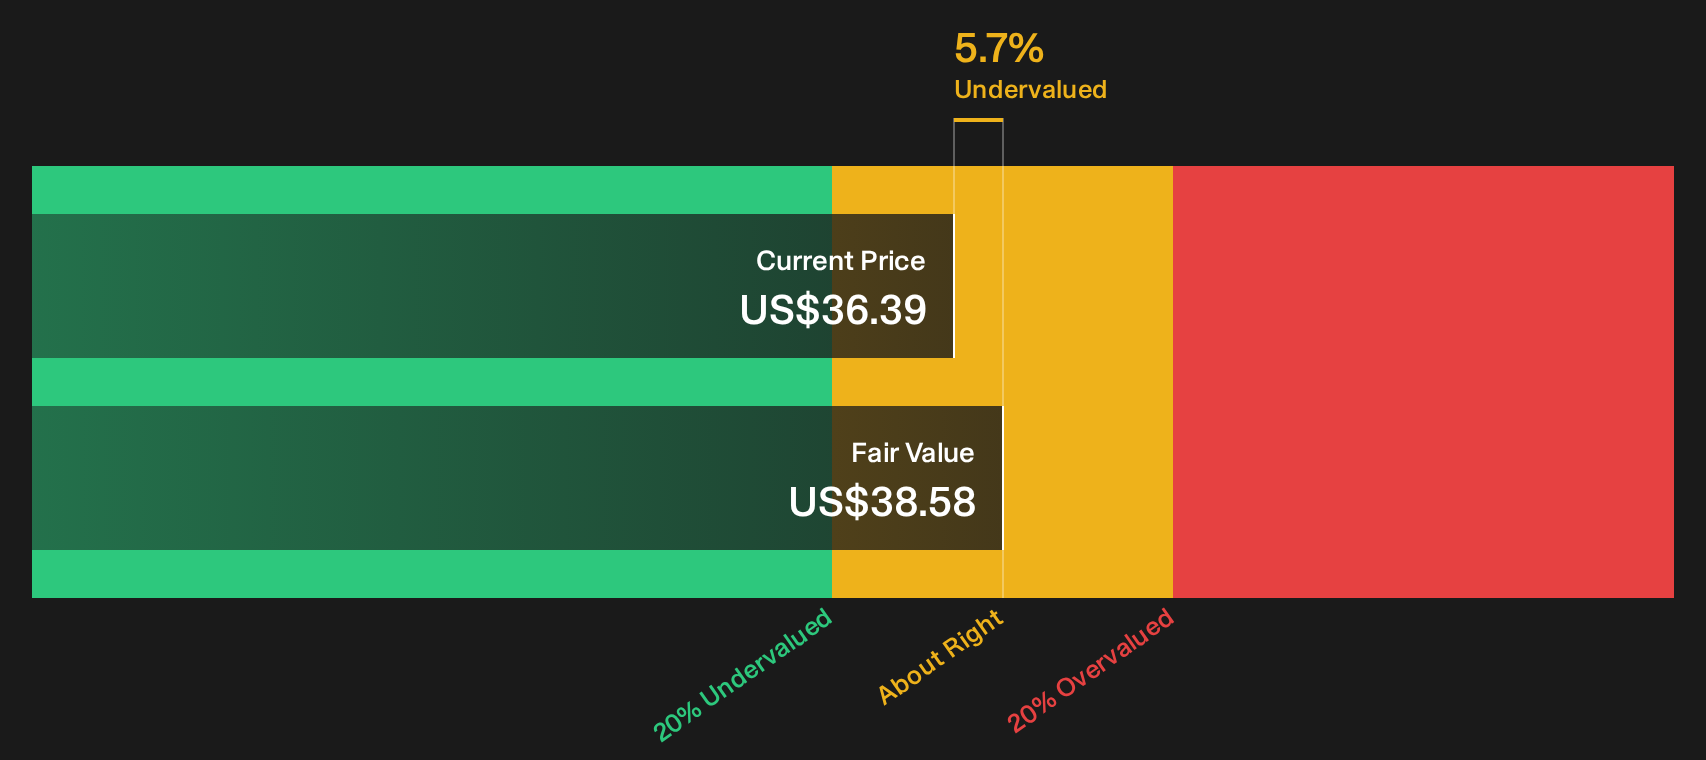
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TowneBank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around TowneBank often create more questions than answers, so use the fresh results and valuation work as a prompt to do your own homework quickly and weigh the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond TowneBank?
Do not stop at TowneBank. Use this earnings update as a springboard to refresh your watchlist with other opportunities lining up on valuation, balance sheets and income.
- Target resilient performers by scanning a 29 resilient stocks with low risk scores that filters for businesses with sturdier profiles when conditions get choppy.
- Hunt for mispriced opportunities by checking a 39 high quality undervalued stocks that blends quality fundamentals with discounted valuations.
- Build a cash flow stream by reviewing a 8 dividend fortresses that focuses on higher yielding payouts with supporting financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com