


EN
Why Does KLA (KLAC) Have A New A Credit Rating From S&P?
- KLA (NasdaqGS:KLAC) received an S&P Global Ratings upgrade to an A credit rating, reflecting a stronger operational profile.
- S&P cited KLA's balance sheet and exposure to AI chip demand as key reasons for the higher long term rating.
- The improved assessment may affect KLA's future financing terms as it invests alongside rising AI driven process control requirements.
- S&P's move to an A rating highlights only one aspect of how AI chip demand is reshaping KLA's position. We have also spotted 4 other big wins worth knowing about at KLA.
AI infrastructure is creating ripple effects across many hardware and tools suppliers, so it is worth comparing KLA with peers exposed to similar demand through 52 AI infrastructure stocks.
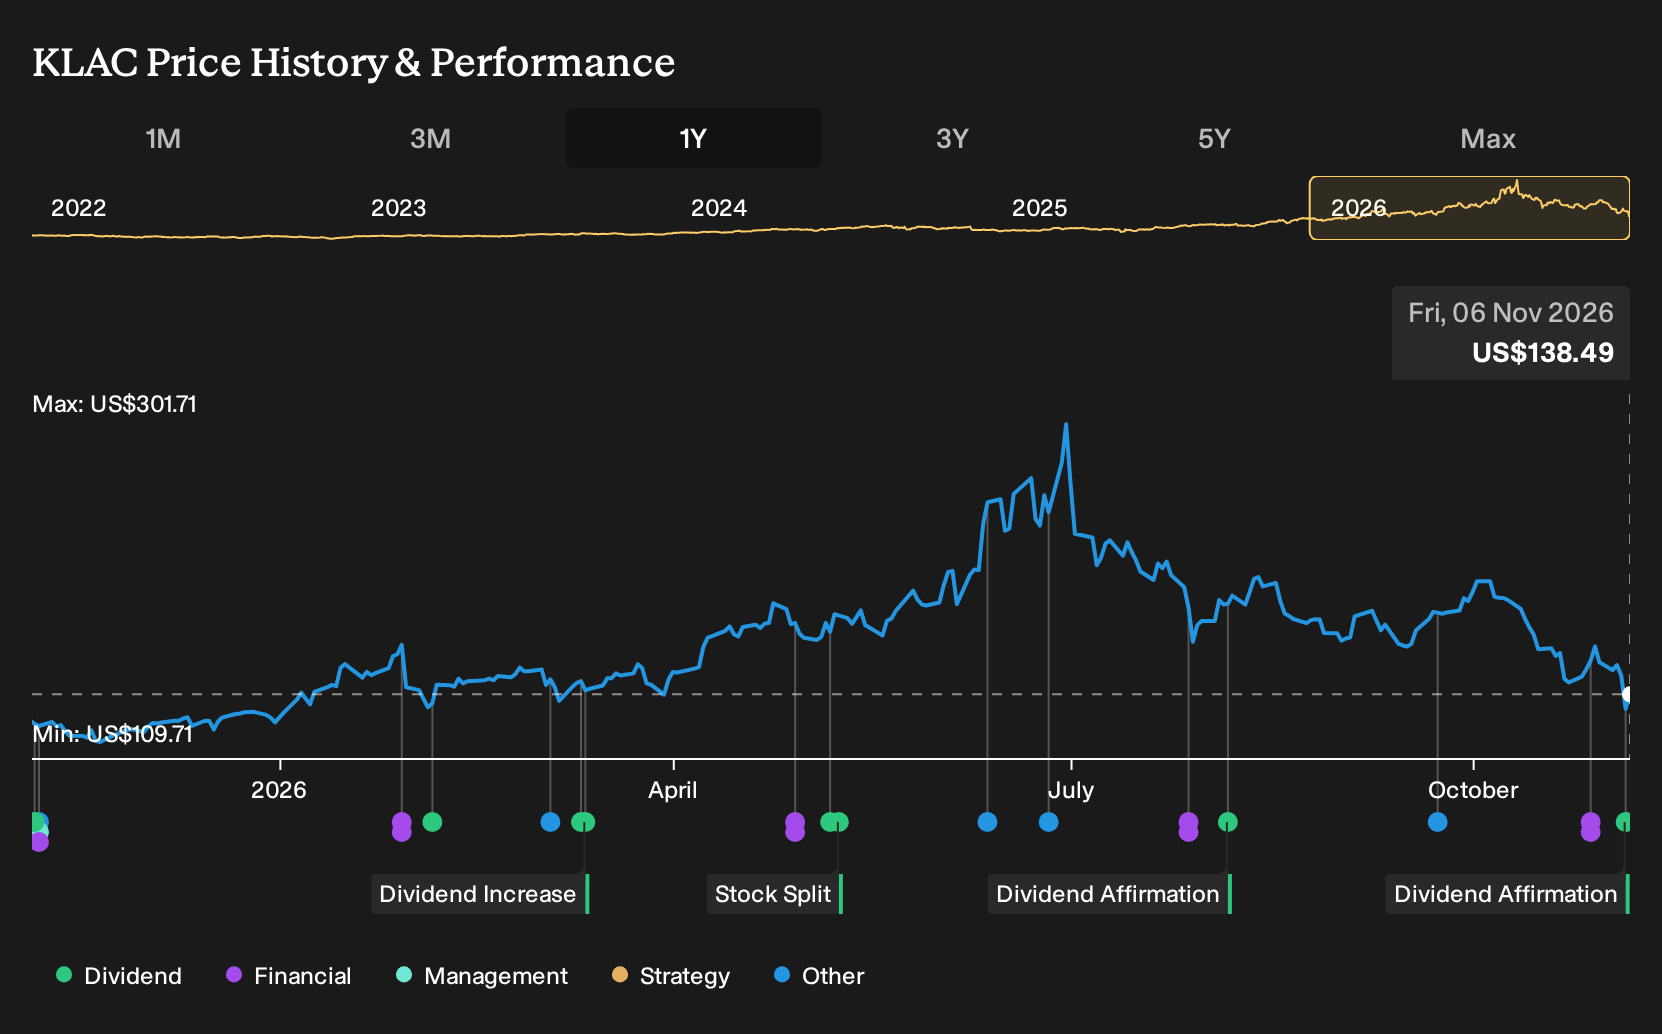
KLA operates in the semiconductor tools space, supplying process control and inspection equipment that chip manufacturers rely on to turn AI focused designs into physical wafers and packaged devices. As a result, its credit profile is closely tied to investment cycles across this manufacturing chain.
See which insiders are buying and selling KLA following this latest news.
KLA rating upgrade leans into the backlog story, while testing the margin risk
The central KLA Narrative says the AI driven equipment boom only works for shareholders if a long pipeline of committed orders turns into high margin process control and services revenue. S&P’s move to an A credit rating plugs directly into that premise because it speaks to balance sheet strength as that backlog is funded and delivered.
The main thing that has to go right is that KLA continues to convert its large, long dated backlog and process control share gains into high margin systems, services, and specialty process revenue...
See how the full story points towards a $225 fair value for KLA.
The higher rating supports the catalyst that matters most in the Narrative, which is a profitable, cash generative model funding AI focused tools over several years. Lower perceived credit risk can give KLA more flexibility when it commits capital to process control and advanced packaging projects, especially against peers like Applied Materials and Lam Research that are chasing similar AI related budgets.
The same news also puts a spotlight on the key risk analysts already flag, that tariffs and higher component costs could still compress gross margin even if financing looks comfortable. A stronger balance sheet does not cancel exposure to China restrictions or long dated order adjustments, so the reward side of the story still depends on how fully that US$12.5b backlog converts to cash and services mix.
For any investor, this rating change only really matters in the context of the KLA investment story that feels most credible, because the same signal can either reinforce or weaken your existing thesis about backlog quality and profitability.
Add KLA to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com