


EN
Earnings Pressure Might Change The Case For Investing In RH (RH)
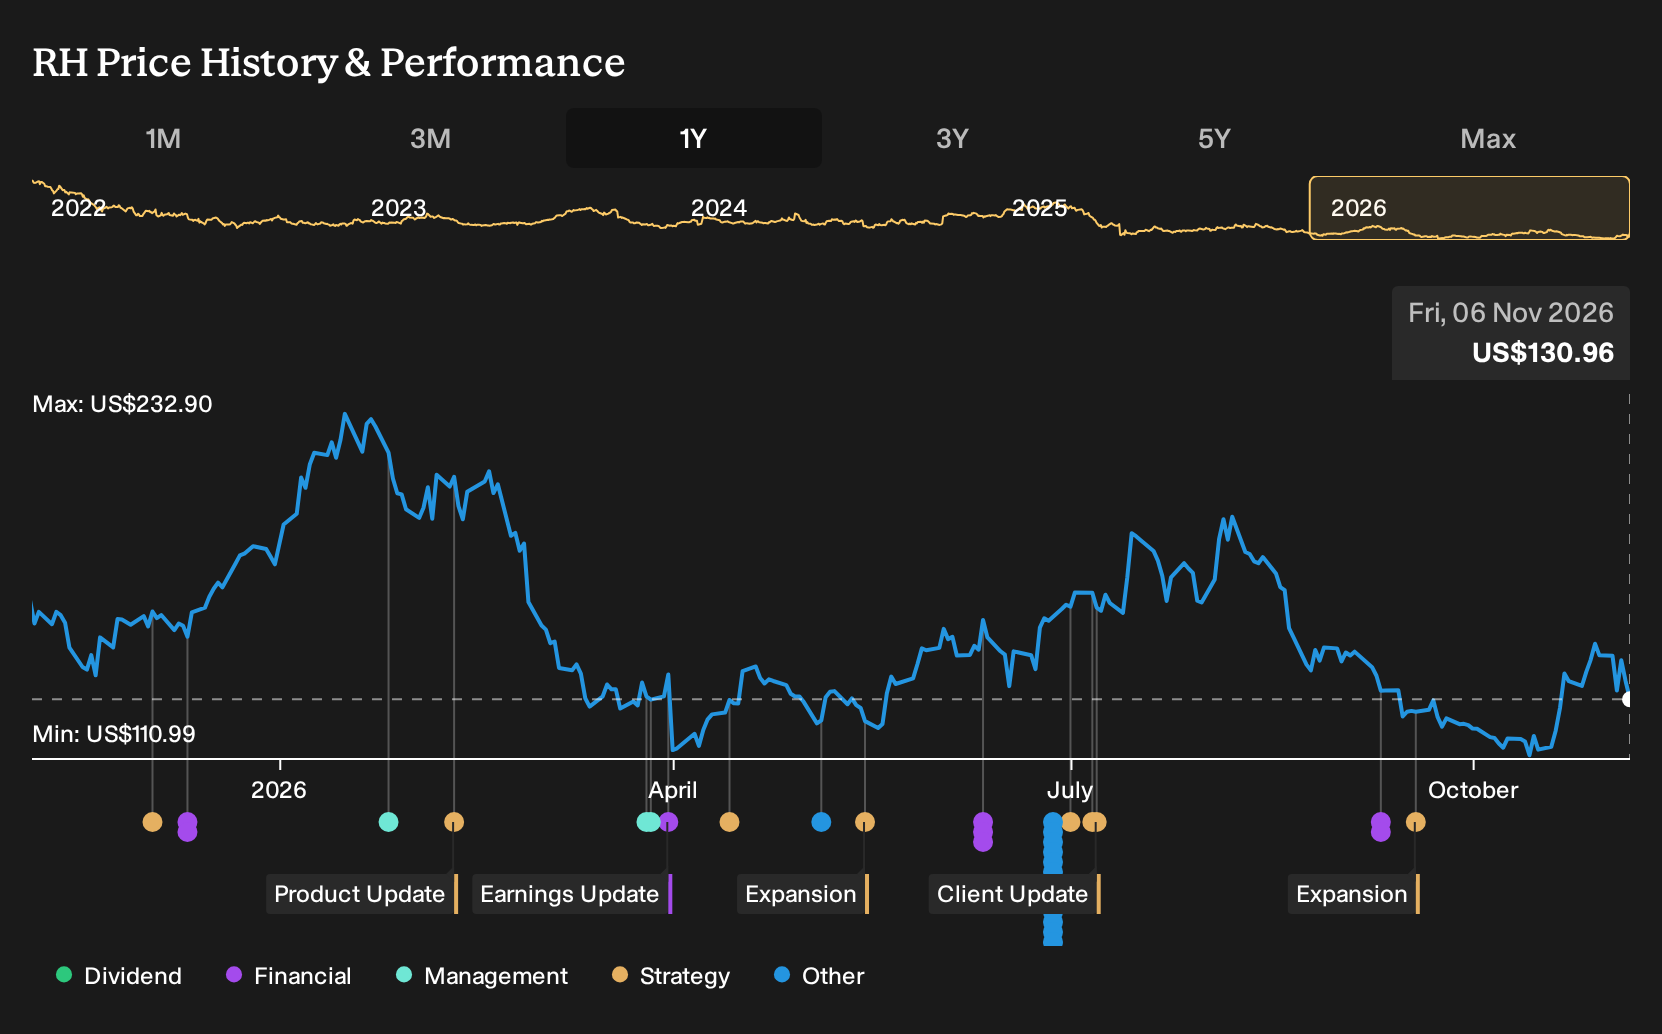
- RH recently saw its shares fall 5.16% in a single session, with investors focused on an upcoming earnings release where current projections point to a significantly lower EPS than the same quarter a year ago.
- The sharp expected EPS compression highlights pressure on RH’s profitability at a time when heavy spending on new galleries and concepts is still working through the income statement.
- We will now see how RH’s investment narrative around capital-heavy expansion and gallery productivity could be tested by mounting earnings caution.
Compare RH’s earnings pressure with other capital intensive retailers and see which ones are still pricing in resilience through the 39 high quality undervalued stocks.
RH Investment Narrative Recap
To own RH, you need to believe the heavy spend on European flagships, large galleries and RH Estates will convert into stronger gallery productivity and healthier free cash flow as capex and pre opening drag ease. The key near term catalyst is evidence that new and existing locations can support margins despite a softer housing backdrop.
The projected EPS drop and recent share pullback mainly sharpen the focus on execution rather than change that core thesis. The biggest current risk is that tariffs, inflation and weak high end housing keep pressuring demand and costs, making it harder for RH to cover interest and hit its EBITDA margin ambitions.
With no fresh operational announcements tied directly to this 5.16% move, the most relevant context is the earlier plan to move into a post peak investment phase. Management has guided for adjusted capex to step down and for international galleries to drag less on EBITDA margins as they mature.
For you, the next few quarters are about proof. RH needs to show that capital already deployed into galleries, RH Estates and European flagships can support revenue and margin progress without leaning on more heavy spending. Any sign that interest coverage is improving as cash generation builds would go straight to the heart of today’s risk debate.
RH's current analyst narrative points to forecast revenues of US$4.5b and earnings of US$308.5 million by 2029, based on an assumed 9.6% yearly revenue growth rate and an earnings increase of about US$197 million from US$111.5 million today.
Discover how RH's fair value indicates a 27% potential upside to its current price, which could narrow quickly if sentiment shifts back toward execution.
Exploring Other Perspectives
Some of the most optimistic analysts focus on RH’s real estate monetization as the swing factor. Before this 5.16% drop, the bullish narrative assumed revenues of about US$4.8b and earnings near US$317.8 million by 2029. That is far more hopeful than consensus, and these pre news forecasts may shift once the latest results land.
Explore 4 other RH fair value estimates, including one that suggests as much as 89% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RH research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for RH. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RH's overall financial health at a glance.
Looking For More Investment Ideas Beyond RH?
If the RH story has sharpened your questions about risk, resilience and balance sheets, it can help to compare it with other businesses facing very different conditions. Put the current debate in context by scanning a broader opportunity set before deciding where your next dollar goes.
- If you want potential upside with strict quality filters, start with a focused group of companies flagged as having resilient finances through the 19 high quality undiscovered gems.
- For readers who care most about capital preservation and steadier profiles, concentrate on businesses screened for lower overall risk using the 29 resilient stocks with low risk scores.
- Income focused investors who still want disciplined fundamentals can zero in on companies combining yield with staying power through the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com