


EN
Enovis Stock Earnings Beat Spurs New $200 Million Buyback Plan
- Enovis reported third quarter 2026 sales of US$558.73 million and a return to quarterly profitability, updated full year 2026 revenue guidance to a range of US$2.32 to US$2.35 billion, and outlined full year earnings expectations alongside a refreshed US$200 million share repurchase authorization.
- The swing from a very large prior year loss to a small profit, combined with continuing buyback capacity, highlights how Enovis is using improving operations and capital returns together to reshape its earnings profile.
- Next, the focus turns to how Enovis' raised earnings outlook and new buyback authorization could shift the existing investment narrative.
Compare Enovis' earnings reset and fresh buyback capacity with other potential opportunities by scanning our curated list of 39 high quality undervalued stocks that pair financial strength with mispriced expectations.
Enovis Investment Narrative Recap
To stay invested in Enovis, you need to be comfortable with a medtech story that leans heavily on orthopedic procedure demand, new joint and shoulder systems, and smoother execution on past acquisitions. The Q3 move back to a small profit and tighter 2026 revenue range suggests the operating reset is progressing, but not transformed. The key near term catalyst is continued margin improvement while integrating recent deals and managing tariffs. The main risk is that integration complexity and tech launch delays, such as in robotics and navigation, keep profitability patchy even if top line trends hold steady.
The narrowed 2026 revenue guidance to US$2.32 to US$2.35 billion does not radically change that equation. It refines expectations rather than reframing them. For you, the question is whether Enovis can sustain cleaner execution in Recon and Prevention and Recovery while funding R&D and MDR related spend without slipping back into larger losses. If operating leverage stalls or procedure volumes soften in reconstructive joints and extremities, the current earnings reset could look more fragile.
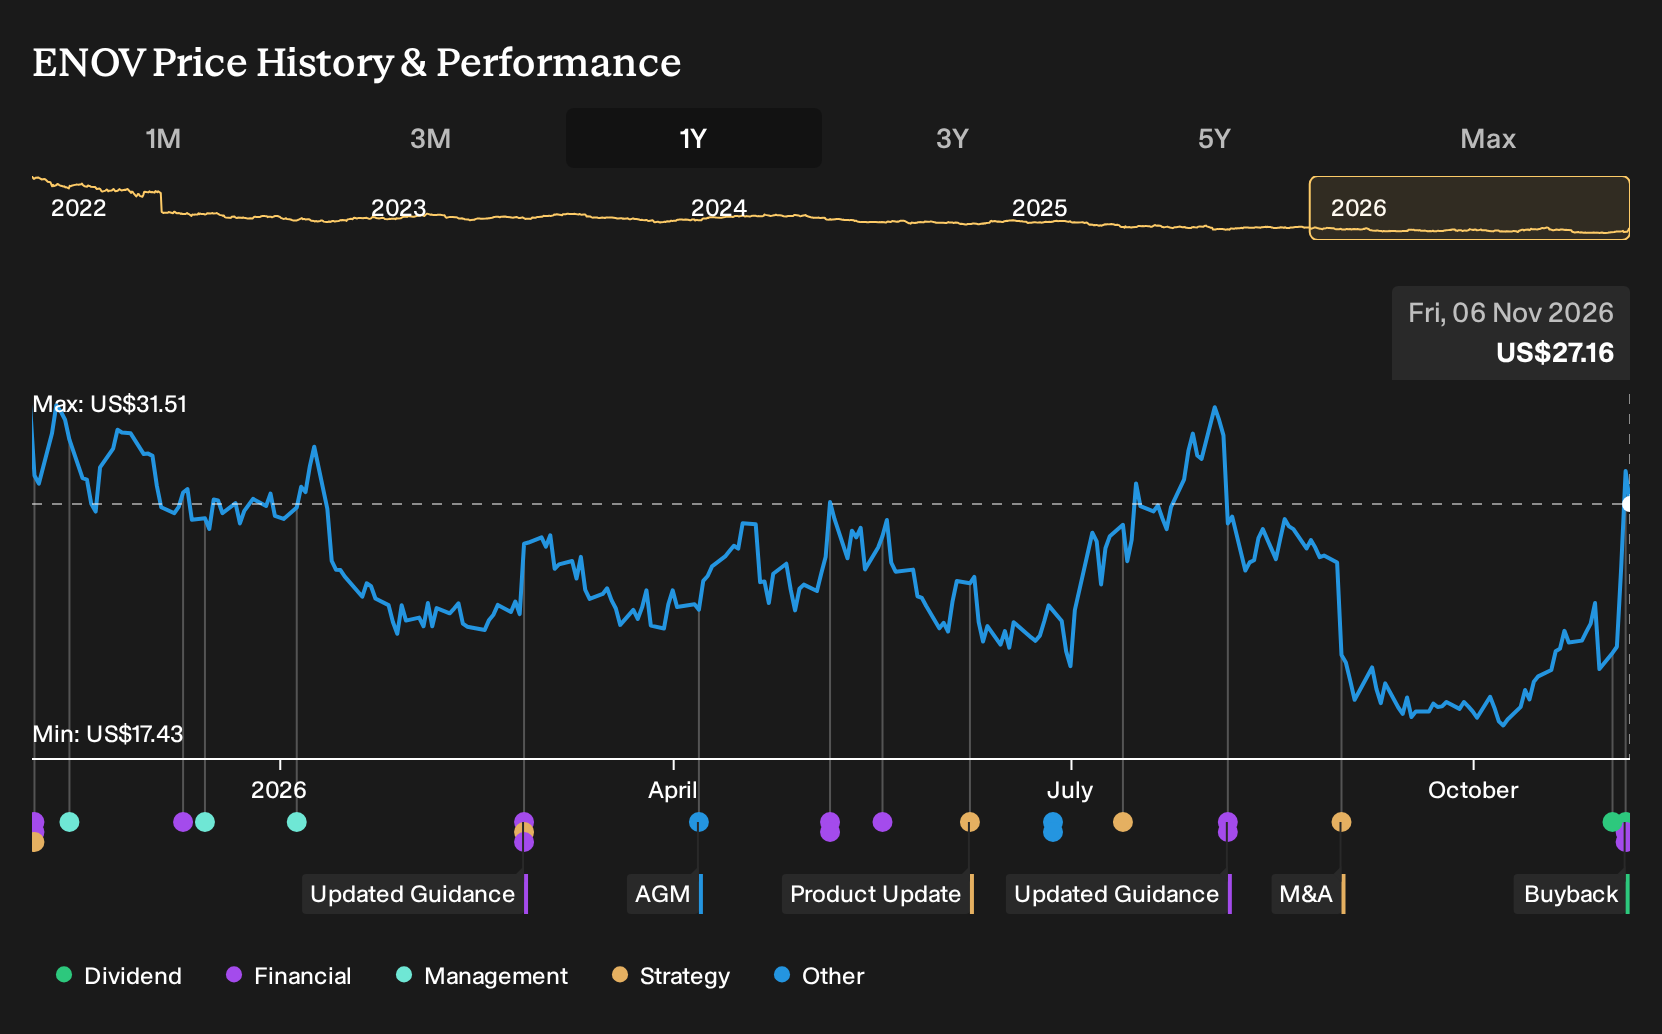
The new US$200 million share repurchase authorization is the announcement that ties most directly into the latest results. Management just completed a prior US$200 million program that retired 6,449,425 shares, or 15.84% of the equity, and is effectively resetting the capacity. Buybacks do not fix integration issues or launch delays, but they can matter for per share metrics if cash generation holds up. For a stock that has fallen 43.3% over three years and 69.6% over five years, the signal this sends about balance sheet flexibility will likely matter to many holders.
For catalysts, the focus stays on execution in high margin reconstructive products and the rollout of enabling technologies such as augmented reality navigation and future robotics offerings, all while absorbing Lima and other recent acquisitions. The repurchase plan sits in the background of that story. It can amplify the impact of any improvement in earnings and cash flow, but it also concentrates exposure to the core risks if orthopedic volumes soften, tariffs squeeze margins, or CapEx limits slow the pace of new product introductions.
Enovis' current analyst narrative points to revenues of US$2.7 billion and earnings of US$66.2 million by 2029, built on an assumed 5.0% yearly revenue growth rate and a shift from an earnings loss of US$1.1 billion today to that future profit level. This implies an earnings swing of about US$1.17 billion over the period.
Uncover why Enovis' fair value indicates a 41% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on tariffs rather than technology delays. The most bearish Enovis analysts were factoring in roughly US$4 million of quarterly tariffs and about US$10 million of war related inflation, and still only estimating around US$2.6 billion of revenue and US$323.2 million of earnings by 2029. That is a far harsher read than consensus and it has not yet incorporated this EPS guidance raise or the new US$200 million buyback plan. Use that spread in expectations as a reminder that reasonable people can disagree significantly, and consider exploring several scenarios before you decide how this latest update fits your own view.
Explore another Enovis fair value estimate, including one that suggests it could be worth just $38.33!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Enovis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Enovis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enovis' overall financial health at a glance.
Looking for more Enovis sized investment ideas?
If the Enovis story has you reassessing your watchlist, it can help to line it up against other companies with different risk and return profiles using the Simply Wall St Screener.
- Prefer potential mispricing backed by balance sheet strength and solid cash generation? Then compare Enovis against our 39 high quality undervalued stocks that share those traits.
- If resilience matters more than excitement right now, scan a 29 resilient stocks with low risk scores to see which companies screen well on stability and risk controls.
- For investors hunting for quality that the market may be overlooking, widen your search with a 19 high quality undiscovered gems that highlight strong fundamentals with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com