


EN
Can DTE Energy (DTE) Justify Its Valuation After Earnings And A Dividend Increase?
What DTE Energy’s latest quarter tells you
DTE Energy (DTE) just put fresh numbers on the board for the third quarter, with higher sales and earnings per share, and paired that update with a higher quarterly dividend for shareholders.
At a share price of US$135.08, DTE Energy has put in a 6.16% 1 month share price gain, while the 1 year total shareholder return of 2.18% and 3 year total shareholder return of 51.88% point to momentum that has built up over time, as investors weigh the recent earnings beat, the DTE Vantage sale agreement and new renewable projects alongside the higher dividend.
Scan regulated utility peers that show similar earnings resilience and grid investment stories with our curated list of 29 resilient stocks with low risk scores.
DTE Energy’s share price already reflects a stronger quarter, a bigger dividend and the DTE Vantage sale plan. The key tension now is whether most of the upside has been used up or if valuation still leaves room ahead.
Most Popular Narrative: 10% Undervalued
DTE Energy’s most followed valuation storyline pegs fair value around $149.39, compared with the recent $135.08 share price. The current quote reflects a discount that hinges on long term project execution and regulatory support.
Growing contracted and potential data center load, including 2.4 GW already under agreement and a further 5 to 6 GW in the large load pipeline, supports a long runway of new generation and storage projects that can add to regulated rate base and future revenue.
Roughly US$5b of planned investment through 2032 to meet Google’s 1 GW capacity needs, including renewables, storage, demand response, and longer term baseload assets, creates a visible project queue that can support earnings from capital deployed into regulated infrastructure.
See why 14 investors see DTE Energy as 10% undervalued.
Result: Fair Value of $149.39 (UNDERVALUED)
Still, severe storms that trigger long outages and regulatory penalties, or tighter approval of DTE Energy’s large capital plan, could quickly weaken that 10% undervalued narrative.
Find out about the key risks to this DTE Energy narrative.
Another View: What DTE Energy’s P/E Is Telling You
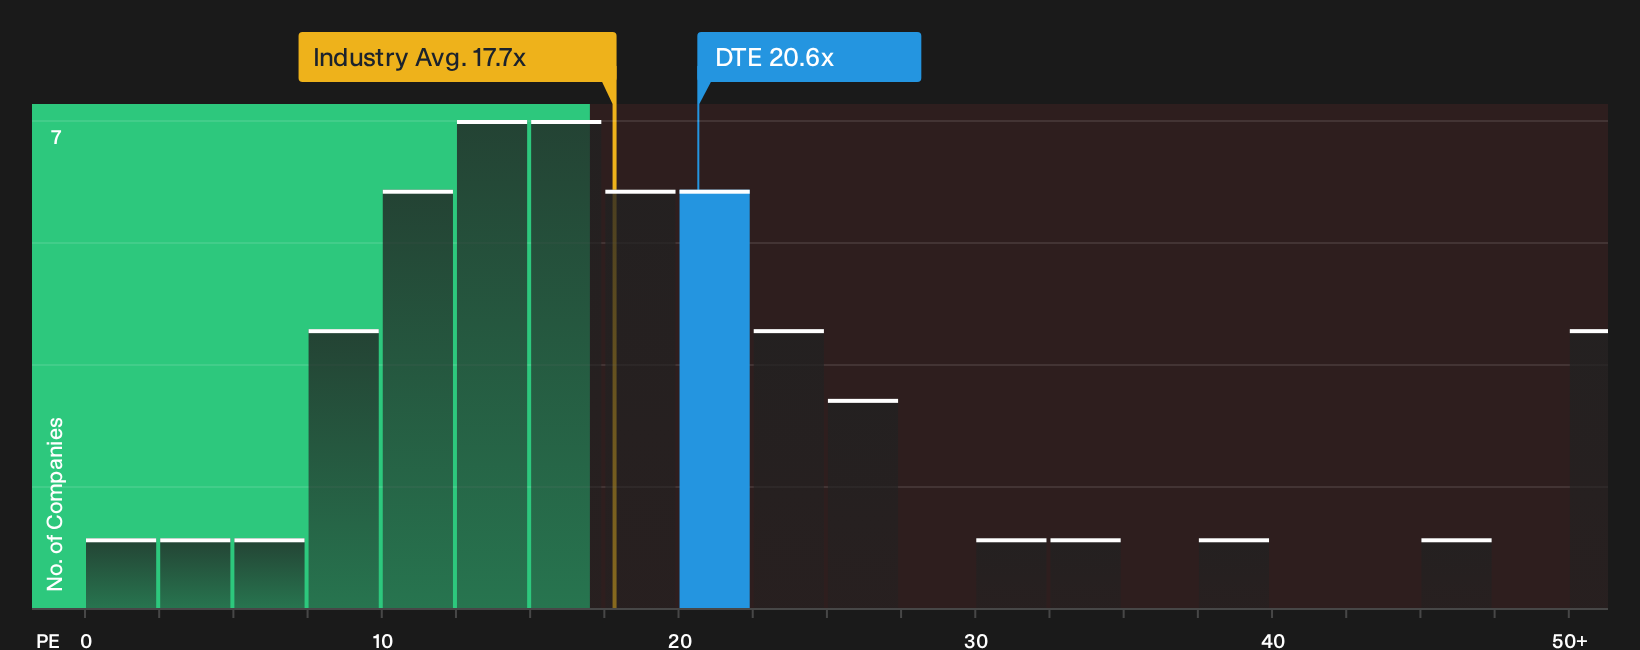
A different lens on DTE Energy comes from its P/E ratio. At 20.6x, the stock trades above the global Integrated Utilities average of 19x, yet below both the peer average of 22.6x and an estimated fair ratio of 22.8x. That mix of richer pricing than the sector but a discount to peers and the fair ratio leaves a simple question for you: Is this a premium you are comfortable paying for regulated growth tied to data centers and grid projects, or a sign to demand a wider margin of safety?
For a closer look at how this earnings multiple stacks up, including peers and the fair ratio the market could move towards, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around DTE Energy feels familiar, treat it as a prompt to move fast and pressure test the story yourself using 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond DTE Energy?
If DTE Energy has your attention, do not stop there. Broader opportunities are only a few clicks away and waiting too long could mean arriving late.
- Spot potential mispriced opportunities early and size them up through the 39 high quality undervalued stocks that filters for quality alongside pricing.
- Lock in income focused candidates by scanning the 8 dividend fortresses that zeroes in on higher yield payouts.
- Strengthen your watchlist with resilient businesses using the list of solid balance sheet and fundamentals (24 results) to filter for healthier finances and sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com