


EN
ATM Share Sale Plan May Change The Case For Investing In Cameco Stock
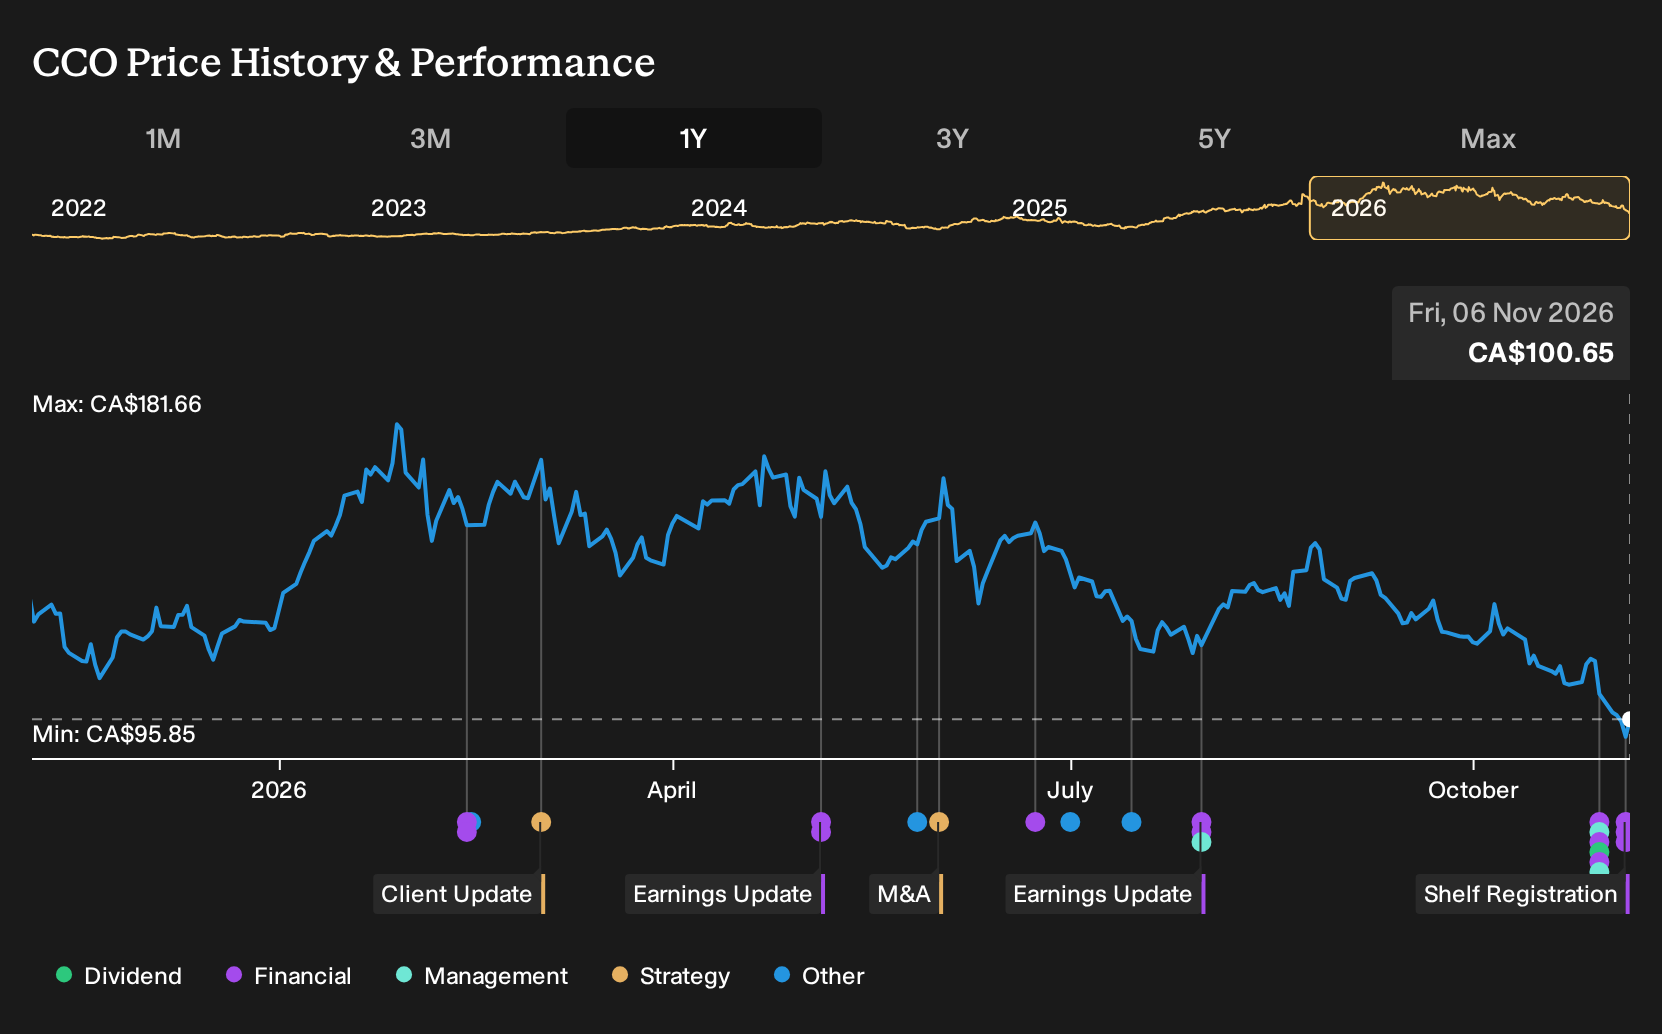
- Cameco renewed its at the market equity program, supported by a new US$1 billion follow-on filing and a US$3 billion universal shelf. Together, these filings expand its menu of common equity, preferred shares, debt, warrants and units for more flexible future financing.
- The additional equity capacity gives Cameco room to fund uranium and fuel development, potential acquisitions and debt repayment, without locking into a single funding route or fixed timing.
- We will look at how Cameco's investment narrative is affected by this renewed at the market equity capacity and the added balance sheet flexibility.
Scan how Cameco’s renewed equity firepower compares with other nuclear fuel and infrastructure plays by running your eye over our curated list of 17 nuclear energy infrastructure stocks in the same theme.
Cameco Investment Narrative Recap
To own Cameco, you need to believe that uranium and nuclear fuel demand stay resilient while the firm keeps its northern Saskatchewan assets running reliably and cost pressures contained. The latest quarter showed net income of CA$42.72 million, with nine month earnings below the prior year, so execution on production and costs remains front of mind for the short term thesis.
The renewed US$1 billion at the market program and US$3 billion shelf do not change the core operational story. They mainly affect how Cameco could fund future projects or manage the balance sheet. The biggest near term swing factor still appears tied to uranium production and delivery timing, with operational disruptions and cost inflation as the key risk.
The narrowed 2026 production and sales guidance is the announcement that lines up most closely with this fresh equity capacity. Cameco now expects its share of U3O8 output at 19.5 to 20.5 million pounds and uranium sales at 29.5 to 30.5 million pounds. This signals tighter planning around what it thinks can realistically be produced and shipped this year.
For you as a shareholder or prospective investor, that updated guidance frames how any future equity usage from the shelf or the at the market program might intersect with real world projects and commitments. Execution against these production and delivery ranges is likely to influence confidence in Cameco’s ability to support long term contracts, absorb input cost pressure and keep using its integrated uranium, fuel services and Westinghouse platform effectively.
Cameco's current narrative centers on analysts expecting revenue growth of 13.5% per year, with earnings today at CA$397.8 million and a consensus forecast of CA$2.1 billion by 2029. That shift implies earnings would need to rise by about CA$1.7 billion over the period for revenues to reach CA$5.1 billion in 2029.
Uncover how Cameco's fair value indicates a 73% potential upside to its current price, highlighting a price gap that some investors consider significant.
Exploring Other Perspectives
You also have a very different take available. The lowest Cameco analysts lean hard into the risk that production growth stays muted because management refuses to push mines without richer long term contracts. They were modelling revenue of about CA$4.1b and earnings near CA$1.5b by 2029, which is far more cautious than the consensus path. These views were all set before the fresh US$1b at the market program and US$3b shelf, so there is a real chance those forecasts and storylines evolve from here.
Explore 3 other Cameco fair value estimates, including one that suggests it could be worth just CA$142.69!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cameco research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cameco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cameco's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cameco?
Once you have a handle on Cameco, it often helps to compare it with other opportunities that line up with your goals on risk, income and balance sheet strength.
- If resilience matters most to you, scan for companies with steadier profiles using our 9 resilient stocks with low risk scores and see which ones match your comfort level.
- For investors hunting for quality at a reasonable price, check out a curated 6 high quality undervalued stocks that pair solid fundamentals with discounted valuations.
- If you care about financial strength first and return potential second, start with a list of solid balance sheet and fundamentals (5 results) and work from that shortlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com