


EN
Will Satellite To Cell Handoff Change Nokia's (HLSE:NOKIA) Narrative
- Nokia Oyj supported AT&T and AST SpaceMobile in what AT&T calls the industry’s first handoff between terrestrial cellular and direct to device satellite networks, while L&T Technology Services announced a five year R&D support contract that includes a dedicated offshore development center in India.
- Together, the satellite handoff milestone and expanded R&D capacity underline Nokia’s push deeper into hybrid connectivity, AI driven telecom software, and long term engineering partnerships.
- We will now look at how Nokia’s role in the AT&T satellite handoff could influence the existing investment narrative around AI networks.
Scan beyond Nokia Oyj and look for other telecom and AI infrastructure plays that could be setting up for the next leg of this theme with the 52 AI infrastructure stocks.
Nokia Oyj Investment Narrative Recap
To stay invested in Nokia Oyj, you need to believe the telecom equipment and AI network thesis still has room to run, even with a rich P/E multiple and volatile earnings. The short term swing factor is execution in Network Infrastructure, converting a growing AI and cloud order book into shipped optical and IP hardware despite 12 to 18 month component lead times.
The biggest risk right now is that supply bottlenecks and free cash flow pressure limit how quickly Nokia can turn that demand into cash and margin. The AT&T satellite handoff is helpful for the story but does not materially change those execution and balance sheet constraints in the near term.
The L&T Technology Services five year R&D deal looks most relevant to the AT&T and AST SpaceMobile milestone. Nokia is effectively adding an Offshore Development Center that can focus on 5G, AI driven operations and next generation compute, which are the same domains investors are watching around AI RAN and cloud networking catalysts.
If this R&D capacity translates into faster product engineering and software development, it could help Nokia deliver on AI and cloud driven opportunities while managing its restructuring program. The key watchpoints stay the same for you: whether execution on this partnership supports margins and delivery, and whether heavy reliance on hyperscalers and AI customers continues without a pause in spending.
How Nokia Oyj’s AI Network Story Meets The Numbers
Nokia Oyj's forecast narrative points to €24.1 billion of revenue and €2.7 billion of earnings by 2029, built on analysts’ assumption of 5.7% yearly revenue growth and an earnings increase of about 3.8x from €702.0 million today.
Uncover why Nokia Oyj's fair value indicates a 54% potential upside to its current price before momentum around Nokia Oyj’s AI network story shifts.
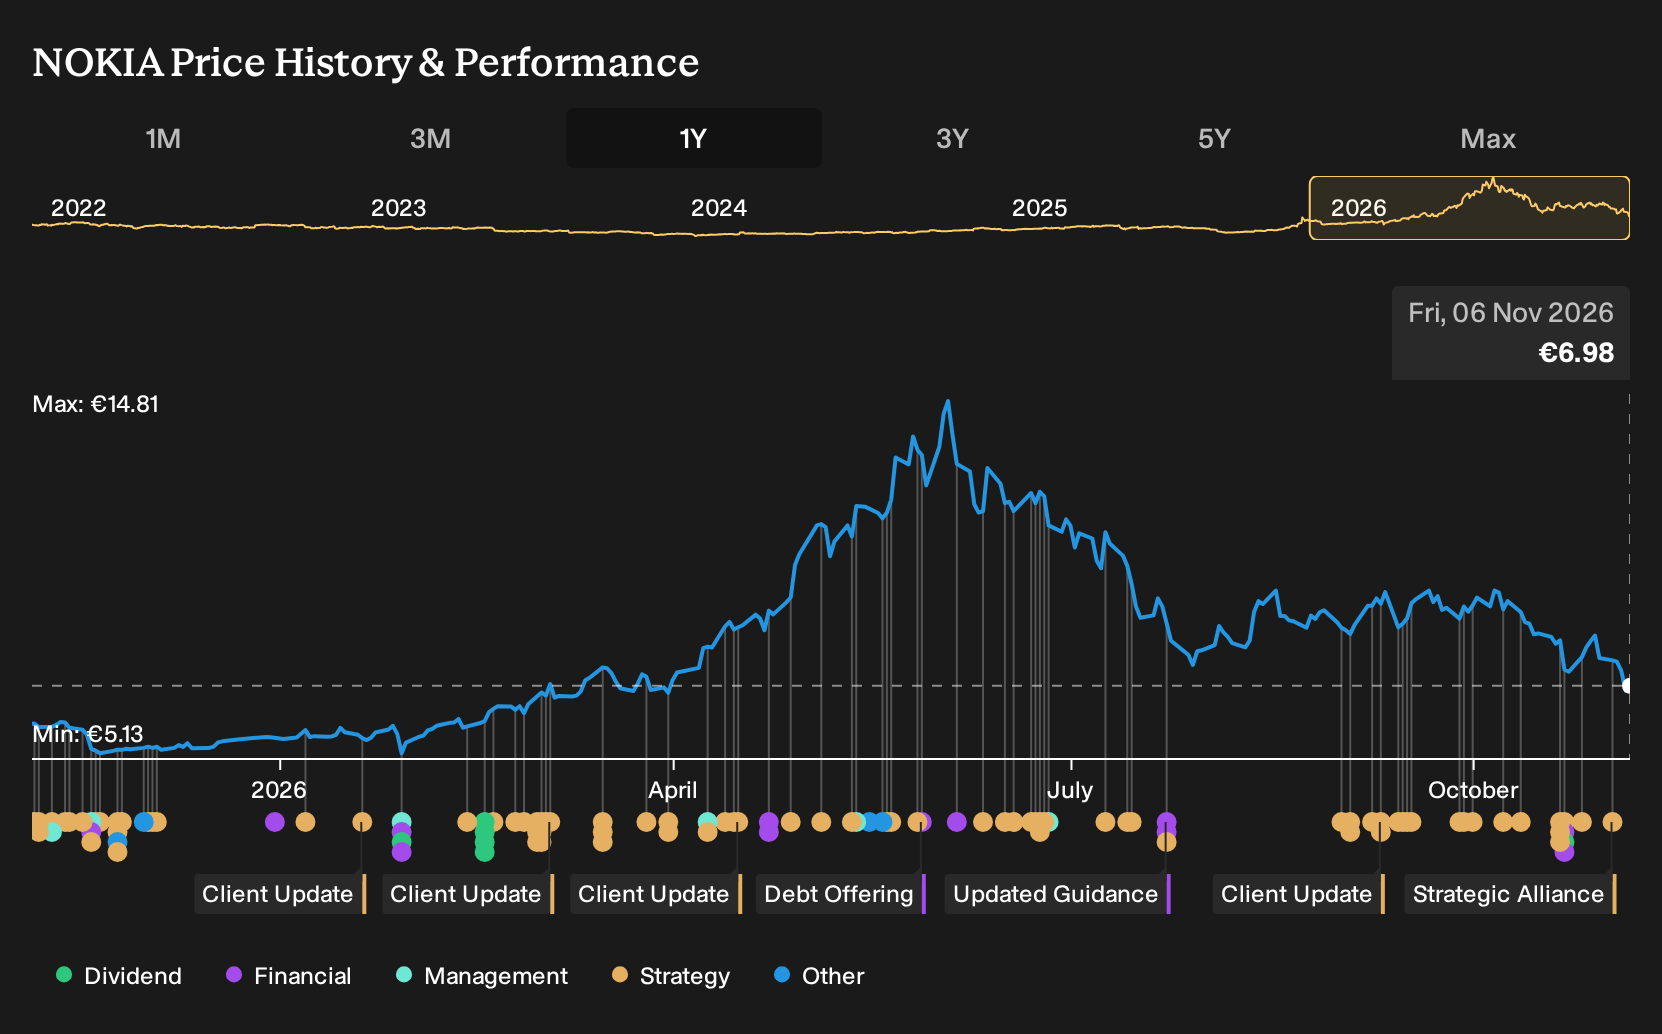
Exploring Other Perspectives
Some of the most optimistic analysts cling to a single catalyst that contrasts with the supply chain worries: Nokia Oyj’s push toward AI heavy software and AI RAN. Before this satellite handoff, the bullish camp was already modeling revenue reaching €27.2b and earnings of €3.7b by 2029, so these views may shift as the satellite story evolves.
Explore 4 other Nokia Oyj fair value estimates, including one that suggests as much as 137% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nokia Oyj research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nokia Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nokia Oyj's overall financial health at a glance.
Looking For More Ideas Beyond Nokia Oyj?
If you want to balance your Nokia Oyj view with fresh ideas, broaden your watchlist using screeners that focus on different strengths such as value, income, or balance sheet resilience.
- For investors who want quality at a potentially attractive entry point, scan for companies flagged in the 224 high quality undervalued stocks.
- If dependable income is a priority, check out stocks highlighted as 232 dividend fortresses to see which payouts might fit your goals.
- For a focus on financial resilience, start with a list of solid balance sheet and fundamentals (193 results) and see which businesses keep their foundations tight when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com