


EN
Intertek Group (LSE:ITRK) Could Be 15% Undervalued As Investors Weigh Separation Plans
Intertek Group (LSE:ITRK) has come under the spotlight after several institutional investors, including Natixis SA and Balyasny Asset Management, disclosed sizeable positions in the business through cash-settled derivatives under the UK Takeover Code.
After a strong run over 2026, with the share price up 30.54% year to date and a 1 year total shareholder return of 22.39%, Intertek Group now trades at £59.45. That momentum aligns with a solid 69.16% total shareholder return over three years, while more recent single day moves around the latest institutional disclosures hint at investors reassessing both upside potential and deal related risk.
Capitalize on the institutional interest in Intertek Group by scanning a curated 15 high quality undervalued stocks that share strong cash generation and balance sheet support.Intertek Group now trades almost exactly in line with the average analyst target, yet a 15% intrinsic value discount still sits on the table. Is the market being careful for good reason, or is it simply too cautious?
Most Popular Narrative: 1% Overvalued
The most followed narrative currently pegs Intertek Group’s fair value at £58.97, which sits just below the latest £59.45 close. That tiny gap leaves the story hinging less on headline valuation and more on how the business reshapes itself over the next few years.
The planned separation of Intertek Testing and Assurance and Intertek Energy and Infrastructure into two specialist ATIC businesses, targeted for completion by mid 2027, is intended to create greater strategic focus and simpler decision making that can reinforce organic revenue growth and support group margins and earnings.
The sharper capital allocation that management expects from running two focused entities, each with its own end markets and investment priorities, is designed to direct more spending into higher growth and higher margin segments, which can support operating margin and earnings quality.
See why 40 investors see Intertek Group as 1% overvalued.
Result: Fair Value of £58.97 (ABOUT RIGHT)
Still, the Intertek Group story can change fast if separation costs or integration issues bite harder than planned, or if Transportation Technology weakness drags on earnings.
Find out about the key risks to this Intertek Group narrative.
Another View: Intertek Group Through A Cash Flow Lens
Analysts see Intertek Group as roughly fairly priced at around £59 based on earnings forecasts, yet Simply Wall St's DCF model paints a different picture. On that cash flow view, the shares trade about 15% below an intrinsic value estimate of £69.99. Which yardstick do you trust more for a long term decision?
Look into how the SWS DCF model arrives at its fair value.
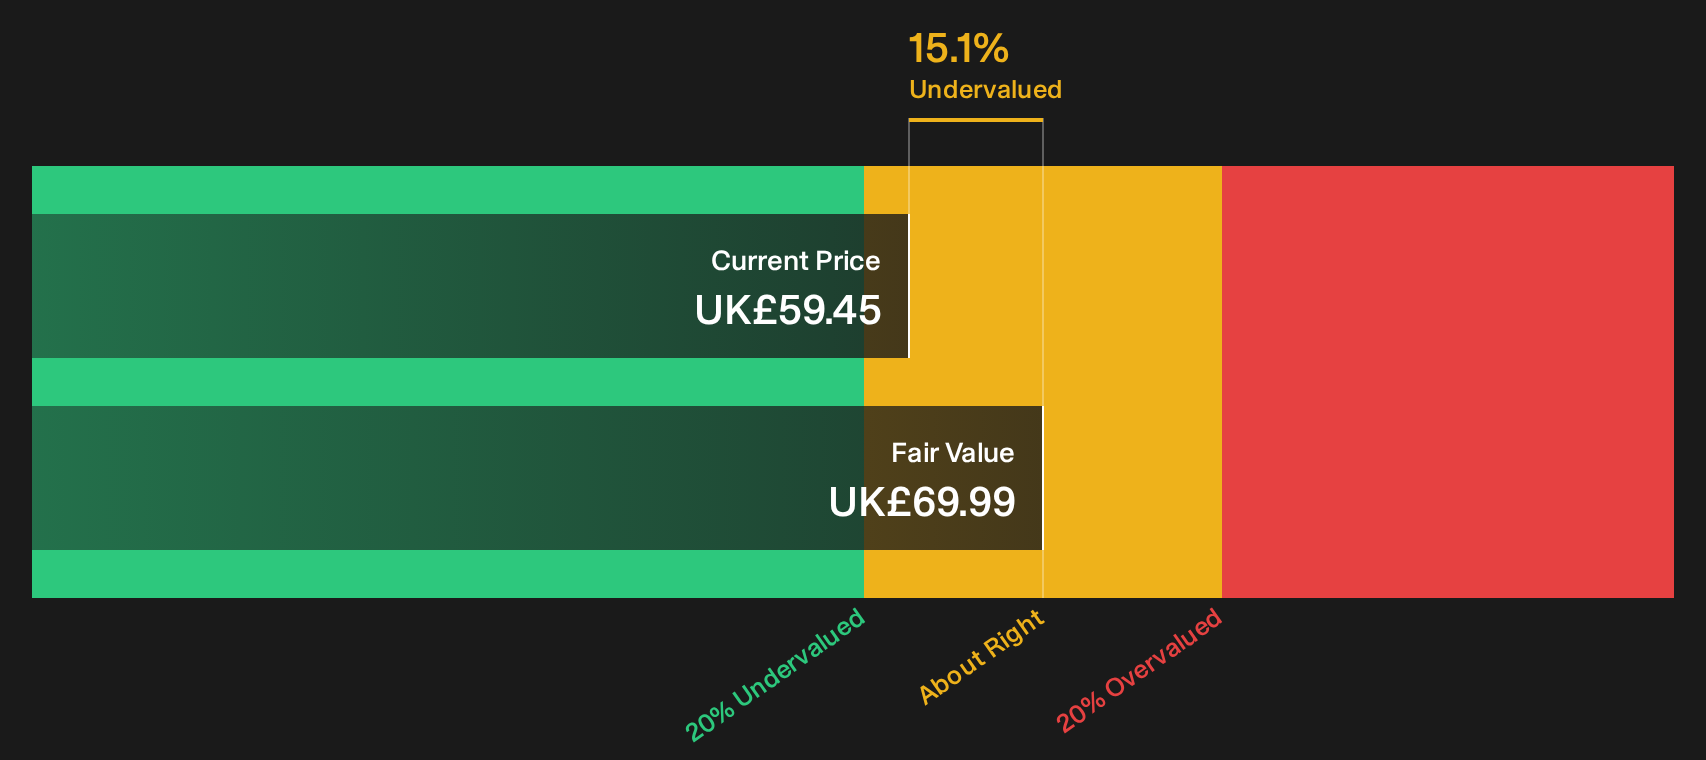
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Intertek Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Intertek Group so far. If you want to move quickly and build your own view using the full picture, review the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Intertek Group?
If you stop at Intertek Group, you risk missing other opportunities that match your style. Consider broadening your watchlist with a few targeted screens:
- Target reliable income and focus your research on companies with generous payouts by reviewing the 4 dividend fortresses.
- Hunt for quality at a discount and see which businesses combine strong fundamentals with appealing prices through the 5 high quality undiscovered gems.
- Reduce portfolio stress and concentrate on financially resilient businesses using the 4 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com