


EN
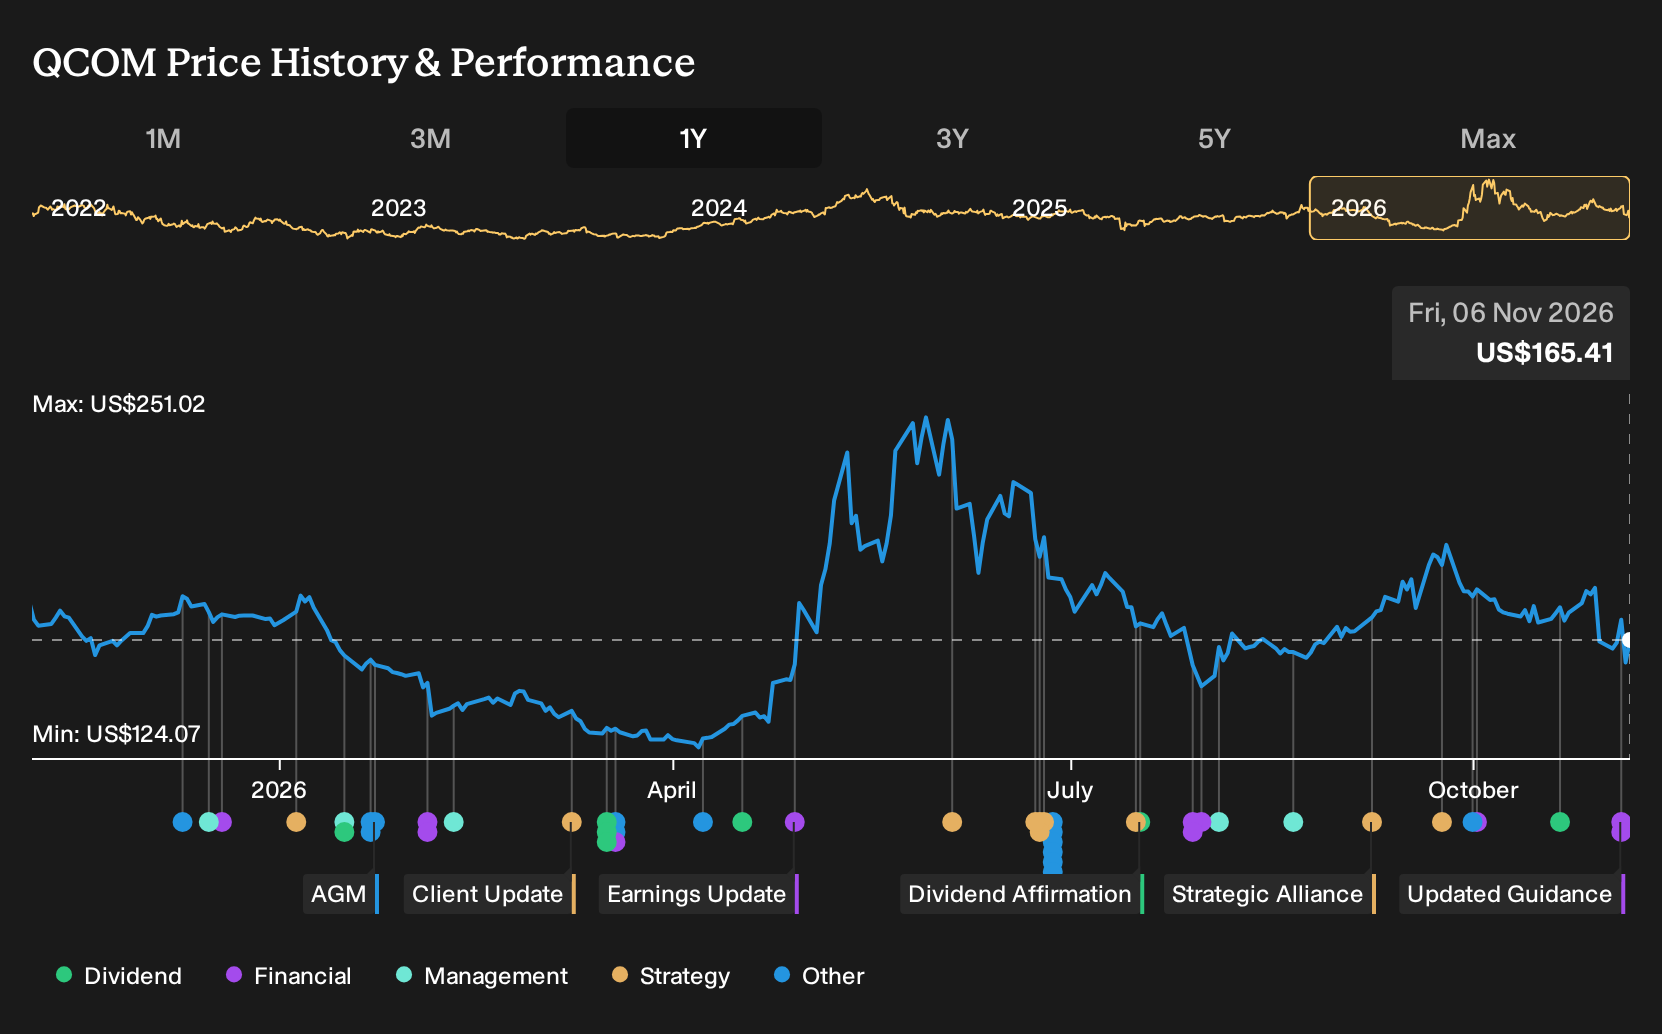
Qualcomm Stock Slides After Handset Sales Drop Raises Margin Pressure Questions
- Qualcomm reported Q4 2026 and full year results with handset chip revenue down 26% and issued Q1 FY27 revenue guidance of US$10.4b to US$11.2b, highlighting weaker smartphone demand and ongoing cost pressure despite growth in automotive, IoT and data center activities.
- The business is leaning harder on newer engines such as automotive, custom AI data center programs and long term 5G infrastructure agreements with SpaceX. However, these segments are still in ramp mode and have not fully offset the handset driven squeeze on chip segment margins.
- The focus now turns to what this Qualcomm earnings reset and handset driven margin pressure could mean for the existing investment narrative.
Compare how QUALCOMM's earnings reset stacks up against peers by reviewing 52 AI infrastructure stocks that are also exposed to AI data centers and chip supply chain pressures.
QUALCOMM Investment Narrative Recap
To stay comfortable owning QUALCOMM, you need to believe the handset slump is a manageable reset while non handset lines such as automotive, IoT and AI data centers scale into something more balanced. The latest quarter and Q1 FY27 revenue guide of US$10.4b to US$11.2b keep that story intact but show how dependent near term sentiment still is on smartphones and chip input costs.
The key near term catalyst remains execution on the data center and automotive ramps, because those areas are starting to matter more to the mix and to how investors frame QUALCOMM’s future earnings power. The biggest current risk is that handset demand and rising manufacturing costs continue to pressure QCT margins faster than new programs, including AWS and other hyperscale wins, can contribute.
The SpaceX Starlink Mobile 5G infrastructure deal looks most relevant here. It extends QUALCOMM beyond devices into carrier grade 5G and AI ready networking, with deployment planned from 2027 and revenue contribution expected toward late fiscal 2027 and more fully in 2028. That timing lines up with management’s push to have non handset QCT revenue, including data center and automotive, carry more of the load.
This agreement also increases execution risk. QUALCOMM now has to deliver at scale on Starlink Mobile at the same time it ramps custom AI data center silicon for AWS and other hyperscalers, all while handset revenue and Apple modem exposure are under pressure. For you, the question is whether the combination of these long dated contracts offsets the margin squeeze and smartphone cyclicality that have driven the latest earnings reset.
QUALCOMM's current analyst narrative assumes revenue grows at 10.8% a year and points to earnings today of US$9.3b, rising to a consensus forecast of US$11.5b by 2029, an increase of about US$2.2b, with revenues projected to reach US$60.0b in the same year.
Uncover why QUALCOMM's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One more upbeat storyline around Qualcomm leans heavily on the AWS custom silicon deal as a potential swing factor. The most optimistic analysts were pencilling in about US$66.9b of revenue and US$11.8b of earnings by 2029, well above consensus. After this guidance reset and handset shock, those projections may shift. Use that range of views as a reminder to stress test several scenarios before deciding how this reset fits your own thesis.
Explore 3 other QUALCOMM fair value estimates, including one that suggests potential upside of as much as 17% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your QUALCOMM research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QUALCOMM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QUALCOMM's overall financial health at a glance.
Looking for more investment ideas beyond QUALCOMM?
If this QUALCOMM reset has you reassessing where you want your capital working, consider casting the net wider and use the Simply Wall St Screener to line up a few clear comparisons before making your next move.
- If capital protection is front of mind, start with companies that pair resilient operations with muted risk scores by reviewing the 29 resilient stocks with low risk scores.
- For investors focused on quality at a reasonable entry point, scan businesses that combine strong fundamentals with attractive pricing using the 19 high quality undiscovered gems.
- If balance sheet strength matters most, compare firms with solid cash positions and manageable leverage through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com