


EN
Acadian Asset Management (AAMI), What Is Behind The Fresh Attention?
Acadian Asset Management (AAMI) drew fresh attention on October 29, 2026, as it paired a quarterly interim dividend of $0.10 per share with third quarter results showing higher revenue and net income.
At a share price of $90.96, Acadian Asset Management has cooled slightly over the past day and month. However, the 91.98% year to date share price return alongside a 1 year total shareholder return of 105.48% signals strong momentum that recent dividend and earnings news may be helping to sustain.
Scan how Acadian Asset Management compares with a hand picked group of quant driven financials and other fast moving managers in the 19 high quality undiscovered gems.
After a near 92% year-to-date climb and fresh earnings momentum, Acadian Asset Management now forces a harder call. Do you lean into the current price, or wait for a friendlier entry point as valuation gets unpacked next?
Price-to-Earnings of 26.5x: Is it justified?
Acadian Asset Management now trades on a P/E of 26.5x, which asks investors to weigh a premium to direct peers against strong recent share returns and earnings momentum.
The P/E ratio compares the current share price with earnings per share and effectively tells you how many dollars investors are paying for each dollar of profit. For an asset manager like Acadian Asset Management, that figure often reflects expectations around fee resilience, performance driven inflows, and how durable current profitability looks through a full cycle.
Here the picture is mixed. The business has delivered earnings growth of 38.7% over the past year after a period where profits declined by 5.3% per year over five years, so part of this multiple can be read as the market paying up for a rebound. At the same time, revenue growth is tied to forecasts of 14.3% per year, which is quicker than the wider US market at 13.2% per year but not in hyper growth territory, so the current P/E embeds a degree of confidence that the recent improvement in margins and returns on equity can be maintained.
Compared with the broader US Capital Markets industry average P/E of 36.7x, Acadian Asset Management trades at a clear discount. That positions the stock as cheaper than the wider sector on earnings, yet still markedly more expensive than its immediate peer group where the average multiple is 14.6x, which suggests investors are assigning this business a higher quality or higher growth profile than many direct comparables.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 26.5x (ABOUT RIGHT)
Still, the sharp 3 year and 5 year total returns, alongside a value score of 1, leave little margin for disappointment if sentiment on Acadian Asset Management cools.
Find out about the key risks to this Acadian Asset Management narrative.
Another View: SWS DCF flags a very different story
That 26.5x P/E paints Acadian Asset Management as reasonably priced against the broader Capital Markets group, yet the SWS DCF model points the other way. On that approach, an estimated future cash flow value of $10.35 per share versus a $90.96 price suggests the stock screens as very overvalued.
The gap between a seemingly fair earnings multiple and a much lower cash flow estimate leaves you with a clear question: Do you trust the recent profit rebound to support today’s price, or does the DCF view make you more cautious about paying up at this level?
Look into how the SWS DCF model arrives at its fair value.
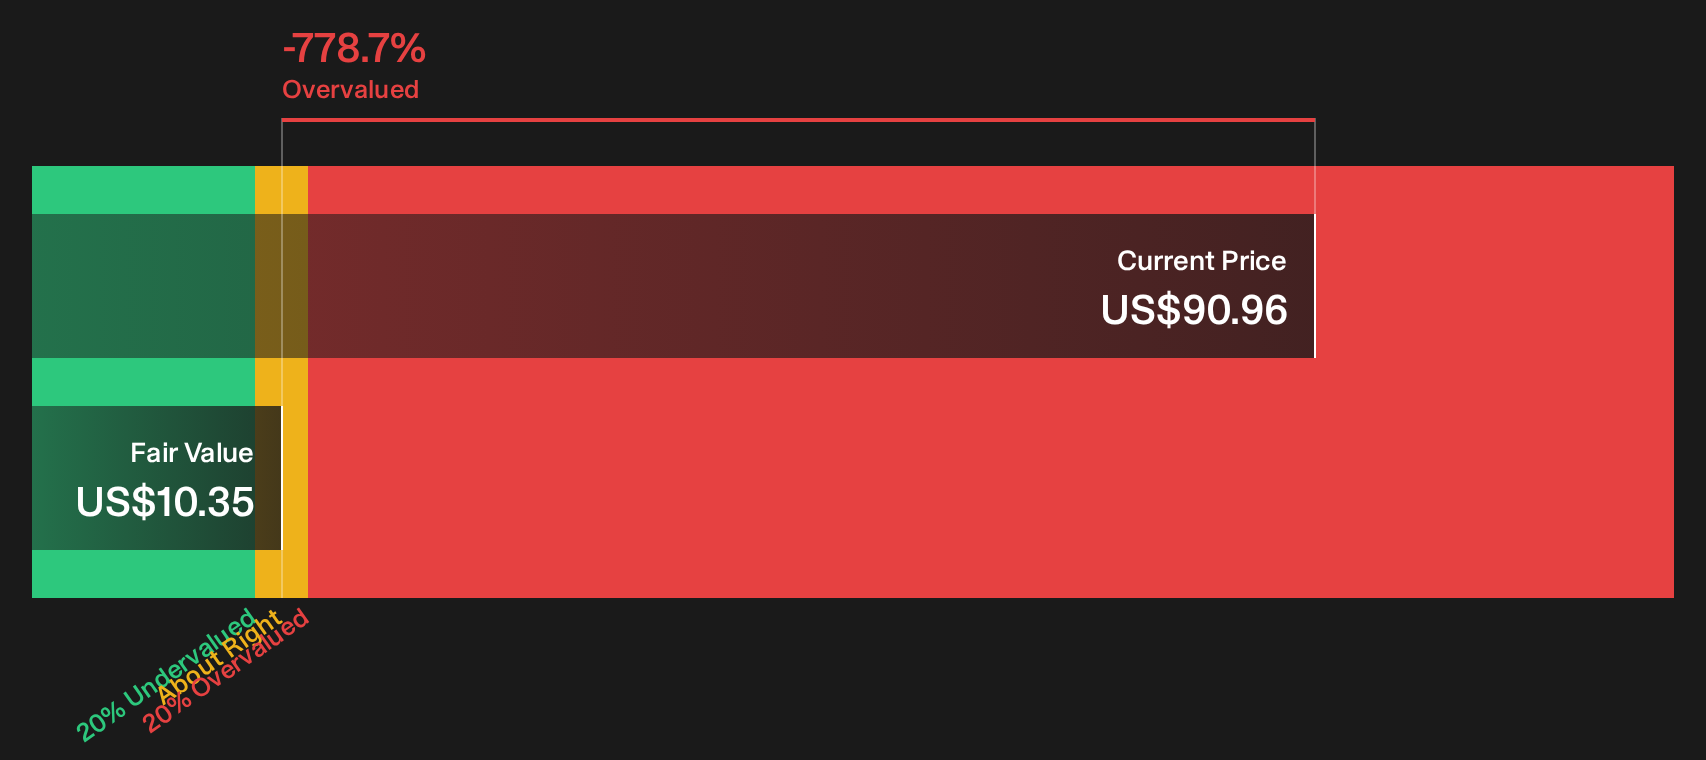
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Acadian Asset Management for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Acadian Asset Management so far. If you want to move with conviction rather than headlines, pressure test both sides of the story by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Acadian Asset Management?
Do not stop your research with Acadian Asset Management. Broaden your watchlist now so you are not chasing the next opportunity after it has already moved.
- Target potential value opportunities by scanning companies that combine quality fundamentals with room for re rating in the 39 high quality undervalued stocks.
- Zero in on resilient businesses by focusing on a list of solid balance sheet and fundamentals (24 results) that can better handle tougher conditions.
- Strengthen your income shortlist by reviewing a hand picked set of 8 dividend fortresses built around higher yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com