


EN
Should Lowered 2026 Outlook Require Action From Molson Coors (TAP) Investors?
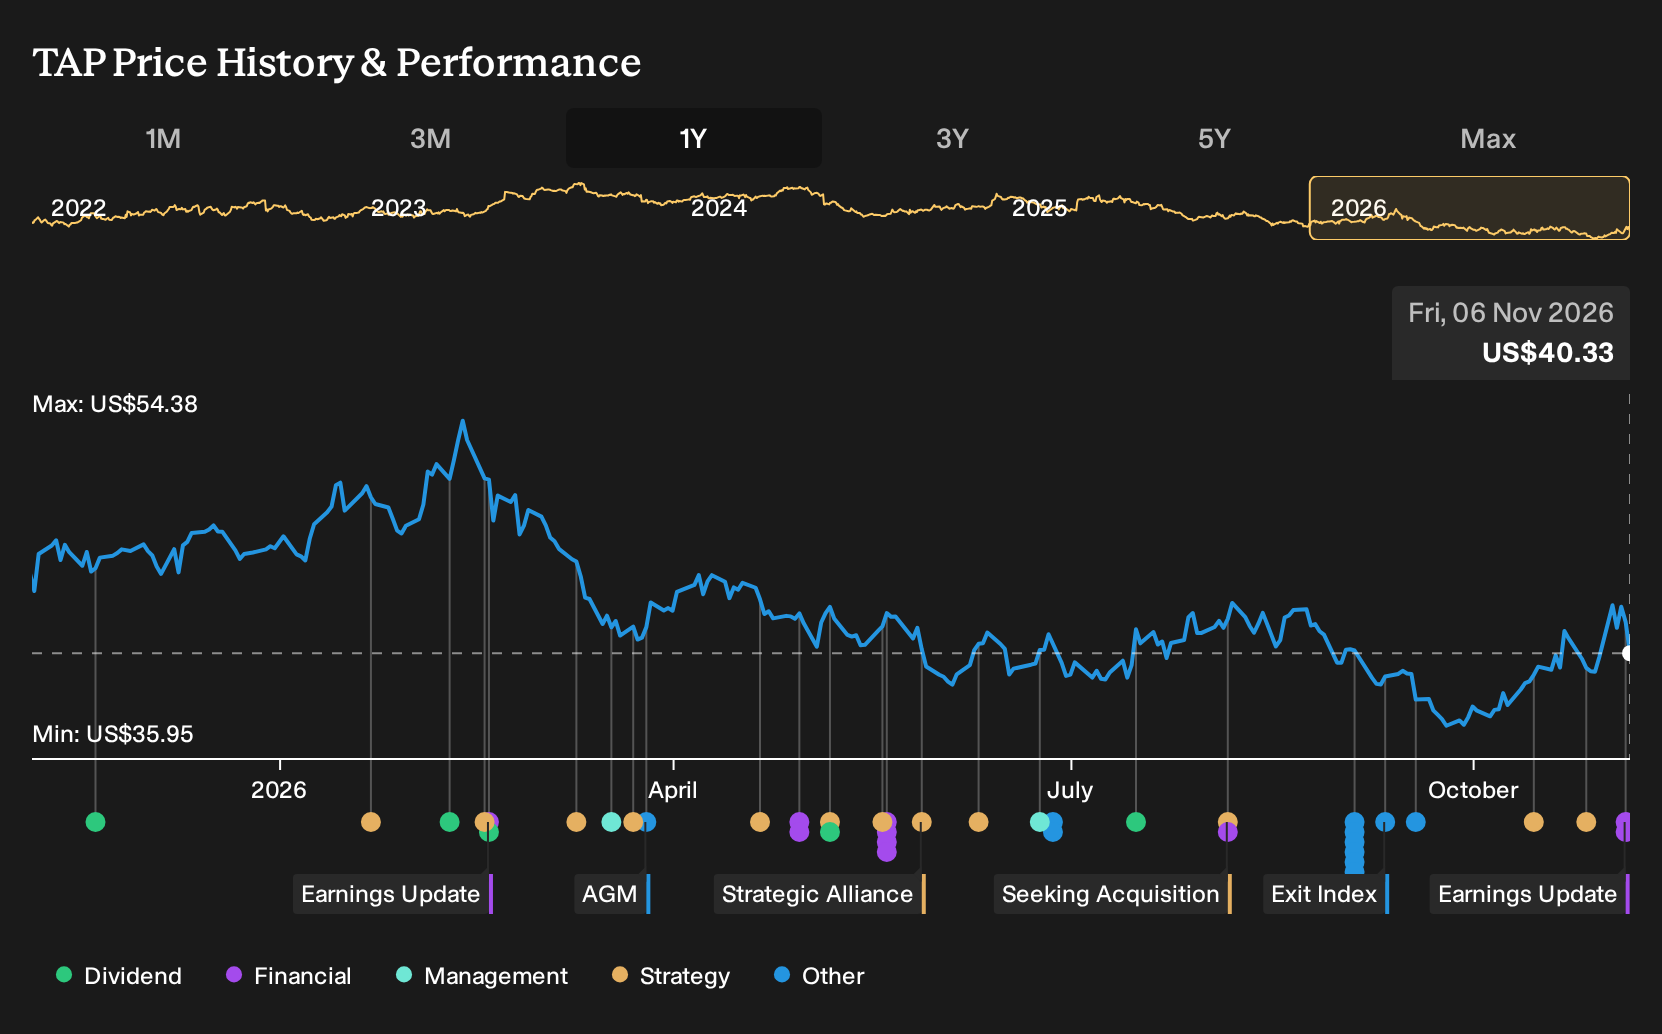
- Molson Coors Beverage reported third quarter 2026 results with sales of US$3,404.9 million and net income of US$271.5 million, and at the same time cut full year 2026 guidance, now expecting constant currency net sales to decline 1% to 2% and underlying EPS to fall 16% to 19% versus 2025.
- While cost and demand pressures led to lower guidance, Molson Coors is still running a US$450 million cost savings program and supply chain restructuring. Management aims to use these initiatives to offset inflation in commodities, freight and fuel that have been weighing on profitability.
- We will now look at how Molson Coors Beverage's investment narrative might shift given the lowered 2026 guidance tied to softer demand.
Compare Molson Coors Beverage's setup with other consumer stocks facing similar cost and demand pressures by scanning our hand picked 39 high quality undervalued stocks, which may offer stronger risk reward trade offs.
Molson Coors Beverage Investment Narrative Recap
For Molson Coors Beverage, shareholders need to be comfortable with a beverage group that is profitable again but operating in a structurally softer beer category. The near term belief test is whether the US$450 million cost savings and supply chain work can keep earnings intact while sales guidance now points to a 1% to 2% constant currency decline and a steeper EPS drop versus 2025.
The biggest short term swing factor remains execution on those cost actions, because input inflation in aluminum, freight and fuel is still biting and Midwest Premium costs are a clear drag. The key risk is that category volume pressure, competitive discounting in markets like the U.K., and softer US shipments keep outpacing mix upgrades into above premium and beyond beer products.
The most relevant update here is the lowered 2026 outlook that came alongside Molson Coors Beverage’s third quarter numbers. Management now expects constant currency net sales to fall 1% to 2% and underlying EPS to decline 16% to 19% against 2025, and also flagged weaker underlying pre tax income and free cash flow for the year.
That reset directly links to the main catalysts investors often watch, which are the cost savings plan, supply chain restructuring and brand mix shift. If the US$450 million program and Horizon 2030 execution stay on track, those moves can still influence margins and cash generation, but the updated guidance underlines how exposed the business remains to beer volume pressure and persistent input cost volatility.
Molson Coors Beverage's current earnings are a loss of US$2.3b, while analysts expect earnings to reach US$956.9 million by 2029. This implies an earnings swing of about US$3.3b, and an analyst consensus that revenues in that year will be US$11.2b.
Uncover why Molson Coors Beverage's fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on Molson Coors Beverage’s revenue trend. The most bearish analysts were already assuming sales would slip about 1.1% a year to roughly US$10.7b by 2029, even as earnings climbed toward US$1.0b. After this guidance cut, that more pessimistic narrative may gain weight. Compare both sets of expectations before deciding what feels realistic to you.
Explore 4 other Molson Coors Beverage fair value estimates, including one that suggests it could be worth just $43.62.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Molson Coors Beverage research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Molson Coors Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Molson Coors Beverage's overall financial health at a glance.
Looking for more investment ideas beyond Molson Coors Beverage?
If Molson Coors Beverage is only one piece of your watchlist, it can help to line it up against other opportunities with different strengths, risk profiles and income characteristics using the Simply Wall St Screener.
- For investors who care most about balance sheet resilience and fundamental strength, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without stretching its finances.
- If capital preservation sits high on your list, compare Molson Coors Beverage with a 29 resilient stocks with low risk scores that scores well on stability and business quality.
- Those hunting for less crowded opportunities can scan a 19 high quality undiscovered gems that combine strong underlying metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com