


EN
Is Sprott (TSX:SII) Fully Valued Following Strong Q3 Results And A Dividend Increase?
Sprott (TSX:SII) just posted fresh third quarter results, with management pairing higher revenue and net income with another increase to the regular dividend and an emphasis on critical materials investment products.
The fresh earnings beat and dividend lift have coincided with a sharp pick up in momentum, with Sprott’s share price up 2.19% on the day and 13.72% over the past week, while the 1 year total shareholder return of 29.06% and the very large 3 year total shareholder return near 4x indicate that long term holders have already experienced strong compounding.
Scan beyond Sprott’s earnings beat and dividend lift by checking out 33 best rare earth metal stocks that focus on the same critical materials theme attracting fresh investor attention.
Sprott’s latest jump and long run of strong total returns raise a simple question: Is the real opportunity still ahead at CA$161.11, or has most of the upside already played out on this move?
Price-to-Earnings of 25.7x: Is it justified?
Sprott now trades on a P/E of 25.7x, which puts the CA$161.11 share price on a much richer footing than both its industry and peer averages.
The P/E ratio compares what investors pay for each dollar of current earnings. For an asset manager like Sprott, that figure often reflects how confident the market feels about the durability and quality of those profits.
High quality earnings, a 27.2% return on equity and profit growth of 29.2% per year over five years indicate that investors are paying up for a business that has converted past performance into stronger profitability. That sort of earnings profile can justify a premium P/E when investors are comfortable that margins and returns on equity can be supported.
The gap to the broader Canadian Capital Markets group is wide. Sprott trades at 25.7x earnings, while the industry average is 7.9x and the peer group average is 8.1x, which signals that the market is assigning a much higher valuation to its profit stream than it does to comparable firms.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 25.7x (OVERVALUED)
Still, the recent 1 year and 3 year total shareholder returns, together with a richer 25.7x P/E, could leave Sprott exposed if revenue pressure persists or sentiment toward critical materials cools.
Find out about the key risks to this Sprott narrative.
Another View: Our DCF model points the other way
The P/E story paints Sprott as expensive, yet our DCF model says something very different. At CA$161.11, the share price sits well above an estimated future cash flow value of CA$52.11. This frames the stock as heavily overvalued on this second lens.
This kind of gap can matter in practical terms. If cash flows do not stretch to meet that richer market price, investors are relying on sentiment and optimism to keep the multiple where it is or push it higher. That sets up a simple question for anyone looking at Sprott today: Which signal feels more reliable, the premium P/E or the discounted cash flow math?
Look into how the SWS DCF model arrives at its fair value.
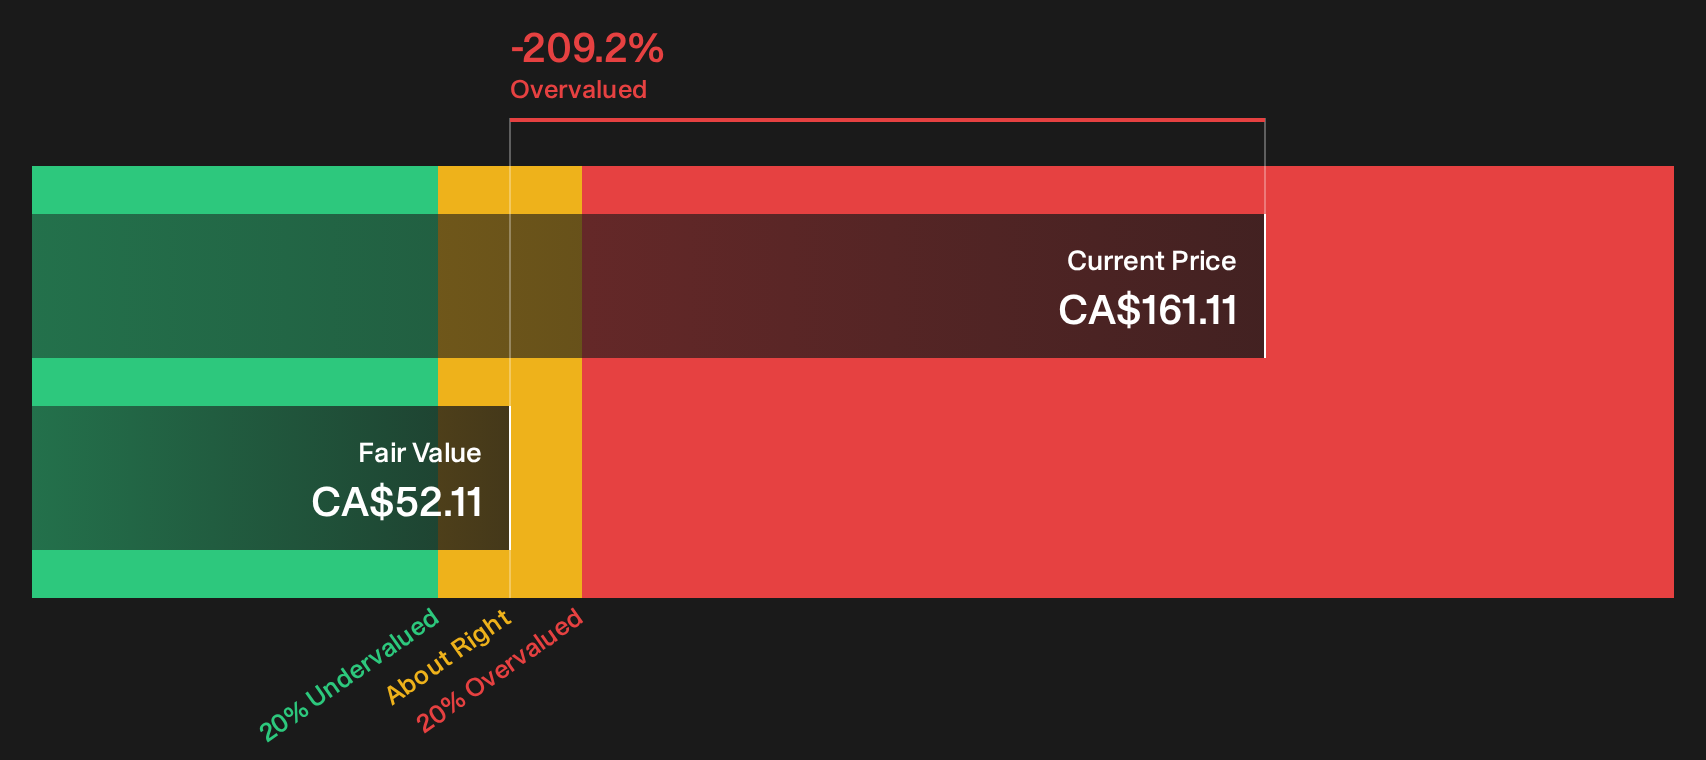
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sprott for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the combination of strong past returns and a rich valuation leaves you uncertain, act while the numbers are fresh and test the thesis yourself by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sprott?
Do not stop with just one ticker. The real edge comes from lining up multiple quality ideas and comparing them side by side before moving any cash.
- Target potential mispricing by scanning a 6 high quality undervalued stocks that highlights companies where quality metrics and current prices tell very different stories.
- Lock in more predictable income streams by reviewing a 3 dividend fortresses built around businesses that pair higher yields with consistent payout records.
- Reduce portfolio stress by filtering for a 9 resilient stocks with low risk scores that screens companies with sturdier financial profiles and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com