


EN
Methanex (TSX:MX) Stock Looks Cheap Against Its Cash Flow Outlook
Methanex has had a strong share price run over the past year, which naturally puts a spotlight on whether that move is supported by the cash the business can generate. With the stock now reflecting fresh news on production decisions and capital returns, the question becomes how far the current price leans on its existing and future cash flows.
- The share price is up 81.3% over the past year, so anyone looking at Methanex today is effectively asking whether that rise already embeds the cash flows the business is likely to produce.
- Recent decisions to idle certain plants while maintaining large scale methanol production and repurchasing shares can reshape future cash generation, timing and capital intensity, which all matter for an intrinsic value anchored in cash flows.
- If you'd rather focus on earnings, this one's for you. See why Methanex's 14.2x P/E tells a different valuation story.
For investors, the debate is whether Methanex's current share price is adequately supported by the cash flows implied by a Discounted Cash Flow (DCF) view of the business.
If you are comparing Methanex's recent cash flow story with other opportunities, it can help to line it up against companies in the 6 high quality undervalued stocks.
Is Methanex Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at the cash Methanex can return to shareholders over time and then discounts it back to today. The model starts from last twelve month free cash flow of about $1.3b, which already reflects Methanex's current methanol footprint and recent capital decisions.
Projected free cash flow in the late 2020s trends lower than that recent $1.3b figure, so the valuation leans on a recovering then declining cash profile rather than aggressive expansion. Despite record North American production, strong recent earnings and a CA$93.77 share price, the DCF projections put Methanex's estimated intrinsic value substantially above the current share price. Because the announced plant idlings, bond redemption and 5% share repurchase program all feed directly into future cash flows and equity claims, they help explain why a cash flow based model still points to more value than the market is currently pricing in. Find out what Methanex could be worth using our Discounted Cash Flow (DCF) estimate.
The Methanex Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St take that Methanex valuation puzzle and spell out which paths for future growth, profitability and earnings would need to play out for the shares to be worth meaningfully more or less than today’s price, all within the Community page. Each idea treats Methanex's fair value as a thesis that can be tracked over time rather than a one off snapshot, so you can see how the story holds up as new information arrives.
One of the top community narratives on Methanex: roughly fairly valued
"The OCI acquisition expands capacity and market reach, improving earnings and operational efficiency while deleveraging strengthens financial stability…"
Discover why this Narrative puts Methanex at roughly fairly valued.
One more Methanex signal worth checking before you move on
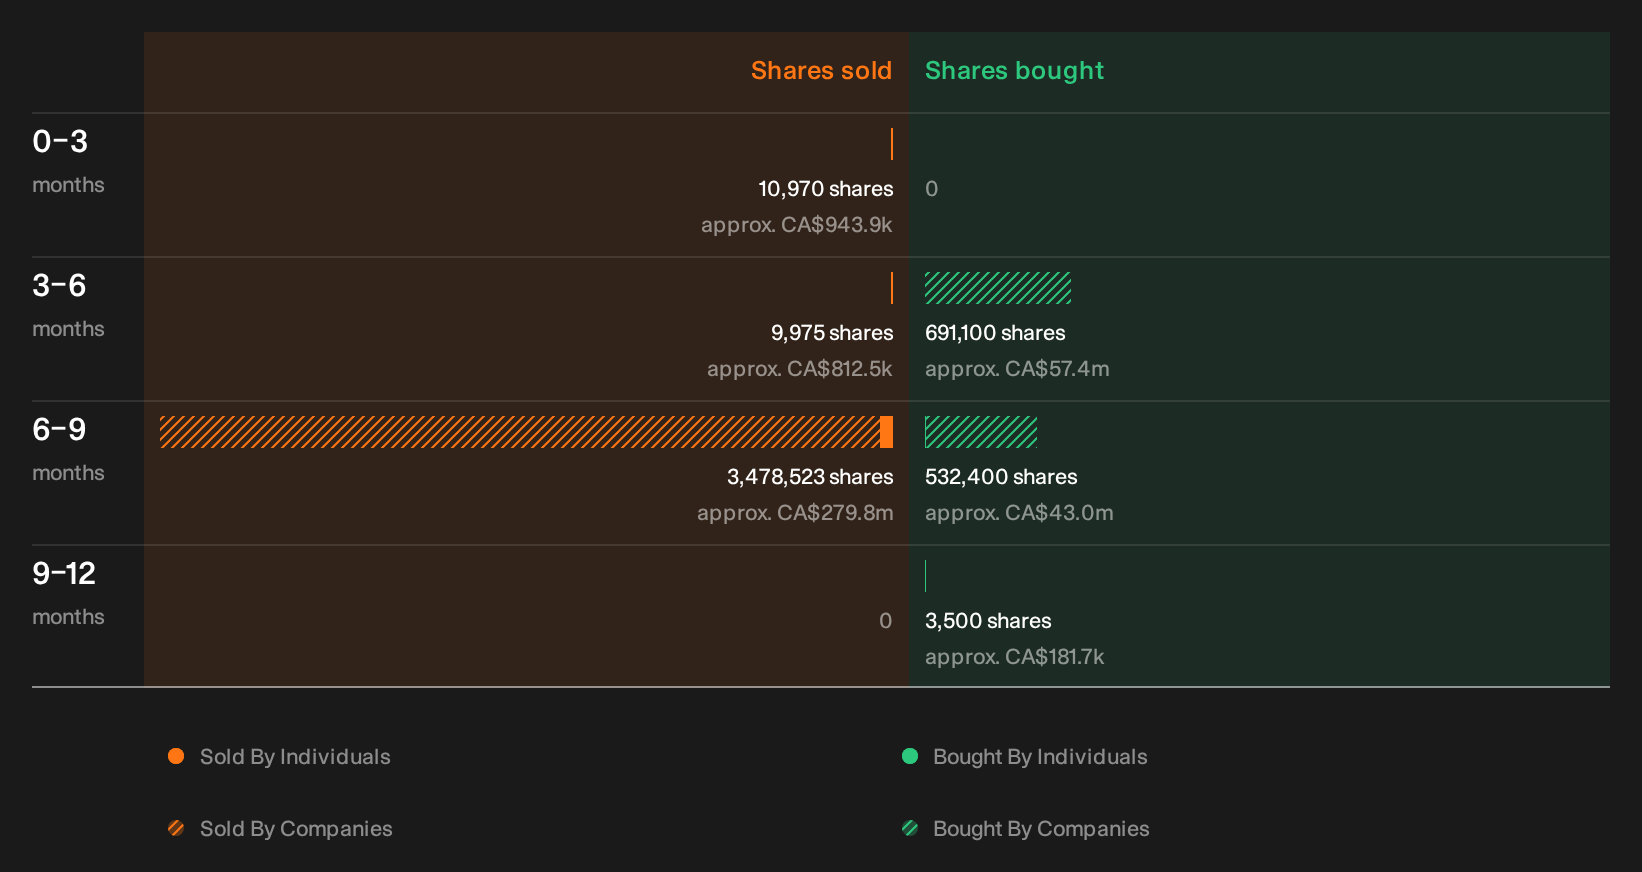
There is a fresh clue sitting outside the cash flow models, because recent trading by people inside Methanex has been flagged and the identities, amounts and possible read across are still for you to unpack. See the recent insider selling flagged for Methanex.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com