


EN
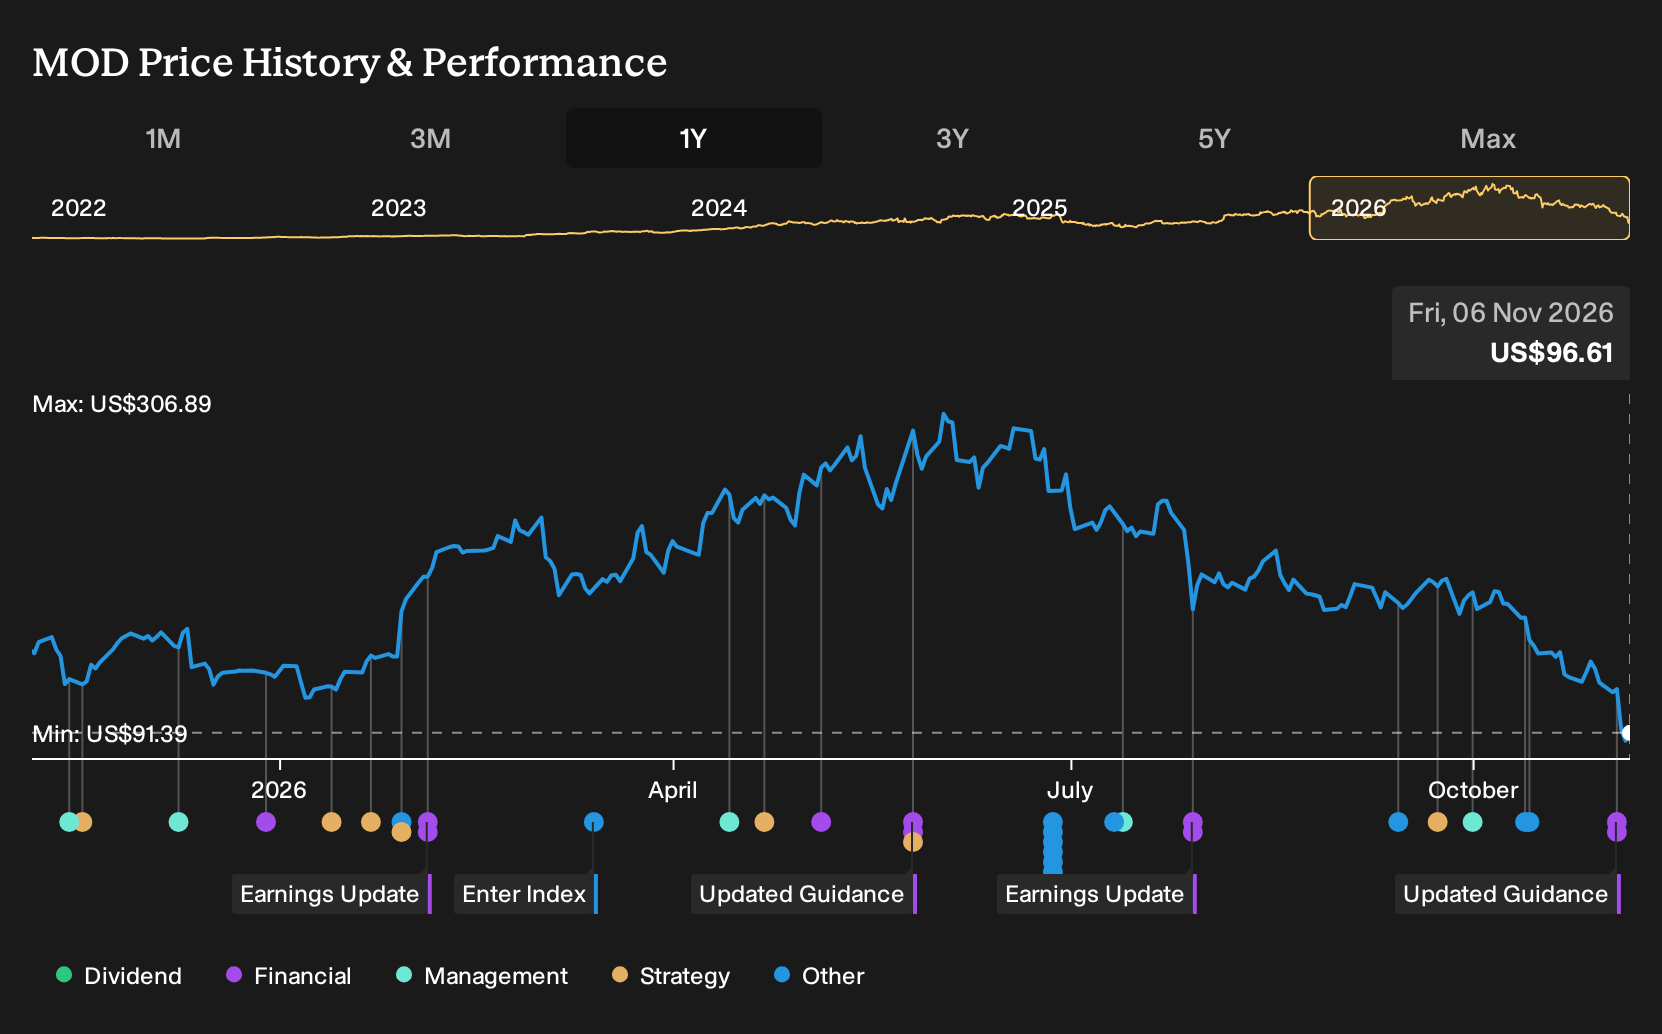
Why Modine Manufacturing (MOD) Is Up 5.7% And What's Next After Record Data Center Orders
- Modine Manufacturing recently reported fiscal 2027 guidance for net sales of US$3.1b to US$3.2b and released second quarter 2026 results showing higher sales but lower quarterly net income and diluted EPS from continuing operations compared with the prior year period.
- The latest update highlights sharp momentum in Modine Manufacturing's data center activity, with nearly doubled segment revenue, record quarterly orders above US$1b, and a new multi year hyperscaler program exceeding US$400 million.
- We will now look at how Modine Manufacturing's investment narrative could shift given the record data center orders and upgraded outlook.
Scan 52 AI infrastructure stocks to see which other thermal and power players could benefit if Modine Manufacturing’s data center build out momentum spills over across the sector.
Modine Manufacturing Investment Narrative Recap
To own Modine Manufacturing today, you need to accept a story built on heavy data center exposure and a mixed margin picture. The fiscal 2027 net sales outlook of US$3.1b to US$3.2b and record data center orders frame the upside. The key short term catalyst is turning that backlog into higher margin shipments without further supply chain friction.
The biggest risk is that material costs, logistics issues, or pricing on new contracts keep squeezing profitability, as Q2 showed with lower quarterly net income and diluted EPS despite higher sales. Recent guidance lifts the growth ceiling but does not remove those execution and cost pressure concerns.
The most relevant fresh update is the earnings release for the quarter and first half ended 30 September 2026. Sales reached US$994.4m in Q2 and US$1,868.5m for six months, while quarterly net income and diluted EPS from continuing operations trailed the prior year. That mix of strong top line and softer earnings is exactly what investors are watching.
For someone tracking catalysts, that report ties directly to the data center surge and capacity expansion story. It shows Modine Manufacturing converting demand into revenue but still working through margin and cash burn issues. The key question now is whether management can translate the larger 2027 sales outlook and record orders into cleaner profitability as supply and pricing actions take hold.
Analysts see Modine Manufacturing reaching US$4.9b in revenue and US$696.9m in earnings by 2029, based on forecasts that assume 12.9% yearly revenue growth and an earnings increase of about US$552.7m from US$144.2m today.
Uncover why Modine Manufacturing's fair value indicates a 201% potential upside to its current price, which may not last much longer.
Exploring Other Perspectives
One alternate story around Modine Manufacturing focuses on customer concentration risk rather than supply chains. The most pessimistic analysts already assumed revenue of about US$5.1b and earnings of roughly US$1.1b by 2029, yet only on a low 15x P/E. Those forecasts came before this guidance and Q2 data center surge, so expectations could shift again.
Explore 3 other Modine Manufacturing fair value estimates, including one that suggests it could be worth just $183.13!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Modine Manufacturing research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Modine Manufacturing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Modine Manufacturing's overall financial health at a glance.
Looking For More Investment Ideas Beyond Modine Manufacturing?
If Modine Manufacturing has sharpened your interest in data center and thermal infrastructure, it can help to widen the lens and see how other businesses stack up on quality, value, and resilience. The Simply Wall St Screener offers a range of pre built filters that let you quickly surface stocks that fit very different objectives, from stability to income to long term compounding potential.
- If you want potential value opportunities with quality fundamentals, sort through 39 high quality undervalued stocks that might meet your return and risk criteria.
- For investors who care most about balance sheet strength and financial resilience, scan the list of solid balance sheet and fundamentals (24 results) to see which companies keep debt and funding risk in check.
- If you prefer under the radar opportunities with healthier fundamentals, review the 19 high quality undiscovered gems that could warrant a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com