


EN
Comstock Resources (CRK) Updates Earnings And Credit Facility, Is It Still Undervalued?
Comstock Resources (CRK) just paired its third quarter 2026 production and earnings release with a fresh amendment to its bank credit facility. This combination puts output trends and financing terms in clear focus for investors.
Comstock Resources’ latest moves come after a tough stretch for holders, with the share price down 43.13% year to date and the 1 year total shareholder return declining 41.75%, even though the 5 year total shareholder return of 52.77% points to a much stronger longer run performance. Recent production growth, the SOCAR divestiture agreement and the extended bank facility help explain why some investors may see recent share price weakness, including a 7 day share price return of down 8.90% and a 30 day share price return of down 2.69%, as more about shifting risk perceptions around gas prices and leverage than about the long term earning power of Comstock Resources.
Spot opportunities beyond Comstock Resources by scanning a curated 42 power grid technology and infrastructure stocks that could benefit from the same long term demand drivers behind rising gas, LNG and data center energy needs.With Comstock Resources trading at a steep discount to both analyst targets and one intrinsic estimate, the real puzzle is whether the price or the valuation range is out of line.
Most Popular Narrative: 12% Undervalued
On the most followed narrative, Comstock Resources screens as undervalued, with a fair value of $15.23 against a last close of $13.41. The gap rests on how durable investors think the Western Haynesville production and infrastructure story really is.
The company's proactive development of Western Haynesville specific midstream infrastructure (such as a major new gas treating plant) will allow for higher production levels, improved price realizations, and increased ability to capitalize on expanding U.S. LNG export capacity, thereby supporting revenue growth.
The recently announced strategic collaboration with NextEra Energy for potential gas-fired power and data center projects near Western Haynesville leverages proximity to major demand centers and existing infrastructure. This could unlock new high-margin, long-term sales channels and provide additional stable cash flows.
See why 10 investors see Comstock Resources as 12% undervalued.
Result: Fair Value of $15.23 (UNDERVALUED)
Still, the whole Comstock Resources story leans heavily on a single gas basin and ongoing heavy investment, so any regional supply shock or cost creep could quickly challenge the current undervaluation case.
Find out about the key risks to this Comstock Resources narrative.
Another View: Comstock Resources Through The Earnings Multiple Lens
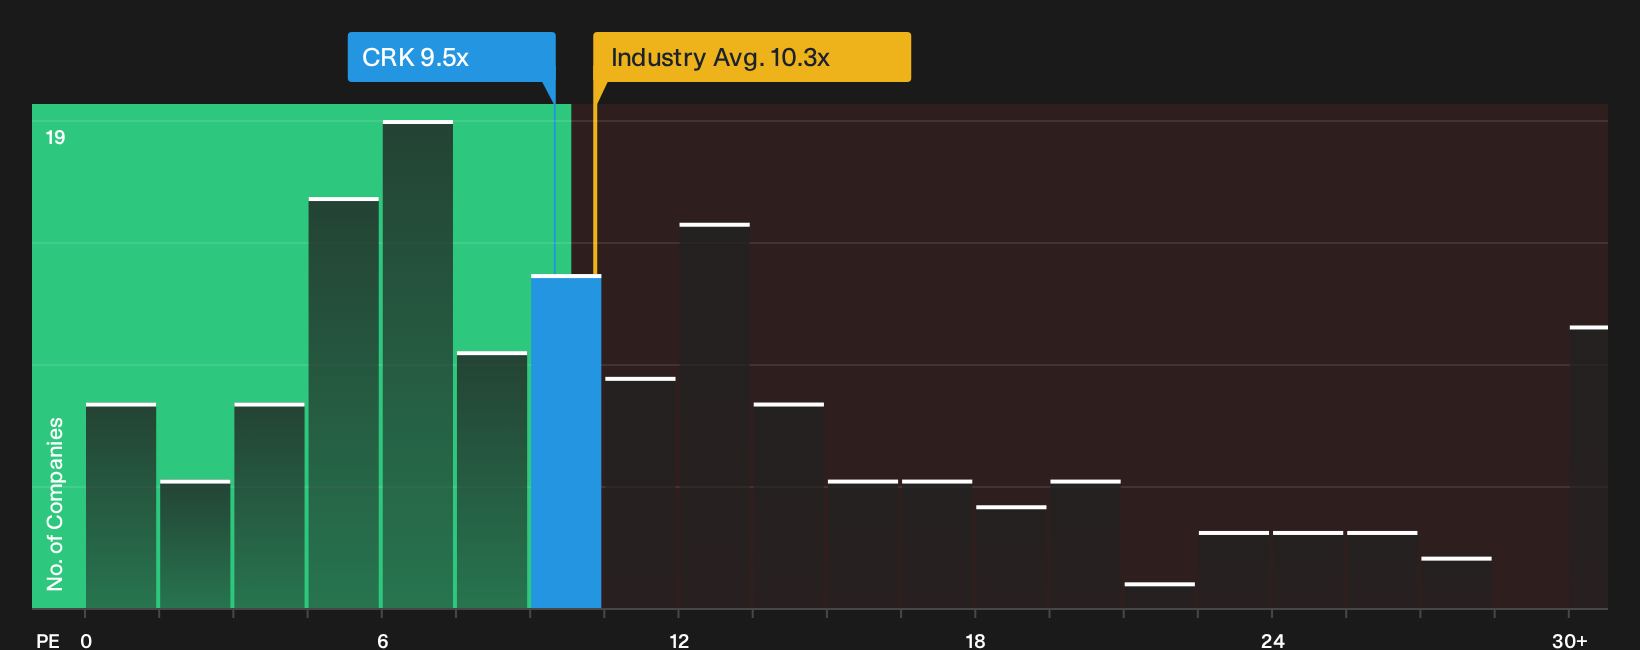
There is a catch. While the narrative suggests Comstock Resources is undervalued, the current P/E of 9.5x sits above its fair ratio of 7.8x, even though it is lower than the US Oil and Gas industry at 11.1x and peers at 10.9x. Is that discount enough if earnings are expected to decline?
For a closer look at how that P/E gap could close over time, including whether the market might shift toward the fair ratio or industry levels, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Opinions are mixed about whether Comstock Resources is being unfairly punished or reasonably discounted right now. Act quickly, stress test the data yourself, then weigh up the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Comstock Resources?
Do not stop your research with Comstock Resources. Broaden your watchlist with data driven ideas that match your risk, income, and quality preferences using the Simply Wall St screener.
- Target mispriced opportunities by running through a curated 39 high quality undervalued stocks that surfaces stocks where fundamentals and current prices look out of sync.
- Strengthen your income stream by scanning a focused 8 dividend fortresses built around companies offering higher yields with supporting fundamentals.
- Dial down volatility by filtering for a 29 resilient stocks with low risk scores that highlights businesses with more resilient balance sheets and risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com